
Publication 527 residential rental property rules determine how rent, deductions, depreciation, and losses actually land on your tax return. That matters because the difference between a deductible rental loss and a trapped passive loss, or between a repair and a capital improvement, changes after-tax cash flow, audit exposure, and portfolio ROI in a very real way.
Why Publication 527 Matters to Rental Property ROI
Rental property performance is never just about gross rent and mortgage payment. After-tax cash flow is shaped by how income is classified, which expenses are deducted now, which costs are capitalized and depreciated later, and whether current-year losses are usable at all. Publication 527 sits at the center of that framework for individual owners of residential rentals.
The strategic stake is straightforward. In a market where median asking rent has softened nationally and vacancy has risen in many metros, tax efficiency carries more weight because pricing power is weaker. Softer rents do not change federal tax rules, but they make classification mistakes more expensive. If revenue growth slows while carrying costs stay high, every lost deduction and every suspended loss has a direct ROI effect.
Four drivers control most outcomes under Publication 527. First is income classification, meaning what counts as rental income and when it is reported. Second is expense treatment, meaning what is deductible now versus depreciated over time. Third is loss limitation, because many landlords discover that an economic loss does not create a current tax benefit. Fourth is law change awareness, especially for 2026 and 2027, when broader individual tax rules affect the economics around the core rental framework.
What Publication 527 Covers
Publication 527 is the IRS guide for residential rental property. It explains how to report rental income, claim deductible operating expenses, depreciate the building and qualifying assets, handle casualty and theft issues where applicable, apply personal-use rules to vacation or mixed-use property, and connect those rules to the actual tax return. The IRS description states that it covers rental income and expenses, depreciation, casualty losses, and the passive activity and at-risk rules.
That said, Publication 527 is guidance, not the legal authority itself. The controlling law comes from the Internal Revenue Code, Treasury regulations, IRS forms and instructions, rulings, and court decisions. Publication 527 tells you how the IRS expects the rules to be applied in common residential rental situations. It is an operating manual, not the statute.
Who Should Use Publication 527
If you own a single-family rental, duplex, condo, co-op, small multifamily property, or vacation home rented to others, Publication 527 is directly relevant. It is especially important if your return includes any of the issues that repeatedly cause confusion: mixed personal and rental use, passive losses, converted former residences, short-term or seasonal occupancy patterns, or depreciation tracking.
This matters most for three groups. First, W-2 earners with rental losses that are limited by passive activity rules. Second, owners of vacation or mixed-use homes whose personal-use days change the entire deduction framework. Third, investors evaluating Real Estate Professional Status because the tax value of that decision depends on whether suspended losses can become current deductions.
What Publication 527 Does Not Decide by Itself
Publication 527 does not resolve every technical limitation. If rental losses are limited, Publication 925 and Form 8582 usually control the passive activity analysis. If deductions are limited by investment at risk, Form 6198 becomes part of the file. If depreciation is involved, Form 4562 often sits alongside the rental schedule, and rental results generally flow through Schedule E.
That boundary matters. Publication 527 tells you what belongs in the rental activity. Other forms determine whether the loss is currently deductible.
The Three Core Classification Rules That Drive Every Rental Return
Most rental tax outcomes trace back to three classifications. What counts as rental income. What counts as a current expense versus a capital expenditure. Whether the property is being used as a rental, a residence, or a mixed-use dwelling.
Errors in these categories create the largest compliance and cash-flow problems because they affect multiple lines at once. Understate rental income and the return is inaccurate from the start. Deduct an improvement as a repair and current-year taxable income drops improperly, but basis and future recapture are also wrong. Miscount personal-use days and an apparent full-rental property becomes a dwelling used as a home, which changes deduction ordering and can cap losses at gross rental income.
Rule 1: What Counts as Rental Income
Rental income is broader than monthly rent checks. It includes regular rent, advance rent, lease cancellation payments, security deposits that are kept, nonrefundable fees, tenant payments of your expenses, and the value of services received instead of cash rent. Publication 527 also treats advance rent and service fees as rental income that must be reported.
Under the cash method, which most individual landlords use, income is generally recognized when received, not when earned. That timing rule surprises owners who collect the last month’s rent upfront in December for occupancy beginning in January. If the cash arrives in December, the income belongs to December’s tax year. The same applies to prepaid lease amounts and many nonrefundable fees.
Rule 2: What Counts as a Deductible Rental Expense
A deductible rental expense must be ordinary, necessary, and connected to the rental activity. Standard examples include mortgage interest, property taxes, insurance, utilities, advertising, repairs, maintenance, supplies, management fees, cleaning, commissions, and professional fees directly related to operating the property.
Connection to the rental activity is the governing principle. If the expense is tied to keeping the property rented, marketable, habitable, or legally compliant, it generally belongs in the rental bucket. If it benefits a personal-use portion of the property, it must be allocated. If it creates or improves a long-term asset, it usually is not a current expense at all.
Substantiation matters just as much as category. An expense that would be deductible in theory often fails in practice because there is no invoice, no business purpose, no property-level coding, or no separation between personal and rental spending.
Rule 3: When a Cost Must Be Capitalized Instead of Deducted
The repair-versus-improvement line determines tax timing. A repair is usually deducted now. An improvement is capitalized and recovered over time through depreciation. That means the same $12,000 spend can either reduce this year’s taxable income immediately or be spread across years, depending on what the work actually did.
The IRS framework turns on whether the work bettered the property, restored it, or adapted it to a new or different use. If it did, capitalization is the rule. If it merely kept the property in ordinarily efficient operating condition, current deduction is generally proper. That distinction drives current-year cash flow, examination risk, and future gain calculations.
How to Determine Whether a Property Is a Residential Rental Property
Before dealing with deductions and losses, you need to know what the property is for tax purposes. The label matters because residential rental property carries a specific depreciation life, specific allocation rules, and specific vacation-home limitations if there is personal use.
A full-time rental with no personal use is straightforward. A former residence converted to rental status is more technical. A beach house rented seasonally with owner weekends mixed in is where mistakes multiply. Publication 527 is built around those distinctions.
Residential Rental Property for Tax Purposes
For depreciation purposes, residential rental property generally means a building where 80 percent or more of gross rental income comes from dwelling units and the normal rental period is 30 days or more. If the test is met, the building is depreciated as residential rental property under MACRS over 27.5 years.
This matters because depreciation life changes taxable income every year you own the property. A property that qualifies as residential rental property receives the standard 27.5-year recovery period for the building, not the 39-year life used for nonresidential real property.
Long-Term Rentals vs. Vacation and Mixed-Use Properties
A long-term rental is usually the cleanest case. If the property is held out for rent, occupied by tenants, and not used personally, most ordinary and necessary rental expenses are deductible, depreciation applies, and losses are then tested under passive and at-risk rules.
Vacation and mixed-use properties are different because personal use changes the framework. Once owner or family use enters the picture, deductions have to be allocated between rental and personal use, and if the dwelling is treated as a home, rental deductions can be capped. That is where the three-tier system becomes decisive.
Tier 1 is the narrow tax-free rental rule. If a beach house is rented for 12 days at $500 per night, gross rent is $6,000. Because the property is rented fewer than 15 days during the year, the $6,000 is not reported as rental income. No rental deductions are allowed. Mortgage interest and property taxes remain personal items if otherwise deductible, but there is no Schedule E rental activity from those 12 days.
Tier 2 is the mixed-use tier. If a property is rented 60 days and used personally 20 days, the personal-use threshold is met because 20 days exceeds the greater of 14 days or 10 percent of rental days. Ten percent of 60 rental days is 6 days, so the threshold is 14, and 20 is over it. That means the dwelling is used as a home. Expenses must be allocated. If annual expenses total $24,000 and are allocated based on days of use, 60 rental days out of 80 total use days produces a 75 percent rental allocation. In that example, $18,000 is allocable to rental use and $6,000 to personal use, subject to the ordering limits for a dwelling used as a home.
Tier 3 is the pure rental tier. If a property is rented 300 days and has zero personal-use days, there is no vacation-home limitation. Rent is fully reported, operating expenses are fully deductible against rental income, depreciation is claimed in full for the rental period, and any resulting loss is then tested under passive and at-risk rules.
Rental Income: What Must Be Reported and When
Owners often focus on deductions because deductions feel like savings. But underreporting income creates the faster problem. The IRS expects gross rental income to include more than just base rent, and cash-method timing rules pull income into the year received.
That means year-end collections deserve close attention. Lease structure also matters because the tax result for a refundable deposit is not the result for a nonrefundable fee, and the result for a tenant-paid utility bill is not the result for a tenant paying your mortgage escrow shortage.
Advance Rent, Last Month’s Rent, and Prepaid Amounts
Advance rent is taxable when received. It does not wait until the lease period begins. If a tenant signs in December 2026 and pays January 2027 rent plus the final month’s rent upfront, both amounts are generally included in 2026 income if they are rent and you are a cash-method taxpayer.
The planning consequence is simple. Accelerated collections accelerate taxable income. In a high-income year, that can create a surprising tax bill. In a lower-income year, it can be useful. But it is not elective once the cash is in hand.
Security Deposits: Refundable vs. Retained
A true security deposit is not income when received if there is an obligation to return it. The tax result changes when the deposit is retained because of damage, unpaid rent, or lease default. At that point, the retained amount generally becomes rental income.
The distinction turns on legal obligation. If the payment is labeled a deposit but is nonrefundable from day one, it is not functioning like a deposit. It is prepaid income. Owners regularly get this wrong because the lease says “deposit” while the economic substance says fee.
Tenant-Paid Expenses and Barter Arrangements
If a tenant pays one of your obligations, the payment is generally treated as rental income to you. If a tenant repairs a fence instead of paying one month of rent, the value of the services is still rental income. If a tenant pays the water bill that legally belongs to you under the lease, that payment is treated as rental income, and you generally take the offsetting rental expense if otherwise deductible.
Barter arrangements deserve special caution because no cash movement can make the transaction feel invisible. It is not. Rent satisfied with services remains rent for tax purposes.
Expenses Paid by a Tenant for Services
There is an important distinction between a tenant paying for services directly and a tenant reimbursing you. If the tenant sets up electric service in the tenant’s own name and pays the utility company directly, that is usually just the tenant’s personal expense, not your rental income and not your deduction. But if you pay the utilities and the tenant reimburses you under the lease, that reimbursement generally belongs in rental income and the utility cost remains your rental expense.
The same logic applies to internet, lawn care, trash service, and other billed items. The tax treatment follows who has the legal obligation and how the lease is structured.
Deductible Rental Expenses Under Publication 527
Publication 527’s practical value shows up here. Most landlords do not struggle to understand the existence of deductions. The struggle is category discipline. The tax return only works cleanly when expenses are tracked in a way that matches IRS reporting categories and can be defended with source records.
Interest, Taxes, Insurance, and Utilities
Mortgage interest on debt secured by rental property is generally deductible on Schedule E as a rental expense. Property taxes imposed on the rental property are generally deducted there as well, not confused with personal itemized deductions. Insurance premiums tied to the rental, including landlord policy coverage and liability insurance, also belong in the operating expense bucket.
Utilities follow the responsibility structure. If you pay for water, sewer, trash, electric, gas, or internet for the rental, those are rental expenses. If the property has personal-use days, those costs must be allocated between rental and personal use. That is one reason mixed-use properties require much tighter records than pure rentals.
Repairs, Maintenance, Cleaning, and Turn Costs
Repairs and maintenance are the day-to-day costs of keeping the property rentable. Typical examples include patching drywall, fixing a toilet leak, replacing a broken window pane, touch-up paint, lawn care, pest control, housekeeping between tenants, lock rekeying, and turnover cleaning.
The principle is preservation, not enhancement. If the work keeps the property in operating condition, it generally points toward a current deduction. If the work materially upgrades the property, extends useful life, or replaces a major component, you are in improvement territory instead.
Advertising, Commissions, Management Fees, and Professional Fees
Advertising costs to find tenants are generally deductible. So are leasing commissions, property management fees, tenant screening charges, bookkeeping fees, legal fees related to operations, and tax preparation fees allocable to the rental activity.
The catch is that not every professional fee is a current rental expense. Legal fees tied to acquisition, title defense, or structural financing matters often must be capitalized or otherwise treated differently. Loan origination and financing costs have their own treatment. Owners lose deductions here by dropping every professional invoice into one bucket without asking what the fee was for.
Travel, Local Transportation, and Home Office Questions
Travel deductions for rental activity require discipline because abuse in this area draws scrutiny. Local transportation for rental-related errands, contractor meetings, supply runs, inspections, and management tasks can be deductible if documented with mileage, date, destination, and business purpose.
Home office deductions sit outside the narrow core of Publication 527 and depend on broader business-use rules. The same goes for larger travel questions involving overnight stays. If the activity supports the rental and meets substantiation rules, the deduction may be available. If records are vague or the travel has mixed personal motives, the deduction position weakens fast.
Repairs vs. Improvements: The Decision That Changes Tax Timing
Based on analysis of recurring landlord reporting errors, this is the classification issue that causes the most current-year distortion. Deducting an improvement as a repair produces an immediate tax benefit, which is exactly why it is tempting. It also creates a weak file if examined and a broken depreciation schedule later.
The business outcome is clear. Correct classification protects current deductions you can actually keep. Incorrect classification inflates this year’s loss, understates basis additions, and creates recapture and gain problems when the property is sold.
What the IRS Treats as a Repair
A repair keeps the property in ordinarily efficient operating condition. It does not materially add value, prolong the property’s useful life in a meaningful way, or adapt it to a new use. Repair work is about fixing what is broken or worn in a limited way.
Examples include repairing a portion of a roof after a localized leak, replacing a broken window, fixing a section of damaged pipe, repairing a furnace control board, or repainting an apartment between tenants. Those costs generally preserve existing condition rather than create something new.
What the IRS Treats as an Improvement
An improvement is generally a betterment, restoration, or adaptation. A betterment materially improves quality, strength, capacity, or efficiency. A restoration replaces a major component or returns the property from a state of disrepair. An adaptation changes the property to a new or different use.
Examples include a full roof replacement, a kitchen remodel, replacing the entire HVAC system, adding a room, converting a garage into living space, or rebuilding after major damage. Those costs are capitalized and depreciated. A large invoice alone does not decide the issue, but full-system replacements and major remodels almost always point to improvement treatment.
Why Component-Level Records Matter
Invoices decide tax positions more often than owners expect. “Property renovation, $18,000” is weak support. “Replace damaged subfloor in bathroom and install matching tile in same footprint, $3,800” is much better. Scope detail determines whether a cost reads like repair work or a capital project.
Before-and-after photos, contractor proposals, itemized invoices, and notes on why the work was done all matter. Digital, time-stamped documentation strengthens a repair position because it shows the project at the component level. Poor records often turn a defensible repair into an improvement during examination simply because the file cannot prove the narrower facts.
Depreciation of Residential Rental Property
Depreciation is the tax mechanism that recovers the building’s cost over time. For most residential rental property, the building is depreciated over 27.5 years under MACRS. Land is never depreciated. That means basis must be allocated between depreciable building value and nondepreciable land value from the start.
This is one of the largest tax benefits in rental real estate because depreciation is a noncash deduction. A property can generate positive cash flow and still show a tax loss once depreciation is included. That feature is powerful, though passive loss rules can block the current benefit.
How to Establish Depreciable Basis
Depreciable basis starts with the purchase price allocated to the building, plus certain acquisition-related amounts that belong in basis, minus land value. A county assessor’s ratio can inform the allocation, though a supportable, fact-based allocation matters more than any shortcut. Closing costs must be separated carefully because some are basis items, some are loan costs, and some are current expenses.
Inherited property follows stepped-up basis rules. Converted property uses a more restrictive framework for depreciation and loss. Improvements added after acquisition create new depreciable basis separate from the original building schedule.
MACRS Recovery Period and Convention
Residential rental property generally uses a 27.5-year recovery period and the mid-month convention. The placed-in-service date matters more than the closing date because depreciation begins when the property is ready and available for rent. If the property is acquired in June but is not rentable until August after work is completed, August is the month that controls.
The mid-month convention means depreciation for real property begins as if placed in service in the middle of the month. That rule slightly adjusts the first and final year amounts.
Form 4562 and Depreciation Schedules
Depreciation is commonly reported through Form 4562, and the resulting expense flows into the rental reporting structure. Even when software handles the annual math, you still need a real depreciation schedule showing acquisition date, placed-in-service date, basis, life, method, convention, and accumulated depreciation.
That schedule is not optional in practice. Without it, future dispositions, partial asset write-offs, casualty adjustments, and CPA transitions become messy fast. A rental with multiple years of untracked improvements is one of the most expensive cleanup projects in landlord tax reporting.
Depreciation on Improvements and Separate Assets
Not every asset attached to a rental has the same life as the building. Appliances, carpeting, flooring, fences, and certain land improvements may be depreciated separately with different recovery periods. A new roof added years after purchase becomes its own capital asset. So does a new HVAC system.
That is why a single-line annual depreciation number is not enough. A defensible schedule identifies separate assets by type and placed-in-service date. The 27.5-year building rule is only the beginning.
Placed in Service, Converted Property, and First-Year Rules
Timing in the first year drives more than depreciation. The placed-in-service date also affects which operating expenses count as current rental deductions and which costs are treated as pre-rental or capital expenditures.
This is especially important for accidental landlords, former homeowners, and owners rehabilitating a property before the first tenant.
When Rental Activity Actually Begins
A property is placed in service when it is ready and available for rent. It does not require a tenant to have moved in yet. If the property is listed, marketable, and available for occupancy, rental activity has begun for depreciation and expense purposes even if it sits vacant for a period.
That rule helps owners in normal leasing gaps. A vacant property held out for rent is still a rental property. Vacancy does not turn it into personal-use property by itself. But if the property is not ready, not marketable, or still under major renovation, it is not yet placed in service.
Basis Rules for Property Converted From Personal to Rental Use
Converted property uses the lower of adjusted basis or fair market value at the date of conversion for depreciation and loss calculations. This rule matters because former residences often decline in value relative to original cost, especially after market shifts or deferred maintenance.
The practical result is that an owner converting a home to a rental cannot always depreciate the old purchase price adjusted upward indefinitely. The conversion-date fair market value can cap the depreciable basis for loss purposes. That makes documentation at the conversion date worth serious attention, including a market analysis, appraisal support, or other valuation evidence.
Start-Up, Pre-Rental, and Carrying Costs
Costs incurred before the property is placed in service are not automatically current rental deductions. Initial renovation work, acquisition-related costs, and carrying charges during a pre-rental rehab period often must be capitalized or otherwise treated outside current Schedule E operating expenses.
This is where many first-year returns go wrong. Owners count every cost incurred after closing as a rental deduction, even though the property was not yet ready for rent. The service date sets the line. Before that line, many costs build basis instead of reducing current taxable income.
Reporting Rental Income, Expenses, and Losses
Publication 527 becomes useful when it connects to the actual filing workflow. Good tax reporting starts with property-level records, then moves into income and expense classification, depreciation schedules, passive and at-risk testing, and finally return forms.
If records are weak, the forms become guesswork. If records are clean, the filing process is mechanical.
Schedule E: Where Most Individual Owners Report Rental Activity
Most individual landlords report rental activity on Schedule E, Part I. That is where rents received, expense categories, depreciation, and net income or loss are shown. Each property is usually listed separately, which supports property-level tracking and later disposition analysis.
This is why separate books by property matter. A single bank account and one annual spreadsheet for five units is not enough if you need to test mixed-use days, track separate improvements, or release suspended losses tied to a specific activity.
Form 8582: Passive Activity Loss Limitations
Rental losses often do not disappear, but they do get trapped. Form 8582 applies the passive activity loss rules and tracks suspended losses when current deductions exceed what is allowed. The IRS specifically connects Publication 527 with Form 8582, which is exactly where many high-income W-2 landlords end up.
This is the moment many owners discover that the tax loss from depreciation does not offset salary. The rental activity generated the loss correctly. The passive rules then limit when you can use it.
Form 6198 and At-Risk Limitations
At-risk rules can limit deductions before passive activity rules are applied. If you are not economically at risk for amounts invested or borrowed, losses can be limited even if the rental otherwise generated them. Form 6198 handles that analysis.
Order matters here. At-risk limitations are applied first. Passive limitations follow. If a loss survives the at-risk test, it still may be suspended under passive rules.
Passive Activity Rules: Why Rental Losses Get Trapped
For most investors, this is the real issue behind the search for publication 527 residential rental property rules. The property shows a loss after depreciation. Cash flow may even be positive. Yet the tax return gives no current benefit. That is not a software error. It is the design of IRC Section 469.
The Default Rule for Rental Activities
Rental activities are generally passive under IRC Section 469, even if you actively manage the property. That is the default rule. Passive losses generally offset only passive income, not wages, portfolio income, or most business income from nonpassive activities.
This is where owners confuse effort with tax classification. Managing tenants, approving repairs, and handling lease renewals does not automatically make the activity nonpassive. For rental real estate, the baseline rule is passive unless a specific exception applies.
The $25,000 Special Allowance for Active Participation
There is a limited exception for some rental real estate owners who actively participate. Active participation is a lower standard than material participation. If you make management decisions in a meaningful way, such as approving new tenants, setting rental terms, and authorizing repairs, you may qualify for a special allowance of up to $25,000 in rental real estate losses against nonpassive income.
But the allowance phases out as modified adjusted gross income rises. For many W-2 earners, the phaseout eliminates the benefit entirely. This is why a physician, executive, or tech employee with a solid salary often sees no current tax benefit from rental losses despite being hands-on with the property.
Suspended Passive Losses and When You Can Use Them
Suspended passive losses carry forward. They are not lost. They remain attached to the activity and can offset future passive income or be released when there is a fully taxable disposition of the entire interest in the activity.
That carryforward feature matters for hold-versus-sell planning. A property with years of suspended losses may look mediocre based on current cash flow alone, but a taxable sale can unlock those losses. The release event has planning value, especially when paired with gain recognition or portfolio repositioning.
Why High-Income W-2 Owners Often See No Current Tax Benefit
This is the common frustration: the property generates deductible expenses, interest, taxes, and depreciation, yet current deduction against W-2 wages is blocked. The reason is not that the expenses failed. The reason is that passive classification overrides the current use of the loss.
If your modified AGI is too high for the special allowance and you do not qualify as a real estate professional with material participation, the losses are suspended. That is the rule. Understanding it early prevents bad strategy, like buying more rentals solely for a current-year wage offset that will not happen.
Real Estate Professional Status: When Rental Losses Can Become Current Deductions
For owners with substantial trapped passive losses, Real Estate Professional Status is the high-impact exception. This is not a branding concept. It is a technical classification under IRC Section 469(c)(7), and the consequences are significant. If the tests are met and material participation is established, rental losses can become nonpassive and therefore currently deductible against nonpassive income.
That is why the standard is audited aggressively. The tax benefit is large, and the documentation burden should be treated accordingly.
The Two Statutory Tests
Two statutory tests define Real Estate Professional Status. More than half of your personal services performed in trades or businesses during the year must be performed in real property trades or businesses in which you materially participate. And you must perform more than 750 hours of services during the year in those real property trades or businesses.
Employee hours count only if the ownership requirement is met. This catches salaried real estate workers who assume job hours automatically qualify. The statute does not work that way. Ownership and participation structure matter.
Material Participation Still Applies
Real Estate Professional Status alone is not enough. Each rental activity must also satisfy material participation unless you make the election to treat all interests in rental real estate as a single activity. This is where many otherwise strong files fail. The status test is met, but no single rental activity shows enough participation on its own.
Material participation is not the same as active participation. Active participation supports the smaller special allowance. Material participation is a higher standard used to determine whether the activity is nonpassive once Real Estate Professional Status is in play.
Grouping Election and Operational Consequences
The grouping election to treat all rental real estate interests as one activity is often what makes material participation practical. Instead of proving material participation separately for each property, you measure participation across the grouped activity.
But grouping has consequences. It affects how future dispositions are treated because selling one property in a grouped activity does not automatically release suspended losses for that single property in the same way as a separate activity sale would. The election helps with annual loss usage, but it changes downstream flexibility. That decision should be modeled, not guessed.
Documentation Standards That Survive Examination
Time logs need to show date, hours, activity, and property connection. Calendars, emails, contractor communications, leasing records, invoices reviewed, travel logs, and management software records should support the same story. A year-end estimate written from memory is weak. A contemporaneous activity file is much stronger.
Based on observed examination patterns, the recommendation is simple: maintain weekly or monthly logs, preserve electronic proof, and separate investor-level review from real operational work. Time spent reviewing financial performance as an investor does not carry the same weight as real management and operational services.
Vacation Homes and Personal Use of Dwelling Units
Publication 527 gives mixed-use property a separate framework because personal-use days can completely change the deduction result. This is the section many owners of beach houses, mountain cabins, second homes, and occasional short-term rentals misunderstand.
The three-tier system is the cleanest way to understand it. Tax-free short rental. Mixed-use residence with allocation and deduction limits. Pure rental with full deduction treatment.
The 14-Day Rule and the 10% Personal-Use Test
A dwelling unit is treated as used as a home if personal use exceeds the greater of 14 days or 10 percent of the days it is rented at a fair rental price. That threshold determines whether the vacation-home limitation applies.
This produces three practical tiers. Tier 1, rent fewer than 15 days and the rental is ignored for income reporting. Tier 2, rent more than 14 days and have enough personal use to cross the threshold, and the dwelling is used as a home, which triggers allocation and deduction limits. Tier 3, rent more than 14 days with personal use at or below the threshold, or none at all, and the property is generally treated as a rental activity subject to the normal rental rules.
When Rental Income Is Tax-Free
If a dwelling unit is rented fewer than 15 days during the year, rental income is not reported. That is one of the narrowest and most favorable rules in residential rental taxation.
Use the beach-house example directly. If the property is rented 12 days at $500 per night, gross rent is $6,000. None of that $6,000 is reported as rental income. No rental expense deduction is allowed. Mortgage interest and property taxes remain where personal residence rules place them, but there is no Schedule E rental reporting at all.
This is powerful, but narrow. The moment the property reaches day 15, the rule is gone and the framework changes.
Allocating Expenses Between Rental and Personal Use
In Tier 2 mixed-use cases, expenses must be allocated between rental days and personal-use days. The basic logic is straightforward: shared expenses are divided by actual use. Direct rental-only expenses stay fully rental. Direct personal expenses stay personal.
Take the required example. The property is rented 60 days and used personally 20 days. Total use days are 80. Shared expenses allocated by use produce a 60/80 or 75 percent rental allocation. If interest, taxes, insurance, utilities, maintenance, and depreciation together total $24,000 for the year, $18,000 is allocable to rental use and $6,000 to personal use. That does not end the analysis, though. If the dwelling is used as a home, rental deductions are limited to gross rental income under the ordering rules. A paper loss from the rental side cannot always be created the same way it can with a pure rental.
What Counts as a Personal-Use Day
This is where owners make expensive mistakes. Personal-use days include your own stays, use by family members, use by anyone paying less than fair rental price, and reciprocal-use arrangements. Family use generally counts as personal use even if a family member pays fair rent, unless the unit is that family member’s principal residence and fair rent is actually paid.
The required rules here are not optional details. Your own stays count. Family member stays count, even if rent is paid, unless the principal-residence exception applies. Days spent primarily on repairs and maintenance do not count as personal use if maintenance is the primary purpose of the stay. That means a day spent replacing damaged flooring, supervising contractors, and repairing plumbing is not a personal-use day just because you slept there that night. But a long weekend that includes one hour of checking smoke detectors is still personal use.
Deduction Ordering Rules for a Dwelling Used as a Home
If the dwelling is used as a home under the vacation-home rules, rental deductions are limited to gross rental income. The ordering rules generally apply expenses in tiers. Interest and taxes usually come first, then operating expenses, then depreciation. Once rental income is reduced to zero, excess deductions are limited rather than used to create a current rental loss.
That is the real tax cost of Tier 2 status. You still report rental income, but you do not receive the same full-loss treatment available to a pure rental. Owners often lose this benefit simply because they underestimate or misclassify personal-use days.
Special Situations Publication 527 Covers
The edge cases are where expensive errors hide. Publication 527 addresses several situations that do not affect every landlord but matter a lot when they arise.
Part-Year Rental Use and Temporary Vacancies
If a property is vacant between tenants but held out for rent, the vacancy period is generally part of the rental activity. Ordinary carrying expenses during that period remain tied to the rental. That is very different from pulling the property off the market and using it personally, which changes the character of the days.
In other words, vacancy alone does not hurt deduction status. Personal use does.
Renting to Relatives
Renting to relatives requires close attention to fair rental price. If the unit is rented below fair rent, the use is generally treated as personal rather than rental. That can collapse deductions and convert what looked like a business arrangement into personal-use occupancy for tax purposes.
Documentation matters here. Market listings, comparable rents, written leases, and actual payment records help prove fair rental treatment. Informal family arrangements are where the IRS often sees weak support.
Casualty, Theft, and Insurance Reimbursements
Publication 527 also intersects with casualty and theft issues for rental property. If a storm, fire, or other casualty damages the property, deductions and basis adjustments depend on insurance reimbursements and the amount of economic loss. Reimbursements reduce the deductible loss and also affect basis going forward.
This is not just an insurance issue. It is also a depreciation and basis issue after the event. Repairs after a casualty can include both deductible work and capital restoration work, which means the records need the same component-level discipline discussed earlier.
Property Held Through an LLC
A single-member LLC is generally disregarded for federal income tax purposes unless an election changes classification. That means the rental is usually still reported on Schedule E in the same way as if owned directly. The LLC may matter for liability protection under state law, but it does not automatically create a new federal reporting method.
Multi-member LLCs are different because partnership tax rules usually apply unless another election has been made. But the presence of an LLC by itself does not move a standard residential rental from Schedule E to Schedule C.
Tax Law Changes for 2026 and 2027: What Changes and What Stays the Same
Owners looking ahead to 2026 and 2027 need to separate the underlying rental framework from broader individual tax overlays. Publication 527’s core rules do not reset because the Tax Cuts and Jobs Act sunset approaches. Income classification, repair-versus-improvement treatment, depreciation methodology, and vacation-home day counting stay grounded in the same federal rental tax structure.
What changes is the broader individual tax environment around those rules.
Rules That Stay the Same
Publication 527’s framework for rental income, deductible rental expenses, depreciation, and mixed personal-use allocation remains intact. Schedule E reporting remains the baseline. Depreciation on residential rental buildings remains tied to MACRS rules. The passive activity regime under Section 469 remains the key limiter on current loss usage.
That distinction matters because owners often expect a sweeping rule reset when broader tax law changes are discussed publicly. For residential rental reporting, the operating manual does not get rewritten just because individual rates or deduction caps change elsewhere.
TCJA Sunset Areas That Affect Rental Owners Indirectly
The most important sunset effects for many owners are indirect. Individual tax rate changes affect the value of deductions. The Section 199A qualified business income deduction may change depending on legislative action. Personal deduction items and bracket structure affect after-tax cash flow even when the rental rules themselves stay the same.
If your rental activity qualifies for QBI, a sunset-related change there alters after-tax economics. If marginal rates rise, depreciation and deductible operating costs become more valuable. If personal tax items become less favorable, trapped passive losses feel even more expensive because your nonpassive income remains more exposed.
Planning Decisions to Evaluate Before Sunset
The recommendation is to model the pieces that actually move tax outcomes. Review repair-versus-improvement timing for projects already underway. Reassess grouping elections if Real Estate Professional Status is part of the strategy. Model when suspended passive losses would be released under possible sale scenarios. Revisit entity structure only if there is a real tax or operational reason, not because an LLC sounds more sophisticated. And if REP eligibility is being pursued, lock down documentation before the year closes.
Tax strategy works best when tied to decisions already happening operationally. Deferring documentation until filing season destroys value.
Publication 527, QBI, and Other Connected Tax Rules
Sophisticated rental owners do not stop at Publication 527 because the return does not stop there. Rental taxation intersects with Section 199A, passive activity limitations, itemized deduction rules, basis rules, and entity classification.
Publication 527 tells you how to report the rental. It does not decide every downstream tax benefit attached to that reporting.
When Rental Activity May Qualify for the Section 199A QBI Deduction
Some rental real estate activities qualify for the Section 199A qualified business income deduction. The analysis depends on whether the rental activity rises to the level of a trade or business under Section 162 or qualifies under the rental real estate safe-harbor framework described elsewhere in IRS guidance.
Publication 527 does not grant QBI by itself. But the records and reporting categories it supports are the raw material for the QBI analysis. If the books are weak, the trade-or-business case is weak too. If the records show real rental operations, hours, services, and ordinary business expenses, the file is stronger.
SALT, Mortgage Interest, and Other Frequently Confused Limits
One of the most common points of confusion is mixing rental deductions with personal itemized deduction limits. State and local tax caps on Schedule A do not generally control rental property taxes deducted on Schedule E as a business expense. Mortgage interest on rental debt belongs in the rental activity, not in the owner-occupied home mortgage framework.
This distinction matters because owners regularly underclaim valid rental deductions by assuming personal deduction caps apply across the board. They do not. Schedule E and Schedule A operate under different rules.
Recordkeeping Systems That Support Defensible Deductions
Good tax strategy fails without operational records. Based on analysis of landlord filings that hold up best under review, the difference is rarely intelligence. It is system design. A workable system categorizes expenses by property, stores source documents at invoice level, tracks personal-use days, and preserves depreciation detail year after year.
That drives time-to-value too. Clean records reduce CPA cleanup time, reduce missed deductions, and make planning possible before year-end instead of after the fact.
The Five Records Every Rental Owner Needs
Every rental owner needs five record sets: lease files, rent ledgers, bank statements, invoices, and depreciation schedules. Lease files prove rental terms, deposits, reimbursements, and fair-rent status. Rent ledgers prove what was billed, received, retained, or forgiven. Bank statements tie the ledger to actual cash receipts and disbursements. Invoices support expense classification and property connection. Depreciation schedules preserve basis and accumulated depreciation.
If travel or local transportation is claimed, mileage logs belong in the file too. If contractor payments require information reporting, W-9 collection and 1099 tracking should be part of the system. The underlying point is consistency. Each record should connect to a specific IRS reporting need.
How to Track Mixed-Use and Vacation Properties
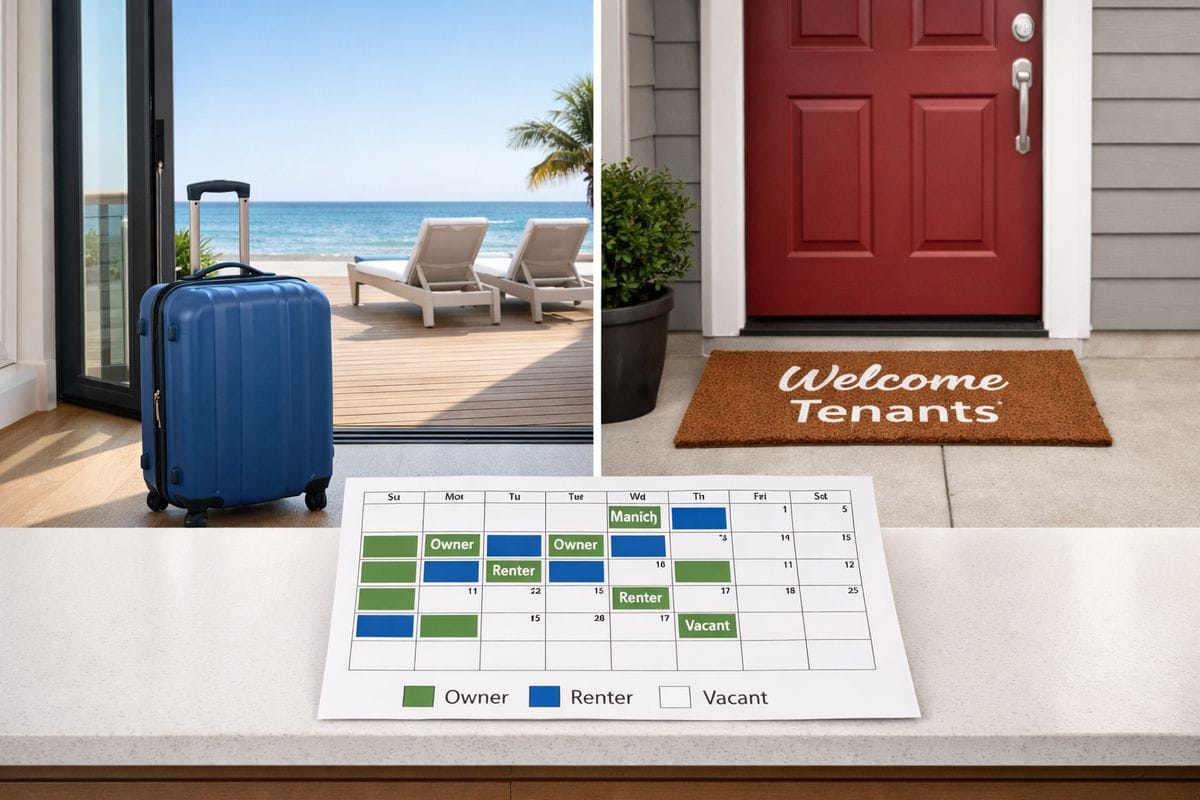
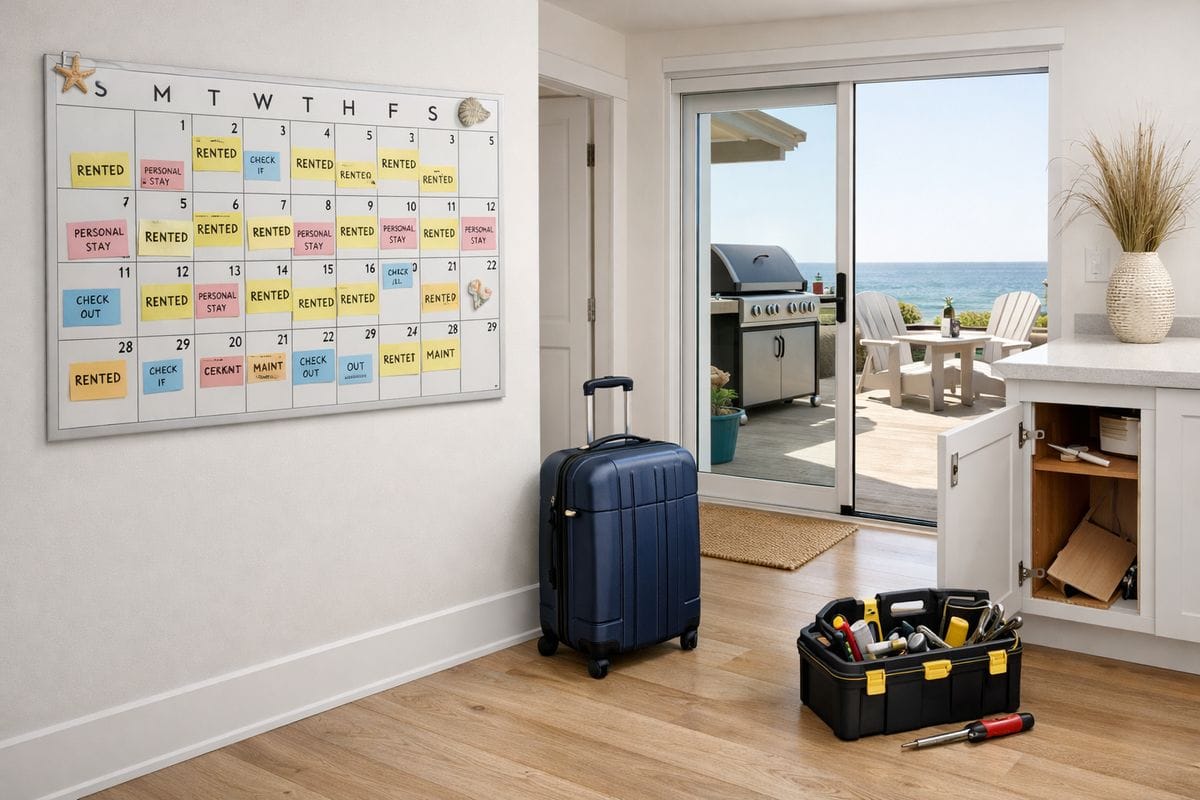
Mixed-use properties need an additional layer: day-count calendars, fair-rent support, booking platform records, and coded personal-versus-rental expenses. A calendar showing each day’s use is often the single most important document in a vacation-home file.
This is especially true for family use. If a relative occupies the property, the file should show dates, rent charged, fair market support, and whether the property was that relative’s principal residence. Without that, personal-use classification becomes hard to challenge.
Year-End Review Process Before Filing
The review sequence should be disciplined. Confirm that all rental income is captured, including prepaid rent, retained deposits, and reimbursements. Review maintenance and contractor invoices to classify repairs versus improvements. Update the depreciation schedule for every placed-in-service asset. Test passive and at-risk limitations. Reconcile personal-use days and rental days for any mixed-use property.
This process should happen before tax forms are drafted, not after. Once numbers are dropped into return software, classification mistakes become harder to see.
The Most Common Publication 527 Mistakes That Reduce ROI or Raise Audit Risk
Certain errors appear repeatedly in landlord tax reporting because they produce an immediate benefit or seem harmless. They are neither.
Deducting Improvements as Repairs
This inflates current deductions and lowers taxable income now, which looks attractive. It also creates one of the easiest IRS adjustments on examination if invoices show remodeling, full-system replacement, or major restoration. The result is denied current deductions, corrected basis, and a more expensive cleanup later.
Forgetting to Depreciate the Building
Some owners skip depreciation because they do not want future recapture or because the property is cash-flow positive and the return already looks good. That is a mistake. Allowed or allowable depreciation rules mean recapture issues remain even if you failed to claim the deduction. You lose current tax value and still inherit future complications.
Miscounting Personal-Use Days
This changes the entire framework for a vacation or mixed-use property. One wrong assumption about family use or owner weekends can shift a property from pure rental treatment into dwelling-used-as-a-home limitations. That means deductions are capped and losses disappear.
Assuming Material Participation Automatically Unlocks Losses
For rental real estate, material participation by itself does not override passive classification. Without Real Estate Professional Status and material participation, or without another applicable exception, rental losses remain passive. This misconception causes repeated overstatement of wage-offset deductions.
Reporting Through the Wrong Form or Entity Lens
Owners regularly assume that an LLC means Schedule C, or that a short-term rental automatically follows the same rules as a traditional annual lease. Federal tax treatment depends on classification rules, activity structure, and services provided, not on branding alone. Form choice should follow the tax rules, not the entity name.
Frequently Asked Questions About Publication 527 and Residential Rental Property Rules
Is Publication 527 the legal authority or just IRS guidance?
Publication 527 is IRS guidance, not the controlling law. The legal authority comes from the Internal Revenue Code, Treasury regulations, form instructions, rulings, and court decisions. Publication 527 is still valuable because it shows how the IRS expects common residential rental issues to be reported.
Can a rental property show a tax loss even when it produces positive cash flow?
Yes. Depreciation is a noncash deduction, so a property can collect more cash than it spends and still show a taxable loss. The separate question is whether that loss is currently usable. Passive activity rules often suspend it.
Does an LLC change how residential rental income is reported?
A single-member LLC usually does not change federal income tax reporting because it is generally disregarded. The rental still typically flows through Schedule E. A multi-member LLC usually introduces partnership reporting, but the rental rules themselves remain grounded in the same tax concepts.
Can rental losses offset W-2 income?
Usually no. Rental activities are generally passive, and passive losses generally offset only passive income. The main exceptions are the up to $25,000 special allowance for qualifying active participants and Real Estate Professional Status combined with material participation.
What counts as personal use for a vacation home?
Personal use includes your own stays, family member stays, below-market rentals, and reciprocal-use arrangements. Family use generally counts even if fair rent is paid, unless the family member uses the property as a principal residence and actually pays fair rent. Days spent primarily on repairs and maintenance do not count as personal-use days.
What is the recommendation before filing or changing strategy?
Use Publication 527 as the operating manual, then test every major output through the companion forms. Run Schedule E from property-level records, validate depreciation on Form 4562, test passive limits on Form 8582, review at-risk exposure on Form 6198 when relevant, and model 2026 and 2027 tax changes before year-end. The recommendation is decisive: document every classification decision at the invoice level and every mixed-use decision at the day-count level, because that is where rental tax outcomes are won or lost.