
Commercial real estate tax deductions change the math faster than almost any rent increase or expense cut. Once you move from houses into apartment buildings, retail, office, industrial, or NNN assets, tax treatment starts affecting after-tax cash flow, DSCR, and reinvestment capacity in a much bigger way.
Commercial real estate tax deductions are the federal, state, and local write-offs, depreciation rules, and incentive programs that reduce taxable income from owning and operating income property. The headline rule is simple: residential rental buildings depreciate over 27.5 years, while nonresidential commercial buildings depreciate over 39 years. But that headline misleads a lot of investors, because the best commercial tax strategy is not the 39-year shell. It is the shorter-life components, current deductions, and timing rules layered around it.
Here’s what matters most in this guide:
- The three drivers of commercial tax savings
- How 39-year depreciation actually works in practice
- Why cost segregation produces the biggest early-year impact
- Which operating deductions owners miss every year
- How 1031, 179D, and local relief programs improve ROI
- Where passive loss rules block paper savings
- What to review before closing, during year one, and before filing
Why Commercial Real Estate Tax Deductions Change Deal Economics
Commercial tax planning is not a back-office detail. It changes acquisition pricing, debt sizing, and hold strategy.
If taxable income drops earlier in the hold period, more cash stays inside the deal. That improves after-tax yield and gives more capital for tenant improvements, leasing costs, principal reduction, or the next acquisition. Based on analysis of common CRE tax outcomes, the biggest wins come from accelerating deductions into the current year, not from collecting the same deductions slowly over decades.
This is why residential investors fixate on the wrong comparison. Seeing 39-year commercial depreciation next to 27.5-year residential depreciation makes commercial property look tax-disadvantaged. On paper, that seems true. In actual deal performance, it often fails, because commercial assets usually offer more opportunities to carve out shorter-life components, deduct common area and leasing costs, and stack federal and local incentives.

The Three Drivers of Tax Savings in Commercial Real Estate
Three drivers produce most of the real money: depreciation acceleration, recurring operating deductions, and gain deferral or incentive programs. Everything else is secondary.
Driver 1: Accelerate deductions into the current year
Current-year deductions have the highest cash-flow value. A deduction taken now improves current ROI. The same deduction spread over 15, 27.5, or 39 years has less present value and less impact on your ability to redeploy capital.
That is why cost segregation matters so much. It identifies building components that belong in 5-year, 7-year, or 15-year categories instead of the 39-year building shell. If bonus depreciation applies, those shorter-life assets can create a much larger first-year deduction. Cost segregation accelerates depreciation, which is exactly why it sits at the center of serious CRE tax planning.
Driver 2: Capture every ordinary property expense
The next layer is less glamorous but no less valuable. Mortgage interest, insurance, property taxes, repairs, CAM expenses, management fees, accounting, software, environmental due diligence, and ordinary travel tied to the property all reduce taxable income when classified correctly.
The field data shows that owners do not usually miss deductions because the rules are hidden. Owners miss them because books are set up poorly, invoices are vague, or expenses get capitalized when they should be deducted.
Driver 3: Defer gains and stack incentives
The third driver is tax drag reduction over the full hold period. 1031 exchanges defer gains and depreciation recapture. Energy deductions under Section 179D reduce taxable income tied to qualifying improvements. State and local incentives, abatements, and assessment relief lower ongoing ownership cost.
That combination matters. Tax savings in commercial property come from both the federal return and local tax structure.
Commercial vs. Residential Depreciation: The Rule Change That Reshapes Returns
The federal rule is straightforward. Residential rental property uses a 27.5-year recovery period. Nonresidential real property uses 39 years. But the useful planning question is not “What is the building life?” It is “What part of this purchase price is really a building shell?”
27.5 Years vs. 39 Years
Apartment buildings generally fall under residential rental property if 80 percent or more of gross rental income comes from dwelling units. Office, retail, warehouse, industrial, medical office, and most NNN lease properties are generally nonresidential real property and use 39-year straight-line depreciation.
Mixed-use assets need careful allocation. A building with apartments over ground-floor retail can include both residential and nonresidential elements. That classification changes depreciation schedules and can materially alter projected tax benefits.
Why Commercial Still Produces Stronger Early-Year Deductions
Here’s where the 39-year rule stops telling the full story. Parking lots, landscaping, site lighting, specialty wiring, cabinetry, decorative finishes, and certain tenant-specific buildouts are not the same as the structural shell. When those items are identified correctly, deductions move into shorter recovery periods.
A simple example makes the point. Assume a $3 million property, with $600,000 allocated to land and $2.4 million to depreciable basis. If the full $2.4 million stays in 39-year property, annual depreciation is about $61,538. If a cost segregation study reclassifies $480,000 into shorter-life assets, the first-year deduction increases dramatically, especially if bonus depreciation applies to part of that reclassified amount. The commercial deal that looked worse on a straight-line basis now produces stronger early tax shelter and better cash retention.
Cost Segregation: The Highest-Impact Deduction Strategy for Commercial Owners
Cost segregation is the highest-impact deduction strategy because it changes timing, and timing drives cash flow.
A study breaks the building into components and assigns the right tax life to each one. That means more basis gets written off over 5, 7, or 15 years instead of 39. Based on field data from commercial tax planning, this is consistently the largest first-year tax savings opportunity for acquired or improved income property.
What a Cost Segregation Study Reclassifies
Plain-English examples help. Five-year property often includes carpeting, removable partitions, tenant-specific cabinetry, specialty electrical tied to equipment, and certain interior finishes. Seven-year property can include some furniture, fixtures, and equipment. Fifteen-year property often includes parking lots, sidewalks, landscaping, fencing, drainage, and site lighting.
That distinction matters because land never depreciates, the shell depreciates slowly, and site improvements depreciate much faster. A quality study separates those categories with engineering support, not guesswork.
When a Cost Segregation Study Produces the Best ROI
The economics are strongest when basis is high enough and shorter-life components are meaningful. That usually means newly acquired office, retail, medical office, industrial, self-storage, renovated multifamily, and NNN assets with major tenant improvements.
Larger acquisitions produce the clearest return, but smaller commercial properties can still justify the analysis if improvement value is significant. Even lower-cost digital tools have entered the market, though pass-through structures and complex ownership arrangements still benefit from specialized review.
Dollar Example: Straight-Line Depreciation vs. Cost Seg
Use the same $3 million acquisition. Land is $600,000. Depreciable basis is $2.4 million.
Without cost seg, annual depreciation on the commercial building is about $61,538.
Now assume the study reclassifies:
- $300,000 to 15-year land improvements
- $120,000 to 5-year personal property
- $60,000 to 7-year assets
- $1,920,000 remains 39-year building
If no bonus depreciation applied, first-year deductions still rise because shorter-life property depreciates faster. If bonus depreciation applied to the qualifying short-life assets, a substantial portion of that $480,000 would be deductible upfront. At a combined 35 percent tax rate, every additional $100,000 of current deduction saves $35,000 in current tax. That is real cash, not a paper benefit.
Bonus Depreciation and Timing Rules That Matter Right Now
Bonus depreciation multiplies the value of cost segregation, but only for qualifying shorter-life assets and only if timing rules are met.
How Bonus Depreciation Applies to Shorter-Life Assets
Bonus depreciation does not apply to the 39-year structural shell. It applies to qualifying 5-year, 7-year, and 15-year property identified through cost segregation. That is why cost seg and bonus depreciation are usually discussed together. One identifies the assets. The other accelerates the write-off.
Phase-Downs, Cutoffs, and Why Placed-in-Service Dates Control the Outcome
Placed-in-service dates control the result. Not contract dates. Not intent. Not underwriting assumptions.
Miss a date and the current deduction shrinks. That delays time-to-value and leaves cash trapped in future years. This is especially important for acquisitions with renovations, tenant buildouts, or phased construction, where different components can enter service at different times.
New Qualified Production Property Rules to Watch
A newer rule deserves close attention for industrial and manufacturing deals. IRS interim guidance addresses 100% bonus depreciation for Qualified Production Property under IRC Section 168(n) for qualifying industrial or manufacturing property placed in service after July 4, 2025, or with construction begun after January 19, 2025.
This is not a broad rule for every warehouse or commercial building. Eligibility review has to cover property use, construction timing, pass-through structure, demolition issues, and component election strategy. Specialized review is the recommendation, because a wrong assumption here directly reduces current deductions.
The Core Operating Deductions You Should Capture Every Year
Recurring deductions matter because they save money every year, even if no cost seg study is done.
Mortgage Interest and Other Financing Costs
Mortgage interest is generally deductible as an ordinary business expense. Loan origination fees, lender legal fees, and similar financing costs are usually capitalized and amortized over the life of the loan rather than deducted immediately.
Refinance costs need separate tracking. Some write-offs accelerate when debt is retired, while new financing costs start a new amortization period. If the books lump all financing costs together, deductions get distorted.
Property Taxes, Insurance, Utilities, and Common Area Expenses
Property taxes, hazard insurance, utilities, security, janitorial, snow removal, and common area maintenance are standard annual deductions. In office, retail, and industrial properties, reimbursement structures matter because lease language determines what is billed to tenants, what stays landlord-paid, and how expenses hit taxable income.
Local property taxes deserve active management because assessment growth directly raises operating cost. Since 2020, property values have risen almost 27% faster than inflation, which is one reason tax pressure has intensified across many markets.
Repairs vs. Improvements
This is one of the most expensive classification errors in commercial real estate. Repairs are generally deducted now. Improvements are capitalized and depreciated.
Patch a portion of the roof, deduct it. Replace the full roof system, capitalize it. Repair HVAC components, usually deduct. Install a brand-new unit, capitalize. The difference is not semantics. It changes current tax liability and after-tax cash flow immediately.
Tenant improvement allowances create another commercial-specific issue. Certain TI costs are depreciated over 15 years if they qualify, while smaller items may be expensed under safe-harbor rules. Lease commissions paid to brokers are generally capitalized and amortized over the lease term, not deducted in one shot.
Professional Fees, Management, Travel, and Administrative Costs
Accounting, tax prep, legal work tied to operations, bookkeeping, property management, software subscriptions, bank charges, and ordinary business travel connected to due diligence or property operations are generally deductible. Documentation matters. Business purpose should be clear from invoices, memos, and logs.
Environmental work is another area residential investors often overlook. Phase I and Phase II assessments are often deductible as ordinary due diligence or environmental costs, and qualifying remediation expenses may be fully expensed under Section 198 instead of capitalized into the building.
Property Tax Deductions, Assessments, and Local Relief Programs
Federal deductions get most of the attention, but local property tax strategy often decides whether a deal keeps its margin.
Why Local Assessment Rules Matter More in Commercial Real Estate
Commercial assessments vary by state, county, classification, and appeal process. Assessment methodology can raise or lower effective holding cost in ways that do not show up in a generic pro forma.
California is a good example because county property value tables separate land, improvements, and personal property categories. That kind of data matters when reviewing assessments, exemptions, and taxable value assumptions.
Appealing Assessments and Finding Exemptions or Abatements
Appealing an assessed value is not optional busywork when taxes jump. It is asset management.
If square footage, occupancy assumptions, market rent estimates, or classification codes are wrong, the assessment should be challenged. Local abatements, redevelopment incentives, and exemption categories can further reduce tax burden. This is jurisdiction-specific work. County and state rules decide the result, not just the federal return.
State-Specific Lease and Occupancy Taxes to Watch
Some states add lease-related tax friction that changes underwriting. Florida offered the clearest example. Florida eliminated its Business Rent Tax effective October 1, 2025, ending a tax that had applied to commercial leases and certain landlord-paid items treated as rent.
That matters because taxes on rent affect tenant demand, occupancy cost, and lease competitiveness. If underwriting ignored state-specific lease taxes before, it overstated net economics.
Special Tax Breaks Beyond Standard Deductions
Standard deductions reduce income. Strategic tax breaks improve portfolio compounding.
Qualified Business Income Deduction for Pass-Through Owners
The QBI deduction under IRC Section 199A allows up to a 20 percent deduction on qualified business income for eligible pass-through owners. Eligibility turns on taxable income, entity structure, and whether the rental activity rises to a trade or business. The business outcome is straightforward: entity structure changes after-tax yield.
1031 Exchanges for Capital Gains Deferral
Section 1031 allows gain deferral when exchanging into other qualifying investment real estate. That includes capital gain and depreciation recapture deferral, which preserves equity for larger acquisitions.
For investors moving from smaller residential assets into apartment, mixed-use, or NNN property, this is one of the cleanest scaling tools in the tax code.
Opportunity Zone and Similar Deferral Programs
Opportunity-related incentives are location-driven. Used correctly, they defer or reduce tax drag while improving project-level ROI. Used casually, they become marketing bait attached to weak deals. Tax benefit never rescues poor basis or poor operations.
Energy Incentives and Section 179D
Section 179D is the most overlooked deduction in commercial real estate. Many eligible owners never claim it because the preparer never checks the engineering thresholds.
For qualifying energy-efficient commercial building improvements, Section 179D can provide deductions of up to $5.65 per square foot under current rules when lighting, HVAC, hot water, or building envelope improvements hit required performance standards. On a 20,000 square foot building, that is a $113,000 deduction. The code section is IRC 179D. The claim is a current deduction, not 39-year building depreciation, but it requires technical certification and project-level review.
Tax Credit Programs for Specialized Projects
LIHTC, historic tax credits, and NMTC matter for redevelopment, adaptive reuse, affordable housing-linked projects, and certain mixed-use transactions. These programs are narrower than basic deductions, but when a project fits, the economics shift materially.
Passive Loss Rules, Real Estate Professional Status, and Using Losses Correctly
A projected deduction is not the same as a current tax savings. Passive loss rules decide whether the loss is usable now.
How Passive Activity Rules Limit Current-Year Benefits
Rental real estate is generally treated as passive. That means depreciation and other losses usually offset passive income, not wages, business income, or portfolio income. A pro forma showing a $150,000 tax loss does not automatically create $150,000 of current tax benefit.
When Real Estate Professional Status Changes the Outcome
Real estate professional status changes the result if qualification tests are met and material participation is established. The high-level thresholds are strict: more than half of personal service time must be in real property trades or businesses with material participation, and more than 750 hours must be performed in those activities. A widely used example shows that a qualifying taxpayer with a $100,000 rental loss can generate up to $40,000 in tax savings where the loss would otherwise remain suspended.
Grouping Elections and Material Participation
Grouping elections and participation records matter more as the portfolio grows. If ownership spans multiple properties, property types, or entities, grouping can determine whether participation is measured efficiently or property by property. Good documentation, calendars, and time logs support the position.
Recordkeeping, Documentation, and Compliance: The Difference Between a Deduction and a Disallowed Claim
Documentation is part of the tax strategy. Without records, a deduction is just a theory.
The Records You Need for Each Major Deduction
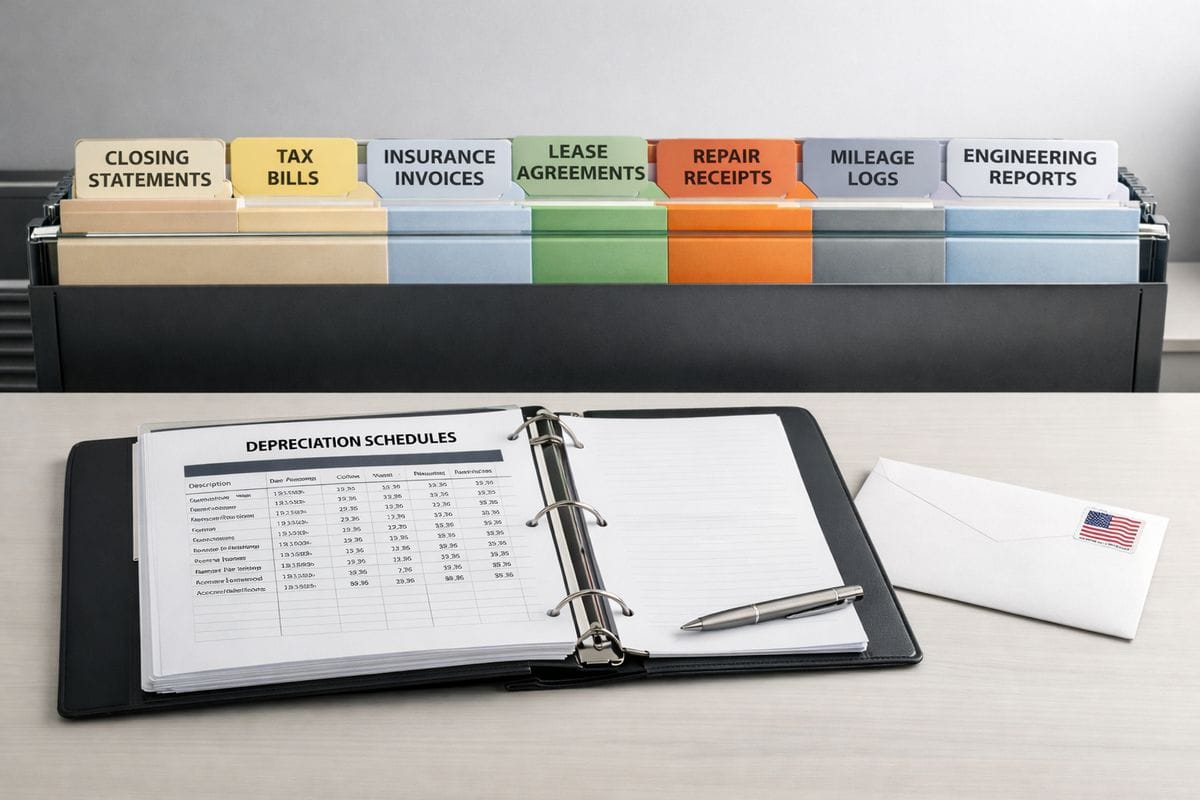
For commercial real estate, the core file should include closing statements, purchase price allocations, depreciation schedules, cost segregation reports, loan agreements, amortization schedules, tax bills, insurance invoices, lease agreements, CAM reconciliations, repair invoices, mileage logs, management agreements, broker commission statements, and engineering certifications for any 179D claim.
Filing Deadlines That Protect Tax Incentives
State and local incentives often require annual reporting. In Washington, some businesses claiming incentives must file an Annual Tax Performance Report by May 31, and missing the deadline can trigger repayment of 35 percent or 50 percent of the claimed incentive. That is not a paperwork nuisance. That is cash leaving the deal.
Working With the Right Specialists
A general tax preparer is not enough for every commercial property. Cost segregation engineers, property tax appeal consultants, state and local tax specialists, and advisors who understand pass-through entity structuring produce faster time-to-value and lower audit risk. That is especially true for cost seg, 179D, QPP review, environmental expense treatment, and multi-state portfolios.
A Practical Deduction Checklist for a First Commercial Acquisition
Residential investors moving into commercial property need a decision sequence, not generic tax tips.
Before Closing
Review entity structure first. Then review purchase price allocation between land, building, and identifiable site or personal property. Analyze lease language for CAM, tax reimbursements, TI obligations, and commission treatment. Search for local abatements and state incentives. Decide whether basis and asset mix justify a cost segregation study.
A commercial-specific checklist should include these deductions and treatments:
- Cost segregation, IRC 167 and 168, capitalize then depreciate by class life, example: $480,000 reclassified from a $2.4 million basis creates a much larger first-year deduction than straight-line 39-year treatment.
- Tenant improvements, IRC 168, capitalize and depreciate, often 15 years for qualifying improvements, example: $150,000 lobby and suite buildout creates faster recovery than 39-year shell treatment.
- Lease commissions, IRC 263 and 167, capitalize and amortize over lease term, example: $24,000 commission on a 6-year lease yields $4,000 annual amortization.
- CAM expenses, IRC 162, expense currently, example: $38,000 for landscaping, snow, cleaning, and security reduces current taxable income immediately.
- Environmental assessments and remediation, IRC 162 or 198 depending on facts, often current expense for due diligence and qualifying remediation, example: $18,000 Phase I/II work deducted in year incurred.
- Section 179D, IRC 179D, current deduction with certification, example: 20,000 square feet times $5.65 equals $113,000 deduction.
During Year One
Track placed-in-service dates closely. Separate repairs from improvements as invoices arrive. Tag financing costs, broker commissions, TI spend, and recurring operating expenses into the correct tax buckets from day one.
Review bonus depreciation eligibility before year-end, not during return prep. If industrial or production property is involved, review current QPP guidance while construction and service dates are still controllable.
Before Filing the Return
Reconcile operating statements to tax categories. Confirm depreciation schedules and any cost segregation adjustments. Test passive loss limitations. Confirm all state or local incentive filings, property tax appeals, and energy certification requirements.
This is also the right point to run one last deduction audit with a real estate tax advisor. Proactive review captures deductions. Retroactive cleanup usually costs more and saves less.
The Recommendation: Prioritize Deductions That Accelerate Cash Flow First
The recommendation is direct: confirm depreciation classification first, run a cost segregation analysis where basis supports it, capture every recurring operating deduction, and audit state and local relief programs every year.
That sequence produces the highest ROI because commercial real estate tax deductions are won through timing, classification, and compliance. The 39-year rule is not the problem. Poor planning is. If a commercial acquisition is underwritten without proactive tax review, cash gets left on the table before the first rent check clears.
Frequently Asked Questions
What are the biggest commercial real estate tax deductions?
The biggest deductions usually come from cost segregation, bonus depreciation on qualifying short-life assets, mortgage interest, property taxes, repairs, CAM expenses, management fees, and Section 179D energy deductions. For larger deals, depreciation timing usually delivers the largest early-year cash-flow impact.
Is commercial property always worse than residential because of 39-year depreciation?
No. The 39-year schedule applies to the building shell, but commercial property often includes shorter-life land improvements, personal property, and tenant-related components that accelerate deductions. Commercial assets also offer deduction categories and local tax planning opportunities that many residential deals do not.
Can a cost segregation study work on a smaller commercial property?
Yes, if basis and shorter-life components are meaningful. A modest strip center, mixed-use property, or small medical office building can still justify a study when parking, lighting, tenant buildouts, or specialty improvements create enough reclassification value.
Are tenant improvements deductible right away?
Usually no. Most tenant improvements are capitalized and depreciated, often over 15 years if the improvement qualifies. Smaller items may be expensed under safe-harbor rules. The exact treatment depends on what was installed and how the cost is documented.
Why do large paper losses not always reduce current taxes?
Passive activity rules often limit current use of rental losses. If the activity is passive, losses generally offset passive income only. Real estate professional status and material participation can change that result, but the standards are strict and documentation has to support the claim.
Why is Section 179D so often missed?
Because it sits at the intersection of tax law, engineering certification, and building systems data. Many owners upgrade lighting, HVAC, or the building envelope and never test for eligibility. In commercial property, that leaves one of the most valuable overlooked deductions unclaimed.