
Inherited property tax basis is the tax starting point for measuring gain or loss after a death, and it changes the math far more than most heirs expect. Get this number wrong and sale proceeds, depreciation, and long-term ROI all move in the wrong direction.
What Inherited Property Tax Basis Means
Inherited property tax basis is the value the tax code assigns to property received at death for future gain or loss calculations. Under Section 1014, that basis usually resets to fair market value on the date of death.
That reset is why basis matters so much in real estate. Basis is not a filing detail. It is the number that determines how much capital gain is recognized when inherited property is sold, how much depreciation can be claimed going forward on a rental, and how much equity stays in your pocket instead of going to the IRS.
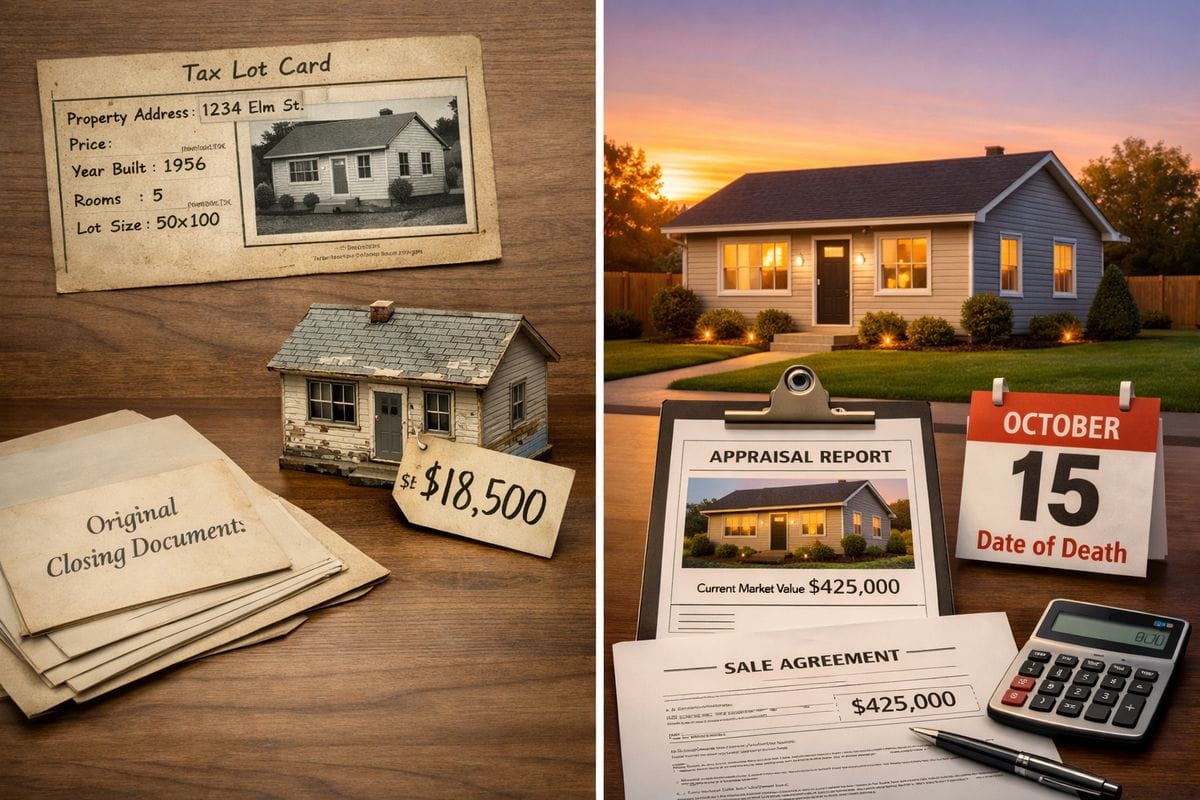
Think of basis as the tax odometer. Death usually resets the odometer to current market value. If a rental climbed from $80,000 to $600,000 over decades, that pre-death appreciation usually disappears for income-tax purposes once the property is inherited.
Why This Rule Matters for Real Estate Investors
For investors, basis treatment drives three outcomes: preserving equity, reducing taxable gain, and improving time-to-value after inheritance. Based on analysis of how inherited rentals are actually sold or retained, basis is often the single biggest tax variable in the first 12 months after death.
If basis resets upward, a sale near date-of-death value often produces little taxable gain. If the property is held, the new basis becomes the platform for future depreciation and future appreciation is measured only from that reset number. That is a much better business outcome than inheriting an old carryover basis from decades ago.
The Three Tax Systems You Must Separate
Most confusion starts here. Basis, capital gains tax, and estate tax are different systems.
Basis determines future gain or loss. Capital gains tax applies when inherited property is sold. Estate tax applies to the transfer of wealth at death, and only to very large taxable estates. Those rules interact, but they are not the same thing.
That distinction matters because step-up in basis affects far more families than estate tax. Federal estate tax reaches 8 out of 10,000 deaths at historic low coverage levels, while basis rules affect anyone inheriting appreciated property.
How the Step-Up in Basis Actually Works
The default rule is simple: inherited property generally receives a new basis equal to fair market value at death. Inherited assets also generally receive long-term treatment for capital gains purposes, even if sold soon after inheritance.
That long-term treatment is easy to overlook, but it matters. A quick sale of inherited property is not forced into short-term capital gains rates just because ownership was brief.
Date-of-Death Value vs. Original Purchase Price
Here is the cleanest way to see it. A rental was bought for $80,000. At death, it was worth $600,000. You inherit it and sell it later for $620,000.
Your taxable gain is generally $20,000, not $540,000. The reset basis is $600,000, so gain is measured from that number, not from the original owner’s purchase price. That is the practical power of inherited property tax basis.
An estate can also elect an alternate valuation date, generally six months after death, in limited situations. If that election is properly made for estate tax purposes, the basis uses that alternate value instead of date-of-death value. That is not the default rule, but it is a real edge case in larger estates.
What a “Step-Up” Really Eliminates
A step-up usually eliminates appreciation that built up during the original owner’s lifetime. That is why highly appreciated rentals, raw land, and family-held investment property see the biggest tax benefit.
The data shows this is especially powerful for assets held for decades. In one farmland example, land acquired at $500 per acre and worth $7,000 per acre at death reset to the higher value, wiping out a $6,500-per-acre gain for income-tax purposes if sold at inheritance value.
When Basis Steps Down Instead
The rule is not always a windfall. If property fell in value before death, basis still resets to fair market value. That means basis can step down.
A rental bought for $500,000 but worth $420,000 at death generally comes into your hands with a $420,000 basis, not the old higher cost. The tax code resets to current value, whether that number helps or hurts.
The Four Drivers That Change Your Basis Outcome
The broad rule is easy. Execution is where money is won or lost. Four drivers control the outcome in practice.
Asset Type
Assets that generally receive a basis adjustment include real estate, taxable brokerage assets, collectibles, art, and some business interests. Assets that do not receive a step-up in the same way include cash, bank accounts, IRAs, 401(k)s, pensions, and annuities. Those retirement assets are usually income in respect of a decedent, which means no fresh basis reset.
For investors, this is a planning line worth respecting. A rental house and an inherited IRA are not taxed under the same logic, even if both arrive from the same estate.
Ownership Structure
Title controls tax results. Sole ownership is straightforward. Joint ownership is not. Revocable trust ownership often preserves step-up because the assets stay includible in the taxable estate. Entity ownership adds another layer, because the result depends on what exactly is inherited and how the entity is taxed.
An LLC does not create a special basis rule by itself. If real estate sits inside a disregarded single-member LLC, the federal tax result often tracks direct ownership. If the inherited asset is a partial membership interest in a partnership-style LLC, valuation discounts, inside basis, and outside basis all become relevant. Partial interests do not escape valuation work just because the underlying asset is real estate.
Marital Status and Community Property Rules
Texas investors need to pay attention here. Texas is a community property state, and that can produce a much better result for a surviving spouse. In general, if community property rules apply and the property is includible in the decedent’s estate, the basis of both halves can reset to fair market value at death, not just the decedent’s half, as explained in IRS Publication 551.
That is a high-value planning point. Title and marital-property classification directly affect tax efficiency at the first death.
Fair Market Value Documentation
The recommendation is simple: document value immediately. If basis cannot be proven, the IRS can challenge it, and in a worst-case scenario treat basis as zero. That is an avoidable tax cost.
Strong support includes a formal appraisal, comparable sales, broker opinions, county records, insurance schedules, and existing valuation reports. Unique property needs stronger evidence than a standard suburban rental. Thinly traded land needs stronger evidence than a house in a busy subdivision.
Inherited Rental Property: Basis, Depreciation, and Sale Strategy
This is where investors usually need more than a basic step-up article. Basis resets, but inherited rental property also carries depreciation consequences.
New Basis for Depreciation Going Forward
Inherited rental property generally starts a new depreciation schedule based on stepped-up basis, after allocating value between land and improvements. Land is not depreciable. Improvements are.
That reset can materially improve after-tax cash flow. A higher building basis means larger future depreciation deductions, which lowers taxable rental income during the hold period and improves projected ROI.
Selling Right Away vs. Holding as a Rental
If you sell close to date-of-death value, taxable gain is often small. If you hold the property, future tax exposure applies only to post-inheritance appreciation plus depreciation recapture created after inheritance.
That changes decision quality. The hold-vs-sell choice becomes an operating decision, not a forced cleanup of decades of built-in gain from the prior owner.
What Happens to Prior Depreciation Taken by the Decedent
Here is the edge case many summaries miss: the old depreciation schedule does not continue in your hands, but prior depreciation does not disappear for every purpose in every situation. The basis for future gain measurement generally resets. Your future depreciation begins from the new basis. But if the property had depreciation issues tied to pre-death periods, especially in more technical transactions, those history files still matter.
For your sale analysis, the practical rule is this: post-inheritance depreciation creates its own recapture exposure later. Keep those records clean from day one. Also note one exception that blocks a fresh step-up entirely: if appreciated property was given to the decedent by you, or by your spouse, within one year before death and then comes back through inheritance, the one-year rule generally denies the reset and restores the old adjusted basis.
Common Misconceptions That Cost Heirs Money
“Inherited Property Is Tax-Free”
The transfer itself is often free of income tax. The later sale is not automatically tax-free. If value rises after death, capital gains tax applies to that post-death appreciation.
“The Estate Tax and Step-Up Are the Same Thing”
They are separate systems. Step-up is an income-tax basis rule. Estate tax is a transfer-tax regime for large estates above the federal exemption. Most estates owe no federal estate tax, but inherited property tax basis still matters.
“An LLC Automatically Improves Basis Treatment”
It does not. An LLC can help with liability separation, management, or succession planning. It does not create magic tax outcomes. Basis depends on inclusion in the estate, tax classification, ownership percentages, and valuation support.
“No Appraisal Means No Problem”
That is backward. No appraisal means weak proof. Weak proof creates delay, disputes, and avoidable tax cost when property is sold or refinanced years later.
Special Cases Investors Should Watch
Inherited Property From a Spouse
In community property states such as Texas, a surviving spouse can receive a basis adjustment on both halves of community property. In non-community-property states, only the decedent’s share usually steps up. The planning takeaway is blunt: title during life controls tax efficiency at death.
Property Held in Trust
A revocable trust often preserves step-up because the asset remains part of the taxable estate. An irrevocable trust does not guarantee the same result. “Trust-owned” is not a useful tax answer by itself. Trust type determines the basis outcome.
Family Partnerships, LLCs, and Closely Held Real Estate
If you inherit an entity interest instead of the real estate directly, basis analysis gets more technical. Valuation of the membership or partnership interest matters. Discounts may affect fair market value. Entity tax classification matters. Inside and outside basis issues may matter. Entity structure changes administration, not the underlying requirement to get basis right.
Farms, Land, and Hard-to-Value Property
Raw land, farmland, mineral-heavy acreage, and unusual properties often produce the largest step-up benefit because appreciation is large and liquidity is low. They also create the most valuation risk. That makes professional appraisal support non-negotiable.
The Documentation Checklist That Protects Basis
Records to Gather in the First 30 Days
Gather the death certificate, deed, trust documents, entity agreements, prior depreciation schedules, property-tax records, insurance schedules, mortgage statements, and any existing valuation reports. Move fast. Records become harder to recover over time.
Valuation Methods That Hold Up Best
A formal appraisal is the strongest support for real estate, especially for income-producing, unique, high-value, or disputed property. For standard assets, credible market data may help, but estimates pulled years later are weak evidence.
Who Should Coordinate the File
The recommendation is a coordinated file managed across an estate attorney, CPA, appraiser, and property advisor. That team structure protects equity, reduces audit risk, and avoids delays when a sale, refinance, or retitling decision arrives.
Frequently Asked Questions About Inherited Property Tax Basis
If You Sell an Inherited House Immediately, Do You Owe Tax?
Usually very little, if sale price closely matches fair market value at death. Gain is measured from inherited basis, not the original owner’s cost. Selling expenses and any price movement after death still affect the final number.
Do You Always Get a Full Step-Up in Basis?
No. The outcome depends on asset type, ownership structure, marital-property rules, estate inclusion, alternate valuation elections, and special exceptions such as the one-year gift-back rule.
Does Texas Change the Federal Basis Rule?
Texas does not change the federal basis rule and does not impose a state income tax. Federal capital gains rules still control. Texas community property law, however, can improve surviving-spouse basis outcomes.
What if You Inherit Only a Partial Interest in Property?
Your basis applies to the fair market value of the interest actually inherited, not automatically to the full property value. A 50 percent tenant-in-common interest needs its own valuation analysis, and lack of marketability or control can affect that number.
Does Depreciation Recapture Get Stepped Up Too?
Post-inheritance depreciation creates recapture exposure when you sell. Pre-death appreciation usually disappears through the basis reset, but rental-property history still matters for technical reporting, entity transfers, and sale planning. The clean rule is to rebuild the depreciation file from the inherited basis immediately.
What Is the Recommendation Before You Sell or Retitle Inherited Property?
Confirm title, secure a date-of-death valuation, review old depreciation records, and get signoff from a CPA and estate attorney before any sale, transfer, or LLC contribution. That is the fastest path to protecting equity and avoiding an irreversible tax mistake.