
Bookkeeping for landlords is not back-office busywork. It is the operating system that protects cash flow, preserves deductions, and turns tax filing into a clean reporting exercise instead of a year-end scramble. The recommendation is a four-phase system: account setup, category design, monthly recording, and tax-ready review.
What this system solves for your rental business
Based on analysis of landlord bookkeeping breakdowns, the same problems show up every time: mixed personal and rental spending, vague expense categories, missing receipts, and unreconciled bank accounts. The result is lost deductions, distorted property performance, and CPA cleanup fees that easily run $200 per hour or more.
A clean system fixes all three business outcomes that matter most. It protects margin, which matters even more with insurance up 26% and maintenance up 12%. It cuts time-to-value because monthly books stay current. And it gives property-level visibility so underperforming rentals stop hiding inside one blended bank account.
Prerequisites: What to set up before starting
Set aside one focused session and gather online access to bank and card accounts, prior statements, lease agreements, mortgage statements, insurance bills, property tax records, HOA statements, utility bills, settlement statements, repair invoices, loan documents, rent rolls, and prior-year tax returns. Also choose a bookkeeping tool before entering a single transaction.
The goal is not a perfect custom accounting system. The goal is a repeatable process that works for 1 to 5 properties and still holds up when the portfolio grows.
Choose your tracking tool
A spreadsheet is enough when transaction volume is low, the portfolio is small, and every property is owned in a simple structure. That works for one or two long-term rentals with a handful of monthly transactions.
QuickBooks Online fits when monthly activity increases and bank feeds, reconciliation, and reporting start saving real time. The catch is that QuickBooks is generic. It handles accounting well, but rental-specific workflows often require property tags, classes, or locations.
Rental-specific software wins on ROI once property-level complexity increases. What the field data shows is simple tools work at low volume, but multiple units, short-term rental payouts, and entity-level reporting drive the need for software built for landlords.
Gather the source documents
Do not build beginning balances or categories from memory. Pull rent rolls, closing statements, mortgage and loan documents, insurance declarations, property tax bills, utility bills, HOA statements, prior invoices, and prior-year returns first.
That one step prevents bad opening balances, duplicate expenses, and missing liabilities. Guesswork always creates cleanup later.
Decide your bookkeeping method
For many landlords, the cash method is the right default. Under IRS guidance, cash-basis taxpayers generally report income when received and deduct expenses when paid (IRS Publication 527).
Consistency matters more than complexity. If the books follow one method all year, the reports stay usable and tax prep stays clean.
Step 1: Open separate financial accounts for rental activity
Mixed-use accounts are the fastest way to lose deductions and waste time. Every rent deposit, vendor payment, tax payment, and reserve transfer should run through dedicated rental accounts.
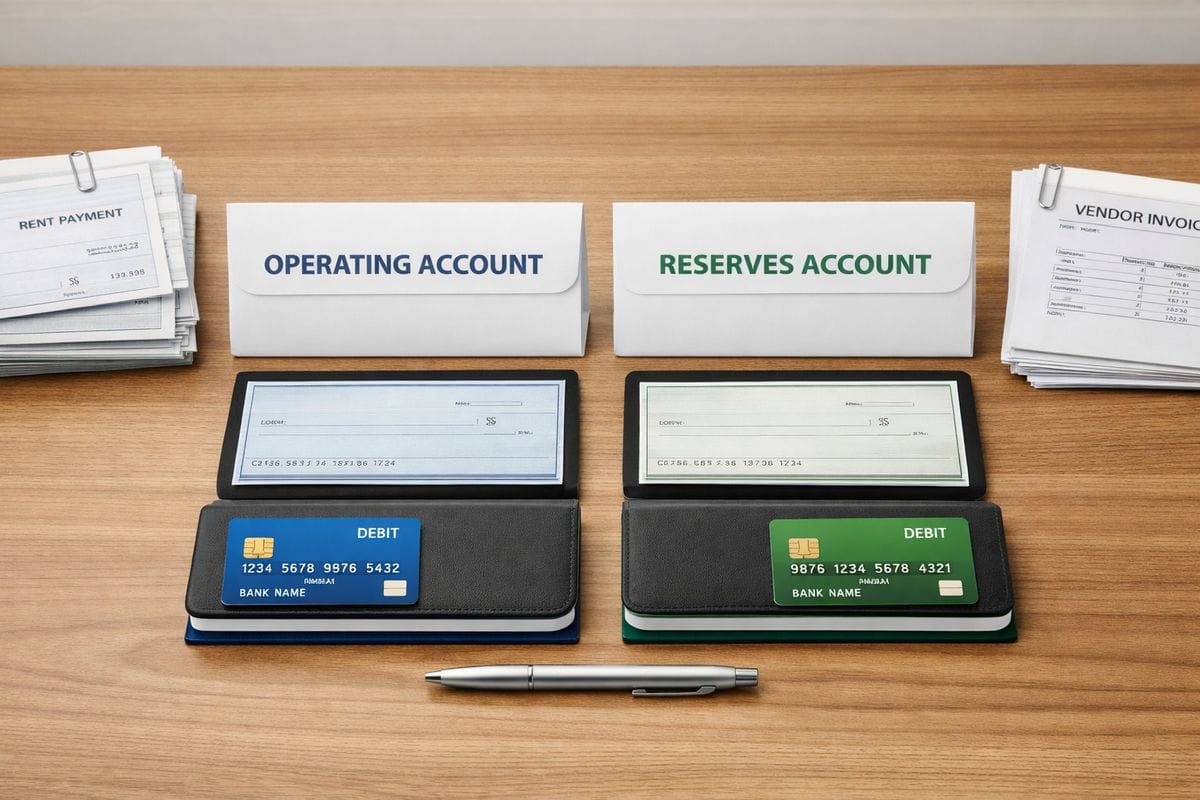
Set up one operating account for rental income and expenses
- Open one checking account used only for rental activity.
- Route all rent deposits into that account.
- Pay vendors, insurance, taxes, utilities, and software fees from that same account.
- Connect the account to the bookkeeping tool.
This creates a single source of truth for reconciliation. If money touches the rental business, it belongs in the rental operating account.
Add a separate savings account for reserves and taxes
- Open a second account for reserves.
- Transfer money into it after rent clears.
- Label portions internally for maintenance, capital expenditures, and tax cash.
That separation improves visibility. Funds already committed to a future roof, turnover, or estimated tax payment stop looking spendable.
Decide whether to use one account per property or one master account
- Use one master operating account with property tags if the portfolio is small.
- Move to property-specific accounts when ownership structures differ or transaction volume rises.
- Keep the approach consistent across the portfolio.
For most small landlords, one master account plus clean property tagging is the best balance of simplicity and control.
Step 2: Build a landlord chart of accounts that matches tax filing
The recommendation is simple: mirror Schedule E line items. Rental real estate income is generally reported on Schedule E for most landlords (IRS Schedule E instructions).
Set up income categories
Use these income accounts:
- Rents Received
- Late Fees
- Application Fees
- Pet Fees
- Laundry Income
- Parking Income
- Other Rental Revenue
- Advance Rent
Advance rent is generally taxable when received, even if it applies to a future period (IRS Publication 527).
Set up operating expense categories
Set up this exact chart of accounts, mapped to Schedule E:
- Advertising → Advertising
- Auto and Travel → Auto and Travel
- Cleaning and Maintenance → Cleaning and Maintenance
- Commissions → Commissions
- Insurance → Insurance
- Legal and Professional Fees → Legal and Other Professional Fees
- Management Fees → Management Fees
- Mortgage Interest → Mortgage Interest Paid to Banks
- Other Interest → Other Interest
- Repairs → Repairs
- Supplies → Supplies
- Property Taxes → Taxes
- Utilities → Utilities
- Depreciation Expense → Depreciation expense or depletion
- HOA Dues → Other Expenses
- Software and Bank Fees → Other Expenses
- Pest Control → Other Expenses
- Lawn Care and Snow Removal → Other Expenses
- Turnover Costs → Other Expenses
This setup works in any bookkeeping system. Create each account as an income or expense category, then assign property tags or classes at the transaction level.
Separate repairs from improvements
- Post routine fixes to Repairs.
- Post betterments, restorations, or major replacements to a fixed asset account.
- Send those asset additions to the depreciation schedule at year-end.
Patching drywall after a tenant move-out is a repair. Replacing the entire roof is an improvement. That distinction changes whether the cost is deducted now or depreciated over time.
Track balance sheet items correctly
- Create Security Deposits Held as a liability account.
- Create Loan Principal as a liability reduction account.
- Create Owner Contributions in equity.
- Create Owner Draws or Distributions in equity.
Security deposits are generally not taxable when received unless kept for damage, lease cancellation, or converted to rent (IRS Publication 527).
Step 3: Organize every property, unit, and entity the same way
Scaling breaks sloppy systems. A ledger becomes useful only when every transaction can be filtered by address, unit, and entity.
Create a naming convention that stays consistent
Use one naming model and never improvise. Example: TX-Dallas-123Main-UnitA. Apply the same structure to properties, folders, leases, and bank rules.
Searchability is the payoff. Duplicate addresses and vague labels create reporting errors fast.
Tag transactions by property and unit
- Assign every income transaction to a property and unit.
- Assign every expense transaction to the property that incurred it.
- Use entity tags if ownership differs across LLCs.
That shows true ROI by address. It also makes year-end reporting fast instead of forensic.
Store digital receipts and contracts in matching folders
Create folders for leases, invoices, tax bills, insurance policies, loan documents, and closing statements using the same property names used in the books. Save every invoice and contract as a PDF.
Documentation matters as much as categorization when defending deductions.
Step 4: Record rental income correctly every time
Rent posting rules need to be boringly consistent. That is exactly why they work.
Enter regular rent and late fees
- Record rent on the date received.
- Match the payment to the bank deposit.
- Split late fees into a separate income account.
That keeps income accurate and makes collection reporting cleaner.
Handle security deposits the right way
- Post the deposit to Security Deposits Held, not income.
- Leave it there until refunded or legally retained.
- Reclassify retained amounts to rent income or damage-related income when facts change.
That keeps profit reports from being overstated.
Record advance rent and lease incentives
- Post prepaid future rent to Advance Rent income when received.
- Record move-in concessions and rent credits clearly in the rent ledger.
- Keep notes attached to unusual lease incentives.
Do not defer advance rent just because it covers a later month. Under IRS rules, it is generally taxable when received.
Account for short-term rental platform payouts
- Record gross booking income from the platform statement.
- Record platform fees separately as expense.
- Record cleaning fees charged to guests separately from cleaning expense.
- Record occupancy taxes based on how the platform handles collection and remittance.
- Match the net deposit to the bank account.
For short-term rentals, substantial services can shift reporting from Schedule E to Schedule C (IRS Publication 527). That item belongs on a tax advisor review list.
Step 5: Record expenses with audit-proof support
Expense accuracy is now a direct margin issue. Rents are up over five years, but operating costs are up too, and sloppy expense tracking hides the damage.
Post recurring fixed expenses
- Enter mortgage interest, insurance, property taxes, HOA dues, software, and management fees.
- Automate recurring entries where possible.
- Review them monthly against actual statements.
Automation reduces errors, but only if the coding is right from the start.
Post variable operating expenses
- Record maintenance, utilities, supplies, cleaning, lawn care, pest control, and turnover costs as they occur.
- Attach the invoice or receipt.
- Add a short note when the business purpose is not obvious.
Split mixed invoices correctly
- Break a mixed vendor bill into separate lines.
- Code repair labor to Repairs.
- Code supplies to Supplies.
- Code major replacements to a fixed asset account.
One invoice can create three different tax treatments. Code it line by line.
Reimburse owner-paid expenses the right way
- Record the expense in its proper category.
- Post the offset to Owner Contributions or Due to Owner.
- Record the reimbursement separately when paid from the rental account.
Do not dump owner-paid items into uncategorized expense. That destroys accuracy.
Step 6: Reconcile accounts every month
Reconciliation is the highest-ROI habit in landlord bookkeeping. It catches missed income, duplicate expenses, coding errors, and transfer mistakes before tax season.
Reconcile bank and card statements line by line
- Match every deposit, payment, fee, and transfer to the statement.
- Investigate every unmatched item.
- Confirm the ending statement balance equals the book balance.
Checkpoint: the reconciled balance should agree exactly with the statement. No exceptions.
Review uncategorized and exception items
- Clear every uncategorized transaction.
- Reclassify suspense items.
- Fix odd vendor charges and unmatched transfers before closing the month.
A tax-ready system has zero mystery transactions.
Verify owner draws, loan payments, and transfers
- Split loan payments between interest expense and principal reduction.
- Confirm reserve transfers are coded as transfers, not expenses.
- Post owner draws to equity, not to property expense.
Your monthly routine should take under 30 minutes per property: 15 minutes to categorize transactions, ongoing receipt capture as bills arrive, and about 10 minutes to reconcile the statement.
Step 7: Run the three reports that drive tax readiness
More reports do not improve decisions. Three reports do.
Profit and loss by property
Review monthly. This report shows revenue, operating costs, and net income by address. It also surfaces miscategorized expenses fast.
Rent roll or income summary
Review monthly. Compare scheduled rent to actual collections, late fees, concessions, and vacancy. Cash-flow problems show up here before they show up in the bank balance.
Balance sheet
Review monthly. This verifies security deposits, reserve cash, loan balances, and owner equity activity. A profit and loss statement will never catch a security deposit posted as income, but the balance sheet will.
Step 8: Prepare a tax-ready file before year-end
Year-end should be packaging, not cleanup.
Match categories to Schedule E lines
Use the chart of accounts already listed and map each account directly to Schedule E. If the books mirror the form, tax prep becomes a copy-and-paste exercise instead of reclassification work.
Pull depreciation-related records
Gather purchase documents for buildings, appliances, and improvements, plus placed-in-service dates and costs. Bookkeeping tracks the spend. Depreciation schedules complete the tax treatment.
Create a year-end document packet
Bundle P&L by property, balance sheet, rent summary, bank statements, Forms 1098, property tax bills, insurance summaries, 1099s received, and major repair or improvement invoices.
That packet cuts CPA prep time and reduces filing delays.
Flag items that need tax advisor review
Short-term rentals with substantial services, cost segregation, material participation, passive loss limits, entity changes, and large improvements deserve proactive review. Quarterly, review the P&L by property, flag miscategorized items, and calculate estimated tax payments.
Troubleshooting: Common landlord bookkeeping mistakes and how to fix them
Mixed personal and rental transactions
Identify personal charges in rental accounts and reclassify them to owner draws. Identify rental charges paid personally and record them as owner contributions, then reimburse properly. Going forward, stop the issue at the source with dedicated accounts.
Missing receipts or incomplete records
Rebuild support using bank statements, vendor portals, email confirmations, and duplicate invoices. Then adopt one rule: capture the receipt when the transaction happens, not at month-end.
Security deposits posted as income
Move those amounts out of income and into Security Deposits Held. Only recognize income when the deposit is legally retained for damage, lease cancellation, or unpaid rent.
Repairs coded as improvements, or the reverse
Recode patching, minor plumbing fixes, and appliance repairs to Repairs. Recode roof replacement, full HVAC replacement, and major remodels to fixed assets. The distinction changes current deductions and depreciation.
Short-term rental income posted incorrectly
Clean up platform deposits by recording gross income, fees, taxes, and net payout separately. If substantial guest services are part of the operation, review Schedule E versus Schedule C treatment before filing.
Expected outcome: What the finished system looks like
The finished system has separate rental accounts, tax-aligned categories, property-level tracking, digital backup, monthly reconciliations, and a year-end file ready for filing or advisor review. It cuts bookkeeping time, protects deductions, and gives a clean base for scaling from a few properties to a larger portfolio.
Next steps: Put the system on a recurring monthly close calendar
Set a weekly habit for transaction capture and receipt storage. Set a monthly close for categorizing transactions, reconciling statements, and reviewing the three core reports. Set a quarterly review for P&L cleanup, estimated tax calculations, and issues that need tax strategy input.
The recommendation is to keep bookkeeping for landlords simple, consistent, and directly aligned with tax filing. That system produces the best ROI because it stays usable every month, not just at year-end.
Frequently Asked Questions
How long should bookkeeping for landlords take each month?
For a small portfolio with clean bank feeds, the system should take under 30 minutes per month per property: about 15 minutes to categorize transactions, ongoing receipt capture, and about 10 minutes to reconcile the statement.
Should every rental property have its own bank account?
Not always. For 1 to 5 properties, one master operating account with clean property tags is usually enough. Separate accounts make sense when ownership structures differ or transaction volume becomes harder to control.
Can a spreadsheet handle rental bookkeeping?
Yes, if the portfolio is small and transaction volume is light. Once rent collection, short-term rental payouts, multiple units, or multi-entity reporting enter the picture, software produces better accuracy and better time-to-value.
Are security deposits taxable rental income?
Generally, no. Security deposits are usually liabilities when received and become taxable only if kept for damage, lease cancellation, or converted to rent under the lease terms (IRS Publication 527).
What is the biggest mistake in landlord bookkeeping?
Commingling personal and rental transactions. That single problem creates missing deductions, distorted reports, and cleanup work across the entire system.
Why match the chart of accounts to Schedule E?
Because it cuts tax prep time and prevents expensive reclassification work. If the books already follow Schedule E categories, year-end filing becomes a reporting task instead of a reconstruction project.