
Your real estate investor entity structure changes more than paperwork. It controls how far a lawsuit reaches, how cleanly rental income flows through your return, how easy financing stays, and how efficiently property passes to heirs. In plain English, entity structure is the legal wrapper around your rentals, and the right wrapper for most investors is simpler than the internet makes it sound.
Why Entity Structure Changes Your Risk, Taxes, and Exit Options
Entity choice is a business decision, not a filing exercise. Based on analysis of common investor setups, the structure determines five outcomes: liability exposure, tax drag, financing friction, transfer efficiency, and scalability.
That matters more now because formal ownership keeps rising. Harvard JCHS found non-individual ownership of rental properties increased from 18 percent in 2001 to 27 percent in 2021, with strong investor concentration in Sun Belt markets including Dallas and Houston. At the same time, market performance is becoming more selective, and return dispersion is widening, which means structure should support disciplined operations, not distract from them.
The three business outcomes that matter most
Three drivers matter most: asset protection, tax efficiency, and transfer or scale. Asset protection determines whether one bad tenant claim threatens a single property or your entire balance sheet. Tax efficiency determines whether income, depreciation, and gain flow cleanly or get trapped inside the wrong vehicle. Transfer and scale determine whether adding properties, partners, or heirs becomes orderly or expensive.
The recommendation is simple: use enough structure to protect meaningful equity and keep operations clean, but stop before complexity starts burning time and fees without improving ROI.
Start With the Baseline: Owning Property in Your Own Name
Direct ownership means title sits in your individual name. For one rental, tax reporting is simple. Income and expenses usually land on Schedule E, there is no entity return for a single owner, and startup cost is basically zero.
The downside is obvious. A claim tied to the property points directly at you, and probate becomes part of the picture at death. Insurance helps, but it does not replace separation between business assets and personal assets.
What it protects: nothing beyond insurance and state-law exemptions.
What it costs: almost nothing to start.
Who it is for: brand-new landlords with one low-risk property and limited equity.
When direct ownership is still defensible
Direct ownership is still defensible for a narrow slice of investors. One low-equity property, strong landlord and umbrella coverage, and a short hold before transfer into an entity can justify keeping title simple.
But that window closes fast. Once equity builds, tenants multiply, or a second property enters the picture, simplicity stops being a strategy and starts being exposure.
Why LLCs Became the Default for Real Estate Investors
The LLC became the default because it fits rental property economics better than anything else. You get limited liability, pass-through taxation by default, flexible management, and fewer bad tax outcomes on sale or distribution than corporations create. Based on field practice and advisor recommendations, the LLC is the starting point for most buy-and-hold investors.
If the goal is deciding when a formal entity actually earns its keep, this is usually the answer.
Single-member LLCs for one-owner rentals
A single-member LLC is one owner, one entity, one clean line between business and personal activity. For tax purposes, it is usually disregarded, so reporting often stays as simple as direct ownership while legal separation improves.
What it protects: personal assets from property-level claims, if formalities stay intact.
What it costs: formation fee, annual maintenance, separate bank account, bookkeeping.
Who it is for: solo investors holding one property or a small cluster.
The catch is that the shield only works if the LLC acts like a real business. Separate bank accounts, leases signed in the entity name, distinct records, and matching insurance are not optional.
Multi-member LLCs for partnerships and spouse-owned properties
A multi-member LLC is usually taxed as a partnership. That means a separate return, K-1s, ownership percentages, capital accounts, and a real need for documented economics. This structure works well when one partner brings cash, another signs on debt, and another handles operations.
What it protects: owners from entity liabilities, subject to guarantees and bad administration.
What it costs: higher tax prep, tighter bookkeeping, legal drafting.
Who it is for: spouse-owned rentals, friends buying together, family investments, private capital deals.
What an operating agreement must actually address
A real operating agreement covers voting, manager authority, distributions, capital calls, transfer restrictions, buyouts, death, disability, and dispute resolution. Anything weaker invites conflict.
This is where many investors get burned. Equal ownership does not mean equal effort, equal guarantees, or equal risk. If that is not addressed up front, deals bleed cash later. For a deeper look at the actual tradeoffs inside rental LLC planning, the structure only works when the paperwork matches the economics.
The Four LLC Strategies Investors Use as Portfolios Grow
As holdings expand, the question shifts from “LLC or not” to “how many, and where?”
One LLC for all properties
One LLC for everything is the lowest-complexity model. One filing, one bank setup, one bookkeeping system. For a very small portfolio, that speed matters.
What it protects: personal assets, but not one property from another inside the same LLC.
What it costs: lowest admin burden.
Who it is for: small portfolios where equity concentration is still modest.
One LLC per property or per risk bucket
This is the cleanest risk-isolation model. One claim stays inside one entity, or inside a grouped bucket such as similar-class rentals in one market.
What it protects: other properties outside that entity.
What it costs: more filings, accounts, returns, and annual maintenance.
Who it is for: investors with rising equity, mixed property types, or different partner groups.
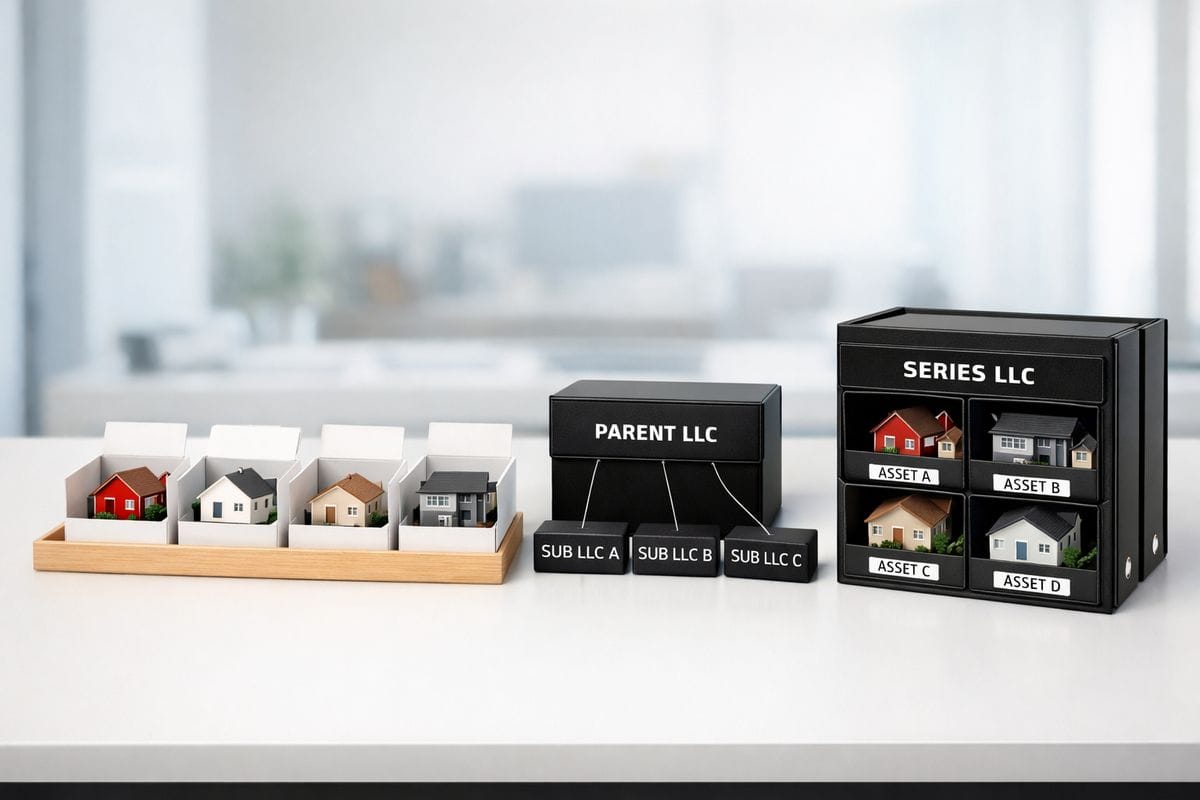
Holding company and subsidiary LLC structure
A parent entity over property-level subsidiaries improves oversight and centralizes ownership interests. It can also make portfolio reporting cleaner.
What it protects: risk isolation at the property level, plus cleaner control at the top.
What it costs: extra compliance and more moving parts.
Who it is for: mid-sized portfolios that need control systems, not just protection.
Series LLCs, with a focus on Texas
Texas makes series LLCs attractive because separate series can hold separate assets under one master filing. For Texas investors, that can reduce filing friction while preserving internal segregation.
What it protects: each series from liabilities tied to another series, if records stay precise.
What it costs: lower filing duplication, but higher discipline in bookkeeping, titling, and insurance coordination.
Who it is for: Texas investors with multiple properties who want segregation without a pile of standalone entities.
Series LLCs are not magic. Lender unfamiliarity, insurer questions, and out-of-state recognition issues are real. For many Texas investors, a series LLC enters the discussion around three to ten properties, not at property one.
Trusts and Estate Planning Vehicles for Real Estate
Trusts solve ownership-transfer problems, not operating liability problems. That distinction matters. A trust can avoid probate, preserve privacy, and create continuity after death or incapacity, but it does not replace the LLC for rental operations.
Revocable living trusts for probate avoidance and continuity
A revocable living trust holds assets during life while preserving control. At death or incapacity, successor management is built in.
What it protects: against probate delay and loss of privacy, not tenant liability.
What it costs: legal drafting and periodic updates.
Who it is for: investors with heirs, aging owners, and anyone who wants continuity.
LLC plus trust: the most common estate-planning stack
This is the most practical stack for long-term investors. The LLC holds the property. The trust owns the LLC interest. That separates operations from succession.
What it protects: liability through the LLC, transfer efficiency through the trust.
What it costs: two layers of setup and maintenance.
Who it is for: investors who want both liability separation and orderly inheritance.
Land trusts get attention for privacy, but privacy and liability are different goals. If that angle matters, review how title privacy tools actually compare.
Irrevocable trusts, family LLCs, and generational wealth transfer
For larger estates, family LLCs and irrevocable trusts become planning tools, not beginner tools. They support gifting, centralized control, and long-term governance. The tax issue that drives many of these decisions is basis. Property transferred at death often receives a step-up, while lifetime gifts generally carry over basis, which can create larger future tax bills.
That is why basis at death versus lifetime transfer deserves attention before gifting LLC interests to children.
Partnerships, LPs, and Joint Venture Structures
When outside money enters the deal, the structure has to price control and conflict correctly.
LLC taxed as partnership vs limited partnership
For small and mid-sized real estate deals, the LLC usually beats the limited partnership. It offers similar pass-through treatment with better flexibility and easier management design. LPs still appear in syndications and family structures where one party wants a classic general partner and limited partner split.
What it protects: LLCs generally shield all members better than a general partnership structure.
What it costs: both require real legal and tax administration, but LLCs are usually easier to customize.
Who it is for: LLCs for most partnerships, LPs for specialized sponsor-investor arrangements.
Structuring partner economics without creating conflict
Preferred returns, waterfalls, promotes, fees, and guarantee compensation must be spelled out before closing. Ambiguity here does not create flexibility. It creates litigation.
The recommendation is direct: tie economics to capital, labor, guarantees, and decision rights in writing, then make sure the operating agreement matches the deal model.
Why S Corps and C Corps Usually Hurt Real Estate Investors
Corporations fit active operating businesses. Appreciating rental real estate is different. The field data shows that corporations create friction where investors need flexibility.
Why S corporations are a poor fit for rental holdings
S corps do not deliver the tax savings many rental owners expect. Rental income generally does not create the same self-employment tax issue that pushes some service businesses toward S corp elections. Add basis complications, payroll concepts that do not fit passive rentals, and ugly rules around property distributions, and the structure loses fast.
What it protects: liability, but no better than an LLC for this use.
What it costs: more tax and admin friction.
Who it is for: almost no long-term rental holding strategy.
Why C corporations create expensive exit problems
C corps are worse. Entity-level tax plus shareholder-level tax creates double taxation, and appreciated real estate inside a corporation becomes painful to distribute, liquidate, or reposition. That destroys flexibility on sale, refinance, gifting, and inheritance. Based on advisor consensus, the recommendation is to avoid C corps for appreciating rental holdings.
Tax Rules That Actually Influence the Structure Decision
Entity choice matters, but tax benefits still come from the property economics.
Pass-through taxation, depreciation, and losses
LLCs usually preserve pass-through treatment. Income, depreciation, and gain flow to the owners without entity-level tax. The entity itself does not create deductions. The building, the debt, the activity level, and the cost segregation strategy create deductions.
QBI, self-employment tax, and common misconceptions
Section 199A gets overused in marketing. Some rentals qualify, some do not, and an LLC alone does not manufacture the deduction. The bigger misconception is that electing S corp status automatically saves taxes on rentals. It does not. For a practical breakdown of where liability protection ends and insurance begins, tax elections are not the same thing as asset protection.
Step-up in basis and sale or transfer planning
Basis planning is where estate strategy and entity strategy meet. A low-basis portfolio passed at death can erase years of built-in gain through a step-up, while gifting the same assets during life can preserve that low basis and shift the tax burden forward. If inherited property planning is on the table, how stepped-up basis works in practice directly affects transfer strategy.
The Hidden Failure Point: Compliance, Financing, and Insurance
Most entity plans fail here, not on paper.
Keeping the liability shield intact
Separate bank accounts. Separate books. Signed leases in the entity name. Annual filings completed. No commingling. If those habits slip, the structure stops doing the job you formed it to do.
Financing and due-on-sale realities
Lenders routinely require personal guarantees, especially for small rental portfolios. Some investors close in an individual name and transfer later because loan programs are easier that way. Before any deed transfer, review mortgage terms, due-on-sale language, title requirements, and insurer expectations.
Insurance still does the heavy lifting
An LLC without proper insurance is incomplete protection. Landlord coverage, liability limits, umbrella policies, and correct named insureds do more day-to-day risk work than the entity itself. Structure and insurance must match.
A Practical Decision Framework for Choosing the Right Structure
Use this flow: start with asset count, then equity concentration, then ownership complexity, then estate goals.
If you own one to two rentals
The recommendation is one clean LLC for one property or a small cluster, plus strong insurance and disciplined bookkeeping. Temporary direct ownership is acceptable only when equity is low and transfer is near-term. Once meaningful equity exists, title in your own name stops making business sense.
If you own three to ten properties
Separate by risk bucket. Add better operating agreements. Consider a holding or management layer only when it reduces admin time across the portfolio. In Texas, this is the stage where a series LLC becomes a real option.
If you own ten-plus properties or plan a family portfolio
At this level, formal mapping matters. Use manager-managed entities, centralized bookkeeping, trust integration, and estate-transfer planning. Family LLC structures become useful when control, gifting, and succession all need to work together.
The Recommendation: Keep the Structure Simple Until Complexity Pays for It
For most U.S. rental investors, the default real estate investor entity structure is an LLC backed by proper insurance. As holdings mature, pair that LLC structure with a revocable living trust for succession. Add multiple LLCs, parent-subsidiary designs, or a Texas series LLC only when portfolio size, equity concentration, or partner complexity justifies the added cost. S corps and C corps are generally the wrong holding vehicle for appreciating rental real estate.
Frequently Asked Questions
Should every rental property go into its own LLC?
No. Separate LLCs make sense when equity is substantial, risk differs by property, or partners differ by deal. For a very small portfolio, one LLC holding a small cluster often delivers better time-to-value.
Does an LLC reduce taxes on rental income?
Not by itself. An LLC usually preserves pass-through taxation, but the real tax drivers are depreciation, financing, expenses, activity level, and sale timing.
Is a trust better than an LLC for rental property?
No. A trust is better for probate avoidance, continuity, and inheritance planning. An LLC is better for operational liability separation. The strongest setup for many long-term investors is LLC plus trust.
Are series LLCs worth it in Texas?
Yes, when multiple Texas properties justify internal segregation and strong recordkeeping is already in place. No, when lender friction, insurance coordination, or out-of-state ownership create more hassle than savings.
Why are S corps and C corps usually bad for real estate investors?
Because appreciating real estate needs flexible exits and clean distributions. S corps create basis and distribution issues. C corps create double taxation and expensive exit problems.