
Real estate investor bookkeeping mistakes do more than create tax-season stress. They distort ROI, hide cash drains, weaken audit readiness, and slow down acquisitions and refinances because the numbers cannot be trusted. Based on analysis of competing content and field data, bookkeeping works best as a profit and tax-planning system, not an admin task, especially when 43% of accounting and tax professionals cite manual work as the top challenge and delayed books reduce visibility.
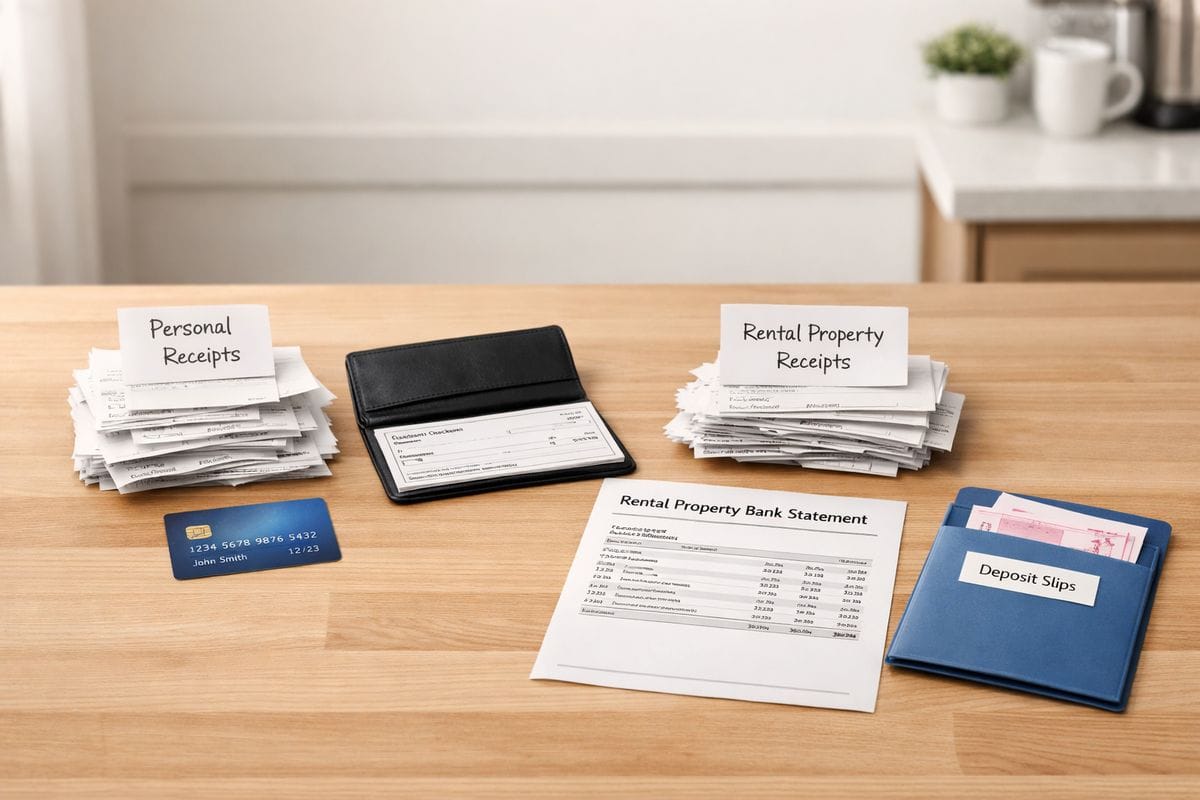
1. Mixing Personal and Business Finances
The mistake is simple: personal charges hit rental accounts, rental charges hit personal cards, and owner transfers get posted with no clear documentation. For Texas investors using LLCs, that is not just sloppy. It weakens entity integrity, corrupts the books, and creates a direct tax compliance problem.
Why investors make it is predictable. Early portfolios feel small enough to manage informally. One card gets used for everything, reimbursements happen “later,” and security deposits get parked wherever cash is available. That approach fails the moment a property has real volume, an insurance issue, or an audit trail request.
Why this mistake is expensive
Personal charges inside business accounts create misclassification, cleanup fees, and audit exposure. They also make owner draws, reimbursements, and actual property expenses impossible to separate cleanly. If a lender, tax preparer, or attorney has to untangle those transactions, the time cost rises fast.
The legal downside is worse. Commingling is one of the fastest ways to undermine LLC liability protection because the entity stops looking separate from you. If the books show no clean line between personal and business activity, the entity starts to look cosmetic.
What clean separation looks like
The minimum standard is direct and non-negotiable: separate bank accounts, separate credit cards, separate security deposit handling, and documented owner contributions and distributions for each entity. If you pay a property bill personally, book it as an owner contribution or reimbursable expense. If you take cash out, book it as a distribution, not a mystery reduction in expenses.
For a 1 to 5 property portfolio, that standard is enough to clean up most reporting issues. For multiple entities, each LLC needs its own bank activity and its own balance sheet.
Dollar example to include
Assume $12,000 per year of mixed personal and rental charges runs through one account. Cleanup takes 8 to 12 extra hours at year-end. At $250 to $400 per hour for bookkeeping and tax cleanup, that is $2,000 to $4,800 in direct cost before tax filing even starts. Add just $3,000 of missed deductible repairs buried in those mixed transactions, and at a 32% combined federal and state-equivalent tax impact assumption for planning purposes, that is another $960 lost. The bigger problem is that your cash flow report is now fiction.
How to fix it: open dedicated accounts immediately, stop paying rental expenses from personal cards, move security deposits to dedicated liability tracking, and document every owner contribution and distribution in real time.
2. Failing to Track Depreciation, Fixed Assets, and Basis
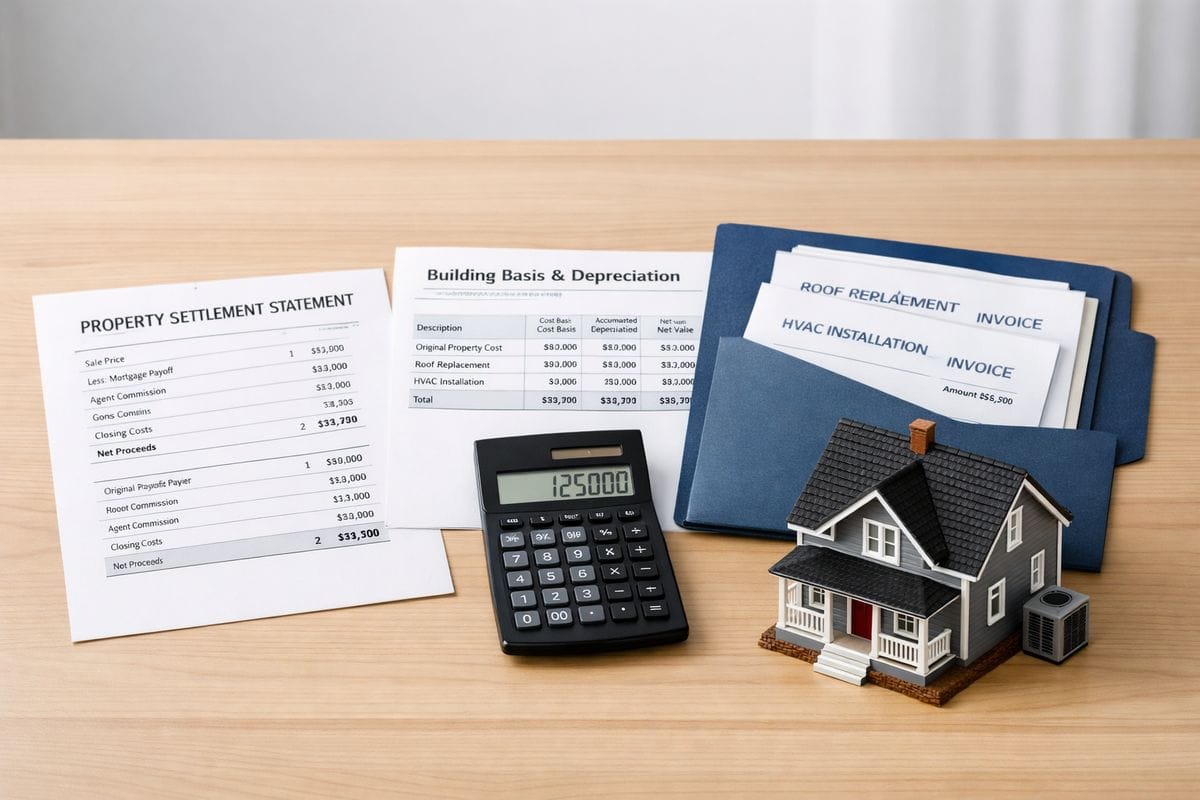
This is the most expensive mistake on the list. The mistake is failing to record depreciation at all, or treating buildings and improvements as if only the cash movement matters. Depreciation is not optional. If you skip it, the tax system still treats that depreciation as allowed or allowable, which means recapture still hits when you sell.
Why investors make it is straightforward. The income statement feels familiar, but the balance sheet and fixed asset schedule do not. A rental property gets purchased, rent starts coming in, repairs get booked, and the building basis never gets set up correctly. Improvements then get buried in maintenance, and basis adjustments disappear.
Why this mistake is expensive
The dollar cost is real and immediate. Use the required example: assume a $250,000 building basis, excluding land. Residential rental real estate is depreciated over 27.5 years. That produces about $9,091 in annual depreciation. Skip that deduction for five years and you leave $45,455 on the table.
Then you sell. Depreciation recapture applies to that same $45,455 even though you never claimed the deductions. At a 25% recapture rate, that is an $11,364 tax bill for deductions you never took. That is not bad luck. That is broken bookkeeping.
The basis problem continues beyond annual depreciation. Every qualifying improvement increases basis and reduces capital gain at sale. If a $20,000 roof and a $15,000 HVAC replacement never get added to fixed assets, taxable gain is overstated by $35,000 when you exit.
Common balance sheet items investors mishandle
Fixed assets, accumulated depreciation, mortgage balances, escrow, security deposits held, prepaid insurance, and loan closing costs all belong on the balance sheet. If those accounts are wrong, the profit and loss statement is incomplete by definition.
Mortgage principal is another common failure point. Principal is not an expense. Interest is. Post the full mortgage payment to expense and taxable income, NOI, and cash flow all get distorted.
Why the balance sheet matters
A clean P&L without a clean balance sheet is not a clean set of books. Refinance packages rely on accurate loan balances, security deposit liabilities, prepaid items, and current asset values. Sale calculations rely on basis and accumulated depreciation. Year-end tax adjustments rely on the exact same information.
Lenders notice weak books quickly. So do buyers during due diligence. If placed-in-service dates, basis allocations, and prior-year depreciation records are missing, transaction timelines slow down and reported numbers lose credibility.
IRS and tax-planning angle
IRS rules draw a clear line: building basis, placed-in-service dates, and capital improvements have to be tracked correctly. Betterments, restorations, and adaptations are capitalized under the tangible property rules and depreciated rather than guessed at. The recommendation is to maintain a fixed asset schedule from day one and update it every time capital work is completed.
How to fix it: set up every property with land separated from building value, record the in-service date, maintain accumulated depreciation, and add every capital improvement to basis. If prior years were missed, correct the depreciation history before the next return goes out.
3. Misclassifying Repairs, Improvements, and Other Key Expense Categories
The mistake is posting everything into generic buckets like “maintenance,” “miscellaneous,” or “property expense.” That habit destroys tax accuracy and makes property analysis useless.
Why investors make it is easy to see. Generic categories feel faster in the moment. But speed at entry creates expensive confusion later, especially for flips, rehabs, and make-ready work.
Repairs vs. capital improvements
Routine fixes are generally current expenses. A leak repair, minor drywall patch, or service call usually belongs in repairs and maintenance. Betterments, restorations, and adaptations are different. A full kitchen renovation, structural rebuild, or conversion of a space to a new use gets capitalized and depreciated.
A $15,000 kitchen renovation is not a repair. Posting it as one inflates current deductions and creates a tax position that does not match IRS rules.
Other categories investors often misclassify
Security deposits are liabilities until forfeited, not rental income on receipt. Mortgage principal is not an expense, while mortgage interest is. Loan fees often need amortization. Owner distributions are not deductible. Tenant reimbursements need consistent treatment. Prepaid insurance belongs on the balance sheet and gets recognized over time.
Why categorization affects tax strategy
Poor categorization causes missed deductions in one area and overstated deductions in another. It also distorts NOI and creates false expectations about taxable income. If your books treat principal, deposits, and capital improvements as current operating expense, your operating performance looks worse while your tax position becomes weaker.
Use a rehab example. Assume $18,000 gets posted to repairs even though $12,000 is capital improvement work and only $6,000 is true repair expense. Current-year deductions are overstated by $12,000. At a 32% tax impact assumption, that is a $3,840 mismatch. If that error gets corrected late, estimated taxes, cash reserves, and sale basis all need revision.
How to fix it: use a real estate-specific chart of accounts, review large invoices before posting, and separate repairs, turns, capital improvements, mortgage interest, loan principal, deposits, and owner activity every month.
4. Failing to Track Income and Expenses by Property
The mistake is keeping books only at the portfolio level. Total rent comes in, total expenses go out, and every property gets blurred together. That is one of the fastest ways to keep underperforming assets longer than you should.
Why investors make it is usually software setup. The chart of accounts exists, but classes, locations, or property tags were never built. In small portfolios, that gets ignored until one property quietly drains cash for a year.
Why property-level books drive better decisions
Property-level P&Ls support rent increases, hold or sell decisions, rehab planning, and refinance readiness. One weak property can be masked by three stronger ones if everything sits in a single bucket. What the field data shows across real estate accounting guidance is consistent: performance tracking only works when each asset stands on its own numbers.
That matters even more in Texas markets where taxes, insurance, and maintenance can swing materially by location. If one property’s insurance jumped 28% and another has stable costs, portfolio-only reporting hides the real issue.
Transactions that must be assigned correctly
Rental income, late fees, repairs, mortgage interest, property taxes, insurance, utilities, HOA dues, turnover costs, capital expenditures, and owner-paid expenses all need property assignment. If you self-manage, travel and mileage related to each property need substantiation too. Reconstructed logs fail IRS scrutiny, so the record has to be contemporaneous.
Fix for small and growing portfolios
For 1 to 5 properties, property or class tracking inside accounting software is enough. For larger portfolios and multiple LLCs, use entity-level bookkeeping with property-level reporting layered inside it. QuickBooks Online supports class and location tracking. Stessa works for simpler rental portfolios. Buildium and AppFolio can handle operational workflows, but accounting still needs clean integration and monthly review.
How to fix it: create a separate tracking dimension for each property, code every transaction at entry, and review property-level P&Ls monthly, not just at year-end.
5. Waiting Until Tax Season to Update the Books
The mistake is delaying bookkeeping until January, February, or even March. That is not just a timing problem. It is a visibility problem that weakens every financial decision made during the year.
Why investors make it is usually workload. Acquisition activity, leasing, repairs, and day jobs crowd out accounting. But stale books always cost more than current books.
What the field data shows
The data shows why disciplined teams close quickly. The average monthly close time is 6.9 business days, and 42% close within five business days or less. At the same time, 20% cite lack of real-time visibility as a major challenge. Delayed books directly reduce decision quality.
Business outcomes lost by delay
Late books block course correction. Rent collection issues sit too long. Maintenance spikes blend into other months. Occupancy problems get noticed after the damage is done. Refinance timing suffers because financials are not lender-ready, and acquisition pacing becomes guesswork because cash reserves are unclear.
Tax estimates also suffer. If year-to-date income is wrong by even $30,000 because books are three months behind, tax planning becomes reactive instead of strategic.
The recommendation
The recommendation is weekly transaction capture, monthly reconciliation, monthly financial review, and quarterly tax-planning check-ins. That cadence keeps books current enough to support decisions and tax strategy.
How to fix it: set a hard monthly close deadline, reconcile bank and credit card accounts every month, review loan balances and deposits held, and resolve uncategorized transactions before the next month starts.
6. Relying on Spreadsheets Instead of a Real Bookkeeping System
The mistake is using spreadsheets as the primary accounting system. A spreadsheet can summarize performance, but it is not a bookkeeping system for a growing rental or flipping business.
Why investors make it is cost and familiarity. Spreadsheets feel flexible. The catch is that flexibility comes with weak controls.
Why manual systems break down
Manual systems fail on version control, formula errors, missing receipts, and nonexistent audit trails. Based on industry survey data, professionals spend 13.8 hours per month on manual entry and reconciliation. That is time spent rebuilding records instead of improving ROI.
The direct dollar cost adds up fast. At $150 per hour of owner or staff value, 13.8 hours per month is $2,070 monthly, or $24,840 per year. That does not include missed deductions from lost receipts or duplicated expenses from copy-paste errors.
What better systems include
A better system includes bank feeds, receipt capture, property or class tracking, recurring rules, document storage, and integration with property management tools. It also creates a searchable history, which matters when a lender asks for support or a tax return needs backup.
Software examples to mention
QuickBooks Online is the practical default for full bookkeeping control. Stessa works well for straightforward rental tracking and tax support. Buildium and AppFolio help larger portfolios operationally, but accounting accuracy still depends on disciplined setup and review.
How to fix it: move transaction entry into accounting software, connect feeds, digitize receipts, and use the spreadsheet only for analysis, never as the book of record.
7. Treating Bookkeeping as Compliance Instead of Tax Strategy
This is the highest-level mistake because it drives all the others. If bookkeeping is treated as something done only to file a return, legal tax reduction opportunities stay hidden until it is too late to act.
Why investors make it is habit. Traditional tax prep is backward-looking, so bookkeeping gets viewed as annual maintenance instead of a decision system.
How clean books unlock tax planning
Proactive tax advisors need current, accurate records to plan depreciation, cost segregation, entity payments, estimated taxes, travel and mileage substantiation, and timing of repairs versus improvements. Clean books also surface often-missed items such as points, prorated property taxes, and prorated interest paid at closing.
Based on analysis of real estate tax outcomes, the upside is not theoretical. Clean records are what make large legal tax reductions possible, including six-figure outcomes in higher-income portfolios.
Specific tax opportunities poor books obscure
Mortgage interest, property taxes, insurance, management fees, travel, mileage, home office where applicable, depreciation, and properly documented rehab costs all depend on accurate books. Poor records also hide basis adjustments that reduce gain on sale.
When to bring in a real estate tax advisor
The trigger is not “large enough someday.” The trigger is operational complexity: multiple entities, short-term rentals, flips plus rentals, rapid portfolio growth, prior-year cleanup, six-figure income shifts, or tax bills that keep rising even though expenses appear higher on paper.
How to fix it: stop treating bookkeeping as year-end compliance, and run quarterly tax reviews using current books so decisions happen before December 31, not after.
Three Controls That Prevent All Seven Mistakes
The recommendation is to build three operating controls into the business. Those controls prevent most breakdowns before they become cleanup projects.
1. Monthly close discipline
Set a monthly close deadline and keep it. Reconcile bank and credit card accounts, verify loan balances, capture receipts, review deposits held, and confirm every transaction is assigned to the correct property before the books are considered closed.
2. Real estate-specific chart of accounts
A tailored chart of accounts reduces miscoding and supports cleaner tax prep and reporting. Separate repairs from capital improvements, principal from interest, deposits held from rental income, and owner contributions from distributions. Generic categories create generic errors.
3. Year-round tax advisor review
Quarterly review beats annual cleanup every time. That is the clearest path to lower surprise tax bills, better ROI, and faster decisions on refinances, sales, and acquisitions.
Frequently Asked Questions
What is the most common bookkeeping mistake real estate investors make?
Mixing personal and business finances is the most common mistake because it corrupts records immediately, hides deductions, and weakens LLC separation. It also creates expensive cleanup work at year-end.
Is depreciation really mandatory for rental property?
Yes. If depreciation is allowed or allowable, recapture still applies at sale even when no deduction was claimed. Skipping depreciation does not avoid tax. It only gives up the deduction.
Should bookkeeping be tracked by LLC or by property?
Both. Each LLC needs its own books, bank activity, and balance sheet. Inside that entity, each property needs separate performance tracking so ROI, cash flow, and hold or sell decisions stay accurate.
Are spreadsheets enough for a small rental portfolio?
No. A spreadsheet can supplement analysis, but it should not be the primary accounting record. Bank feeds, receipt capture, reconciliation history, and property-level coding belong in accounting software.
How often should rental property books be updated?
Weekly transaction capture and monthly reconciliation is the working standard. Quarterly tax review keeps estimated payments, depreciation planning, and timing decisions current.
The Clear Recommendation for Investors Ready to Scale
If books are behind, property performance is unclear, or tax planning starts in March, the recommendation is to rebuild the system now. Accurate, current, property-level bookkeeping drives lower tax drag, better acquisition decisions, stronger lender readiness, and faster time-to-value as the portfolio scales.