
Qualified opportunity zones are designated low-income census tracts where eligible capital gains can receive favorable tax treatment when invested through the right structure. For real estate investors, that matters because the program connects tax deferral and potential appreciation exclusion to long-hold development and redevelopment strategy, not to passive hope or loose marketing claims.
What Qualified Opportunity Zones Are and Why Real Estate Investors Pay Attention
Qualified opportunity zones were created under the Tax Cuts and Jobs Act of 2017 to attract long-term private capital into economically distressed areas. States and territories nominate eligible census tracts, and the U.S. Treasury certifies them. In plain English, a qualified opportunity zone is a map-defined place, not a tax shelter by itself.
The business stake is straightforward. If a large capital gain is sitting on the table, a qualifying Opportunity Zone investment can defer tax on that gain and, under the program structure, offer favorable treatment on future appreciation after a long enough hold. That is why landlords, developers, and investors exiting appreciated stock, business interests, or property keep paying attention.
Real estate fits the program unusually well. Based on analysis of market use patterns, the strongest use cases involve projects that create value over time: ground-up multifamily, mixed-use redevelopment, and substantial rehabilitation in tracts with real tenant demand. The tax benefit is attractive, but the recommendation is to treat it as a return enhancer layered onto a sound deal.
How a Qualified Opportunity Zone Differs From a Qualified Opportunity Fund
This distinction drives the entire program. The zone is the location. The Qualified Opportunity Fund, or QOF, is the investment vehicle.
A property inside a designated tract does not automatically unlock the tax benefit. Eligible gains must be reinvested into a properly structured QOF, and that fund must deploy capital into qualifying Opportunity Zone property or businesses. The IRS specifically centers the program on investing through a Qualified Opportunity Fund.
How the Program Works in Practice: The Four-Phase Investment Path
The mechanics are easier to understand when broken into four phases. That sequence is what determines whether the tax result holds.
Phase 1: Realize an Eligible Capital Gain
The incentive starts with an eligible capital gain. Ordinary income does not qualify. A gain from the sale of appreciated real estate, stock, or another capital asset can start the process, but timing controls the outcome.
Miss the reinvestment window and the core tax benefit is gone. That is why Opportunity Zone planning usually starts before the sale closes, not after cash hits the account.
Phase 2: Reinvest the Gain Into a Qualified Opportunity Fund
The QOF is the required vehicle. A fund can be self-created or managed by a third-party sponsor. Self-created funds offer control, but the tradeoff is full responsibility for structuring, documentation, testing, and ongoing compliance. Third-party funds reduce the operational burden, but sponsor quality becomes a central underwriting issue.
The compliance standard that gets the most attention is the 90% asset test for Qualified Opportunity Funds. In practice, that means the fund must keep at least 90 percent of its assets in qualifying Opportunity Zone property. That sounds simple. It is not. Fund records, testing dates, and asset classification all matter.
Phase 3: Deploy Capital Into Qualified Opportunity Zone Property
Once capital is inside the fund, the fund must invest it in qualifying property or businesses in designated tracts. For real estate investors, this usually means development or redevelopment projects inside a verified zone.
What the field data shows is consistent: the program has been used heavily for ground-up development, substantial rehabilitation, and mixed-use assets. That makes sense because long development timelines and value creation over several years fit the tax design better than quick-turn projects.
Phase 4: Hold Long Enough to Capture the Tax Outcome
Opportunity Zone investing is a long-duration strategy. Historically, the framework has included deferral of the original gain, 5-year and 7-year basis step-ups under the original design, and potential exclusion of post-investment appreciation after a 10-year hold. Current applicability depends on up-to-date law and guidance, so verification before funding is mandatory.
For real estate, that long hold period changes the underwriting lens. Rent growth, operating durability, refinancing options, and exit liquidity matter more than a short-term pop.
The Three Tax Drivers That Make Opportunity Zones Attractive
The tax appeal comes down to three economic drivers, each tied to capital allocation and long-term ROI.
Driver 1: Deferral of Existing Capital Gains
Deferral is the immediate value. When an eligible gain is timely reinvested through a QOF, tax on that original gain is deferred under the program rules. That preserves capital that would otherwise go out the door now.
For investors rotating out of highly appreciated assets, that improves near-term cash deployment. More dollars stay in play for land acquisition, construction, tenant improvements, and reserves.
Driver 2: Potential Reduction Under the Original Holding-Period Rules
The original program structure included basis step-ups tied to 5-year and 7-year holding periods. That feature was part of the initial policy design and remains relevant when evaluating older commentary and competing content on the topic.
Current treatment requires fresh verification. The right way to use this rule in planning is as a legal and tax review item, not as a marketing assumption.
Driver 3: Potential Exclusion of New Appreciation After a 10-Year Hold
This is the headline benefit. If the investment is structured correctly and held for at least 10 years, appreciation on the Opportunity Zone investment itself can receive favorable treatment under the program framework.
That is why the strategy fits value-creation real estate. If a project starts with raw land or obsolete improvements and ends as a stabilized income-producing asset, the tax treatment on that built-in appreciation can materially change after-tax return.
Which Real Estate Investments Tend to Fit Best
Not every real estate deal belongs in a zone strategy. Based on analysis of market use patterns, three categories stand out.
Ground-Up Development and Major Redevelopment
Ground-up and major redevelopment projects often fit best because the hold period is naturally longer and the value creation happens inside the investment. Mixed-use and multifamily are common examples, especially in urban tracts where demand supports lease-up and rent growth.
That said, tract quality still decides the outcome. Some zones sit in improving submarkets with expanding job access and durable housing demand. Others offer weak absorption and thin exit liquidity. The designation alone means nothing.
Substantial Rehabilitation and Value-Add Repositioning
Existing property can qualify when the project meets the required improvement standards. For investors buying older commercial, multifamily, or mixed-use assets, this opens the door to repositioning plays rather than only new construction.
Before closing, planned capital expenditures and business use need to align with current standards. A loose renovation budget and vague business plan are not enough.
When a Qualified Opportunity Zone Deal Is a Poor Fit
The strategy loses appeal when the hold is short, the gain is small, the sponsor lacks execution history, or the zone itself does not support rents, occupancy, and exit value. A flip strategy is usually a poor match because the program rewards patient capital.
Tax benefits do not repair weak fundamentals. If the tract lacks demand, if comparable rents do not justify basis, or if buyers will be scarce at exit, the tax story is irrelevant.
The Compliance Rules That Determine Whether the Tax Benefits Hold
Opportunity Zone investing succeeds or fails on rule execution. That is not a side issue. It is the deal.
Zone Verification, Fund Certification, and the 90% Asset Test
Start with zone verification. Investors can confirm designated tracts using the HUD Opportunity Zones map and cross-check with current federal guidance. Marketing decks are not verification.
Then confirm the fund is properly formed and maintained as a QOF. Ask how compliance is tested, how often asset percentages are reviewed, and what reporting controls are in place. If clear answers are missing, execution risk is high.
Timing Rules, Use Requirements, and Holding Period Discipline
The failure points are predictable: missed reinvestment deadlines, nonqualifying use, and broken holding-period assumptions. Before capital is committed, the transaction needs a documented timeline from realized gain to fund contribution to property deployment.
For rental, development, or redevelopment strategy, this also means checking that the tract supports the intended business use. A zone on the map is not enough. Local rents, vacancy, absorption, and zoning still govern ROI.
Why Tax Counsel and Legal Review Drive Time-to-Value
Experienced tax and legal review shortens the path from realized gain to compliant deployment. That is a business outcome, not administrative overhead.
The recommendation is simple: use advisors who already know QOF formation, fund maintenance, and real estate execution inside designated tracts. Speed without compliance destroys value. Compliance with slow, confused structuring does the same.
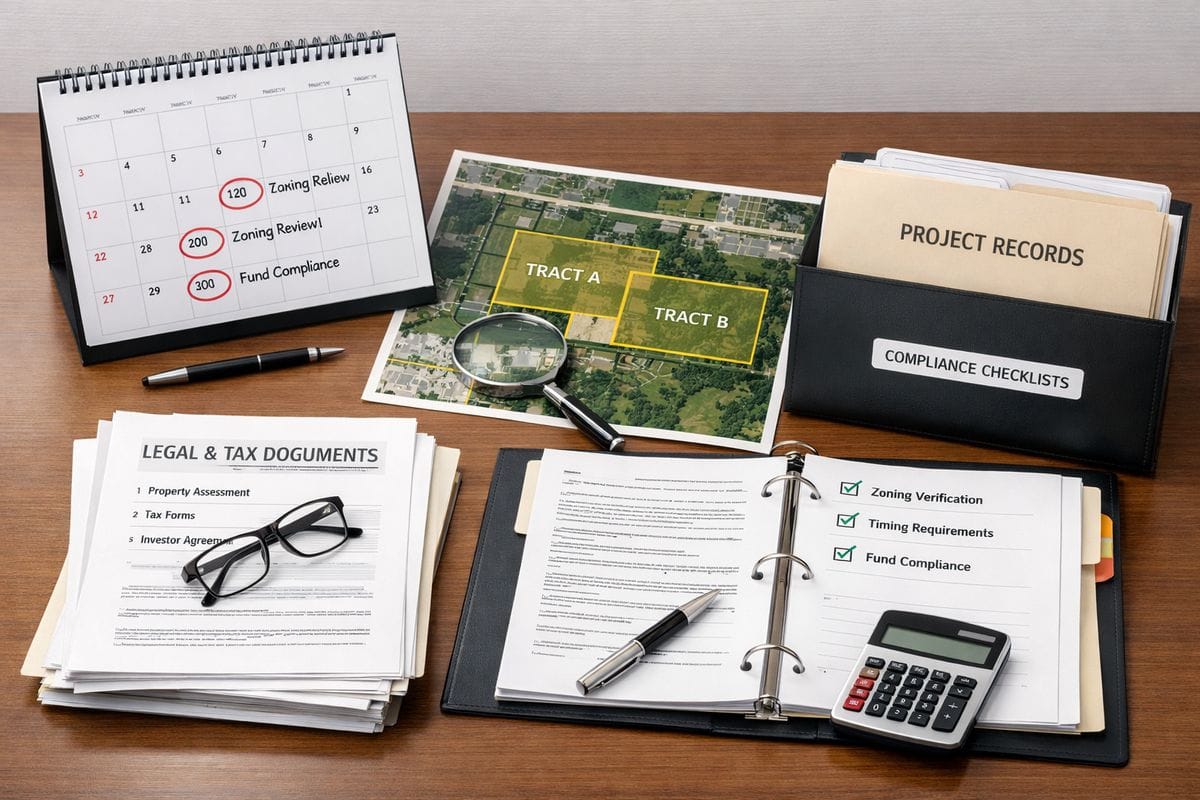
How to Evaluate a Qualified Opportunity Zone Deal Before Committing Capital
The recommendation is to underwrite the real estate first and the tax benefit second. That keeps discipline where it belongs.
The Five Due-Diligence Checks That Matter Most
Use five checks before funding: confirm the zone on the HUD map, confirm QOF compliance, underwrite local demand, evaluate sponsor track record, and test the exit plan against a 10-year hold.
Each check protects ROI. Zone confirmation avoids a false premise. QOF compliance protects tax treatment. Local demand protects rent and occupancy. Sponsor quality protects execution. A 10-year exit test protects strategy drift.
Community Impact vs. Investor Return: What the Field Data Shows
Opportunity Zones were designed to channel capital into underserved communities, but policy intent and project performance are not the same thing. Some projects improve housing stock and activate neglected corridors. Others simply chase tax benefits in weak locations.
Field data shows that outcomes vary with project quality, local demand, and sponsor discipline. The right lens is not moral branding. It is measurable performance in a real submarket.
Common Misunderstandings About Qualified Opportunity Zones
Most first-time confusion comes from three bad assumptions.
“Buying Property in a Zone Automatically Creates the Tax Benefit”
It does not. The investment must run through a properly structured QOF and satisfy the program rules. Buying directly in a qualifying tract without the correct fund structure does not produce the intended tax result.
“Any Distressed Area Counts as an Opportunity Zone”
It does not. Only officially designated census tracts qualify. Verification on the HUD map or through current federal resources is mandatory.
“The Tax Break Makes Any Deal Worth Doing”
It does not. The tax benefit enhances a strong deal. It does not fix poor location economics, weak sponsorship, unrealistic rent assumptions, or a bad capital stack.
Frequently Asked Questions
How do qualified opportunity zones affect rental property strategy?
The strongest fit is long-term rental or mixed-use strategy in tracts with durable demand. If cash flow depends on aggressive rent growth in a weak market, the zone benefit does not save the deal.
Can a self-directed investor create a Qualified Opportunity Fund?
Yes, but control comes with full compliance responsibility. Fund formation, documentation, testing, and ongoing maintenance all need to be done correctly from day one.
How do zones get selected?
States and territories nominate eligible low-income census tracts, and the U.S. Treasury certifies the designations. That is why only specific tracts qualify, not entire neighborhoods.
Is a flip strategy a good fit for Opportunity Zone investing?
No. The program is built around long holds, especially the 10-year appreciation benefit. Quick resale works against the structure.
Where can zone status be verified before buying?
Use the HUD Opportunity Zones map and confirm the exact census tract before signing or funding. Street-level assumptions are not enough because tract boundaries can cut through a neighborhood.
The Recommendation: Use Opportunity Zones Only When Tax Strategy and Real Estate Fundamentals Align
Qualified opportunity zones make sense when four conditions line up in the same deal: a large eligible capital gain, a 10-year investment horizon, a compliant QOF structure, and strong property fundamentals in the actual census tract. Based on analysis of real estate use patterns, that is where the program delivers real after-tax value. The recommendation is to verify current law, confirm the tract on the HUD map, and complete tax and legal review before capital is placed.