
A qualified opportunity fund is an investment vehicle that lets you roll eligible capital gains into designated Opportunity Zones under a specific federal tax regime. For real estate investors and landlords, that matters because the decision affects after-tax ROI, hold period strategy, liquidity, and how confidently capital can be redeployed after a sale.
What a Qualified Opportunity Fund Is and Why It Matters
A qualified opportunity fund, usually shortened to QOF, is a corporation or partnership organized to invest in Qualified Opportunity Zone Property. In plain English, it is the legal container that holds the investment. The zone is the location. The fund is the entity. That distinction is where a lot of confusion starts.
Based on analysis of IRS guidance themes and the way high-performing advisory content explains the program, the value is not “tax shelter” in the casual sense. The value is tax deferral inside a rules-driven structure with ongoing compliance requirements. If your gain qualifies, your timing is right, and the fund stays in compliance, your tax outcome improves. If any of that breaks, the tax story changes fast.
For a property owner, this is a capital allocation question as much as a tax question. Selling appreciated real estate often creates a large gain and an immediate tax drag. A QOF gives you a way to defer that drag while placing capital into a long-duration investment strategy tied to specific communities and specific IRS tests.
How a QOF fits into the Opportunity Zone program
The QOF exists inside the federal Opportunity Zone program created by the Tax Cuts and Jobs Act of 2017. Congress designated certain low-income census tracts as Opportunity Zones to attract long-term private capital. The fund is the mechanism used to move eligible gains into those areas.
That place-based design matters. You are not just buying into a tax structure. You are buying into assets or businesses located in designated zones, which means local market quality, project execution, and neighborhood economics still drive results. The tax rules create upside, but the geography creates real investment risk.
The Four Rules That Control QOF Tax Benefits
Four rules drive the outcome: eligible gains, timing, asset composition, and holding period. That is the operating framework.
What the field data shows is simple: investors see the tax upside first and discover the restrictions later. That is backwards. In this kind of program, compliance mechanics decide whether the tax benefit survives.
Rule 1: Only eligible capital gains qualify
QOF treatment starts with eligible capital gains. Not wages. Not rental income. Not ordinary business income. If the cash came from something other than a capital gain, it does not create the same deferral opportunity.
For landlords and real estate investors, common gain sources include the sale of rental property, the sale of stock, and gains flowing through from partnerships, LLCs taxed as partnerships, or S corporations. That last category gets complicated fast because the recognition date and election timing can vary based on the entity structure. The recommendation is straightforward: identify the exact gain type before focusing on the fund.
Rule 2: The 180-day investment window is nonnegotiable
The 180-day deadline is the gatekeeper for deferral. Once the eligible gain is recognized, the clock starts. If the gain is not invested into a QOF within that period, the deferral benefit is lost.
This is where documentation matters more than most investors expect. You need clear records showing when the gain was recognized and when the QOF investment was made. That becomes even more important with partnership allocations, S corporation distributions, installment sales, or multi-entity ownership structures. A missed date does not create a smaller benefit. It ends the benefit.
Rule 3: The fund must meet the 90% asset test
A QOF must hold at least 90% of its assets in Qualified Opportunity Zone Property. This is not a setup requirement that gets checked once and forgotten. It is an ongoing compliance test, measured semiannually and reported on Form 8996.
Here is the practical point: a fund that fails the 90% asset test can face monthly penalties for the shortfall. More importantly, failed compliance damages investor confidence and creates tax drag. In plain English, the fund has to keep enough of its capital in qualified property, not just promise that it intends to. Branding, pitch decks, and zone maps mean nothing if the asset test is not met.
Rule 4: Holding period drives the biggest upside
A QOF is built for patient capital. The original gain is deferred under the program rules, but the bigger economic appeal comes from a long hold strategy. If the investment is held long enough under applicable rules, appreciation on the QOF investment itself can receive favorable tax treatment.
That changes how you should evaluate the deal. Short-turn projects and early exit assumptions work against the structure. Long-duration investments, stable business plans, and realistic appreciation horizons fit the program far better.
How a Qualified Opportunity Fund Works in Practice
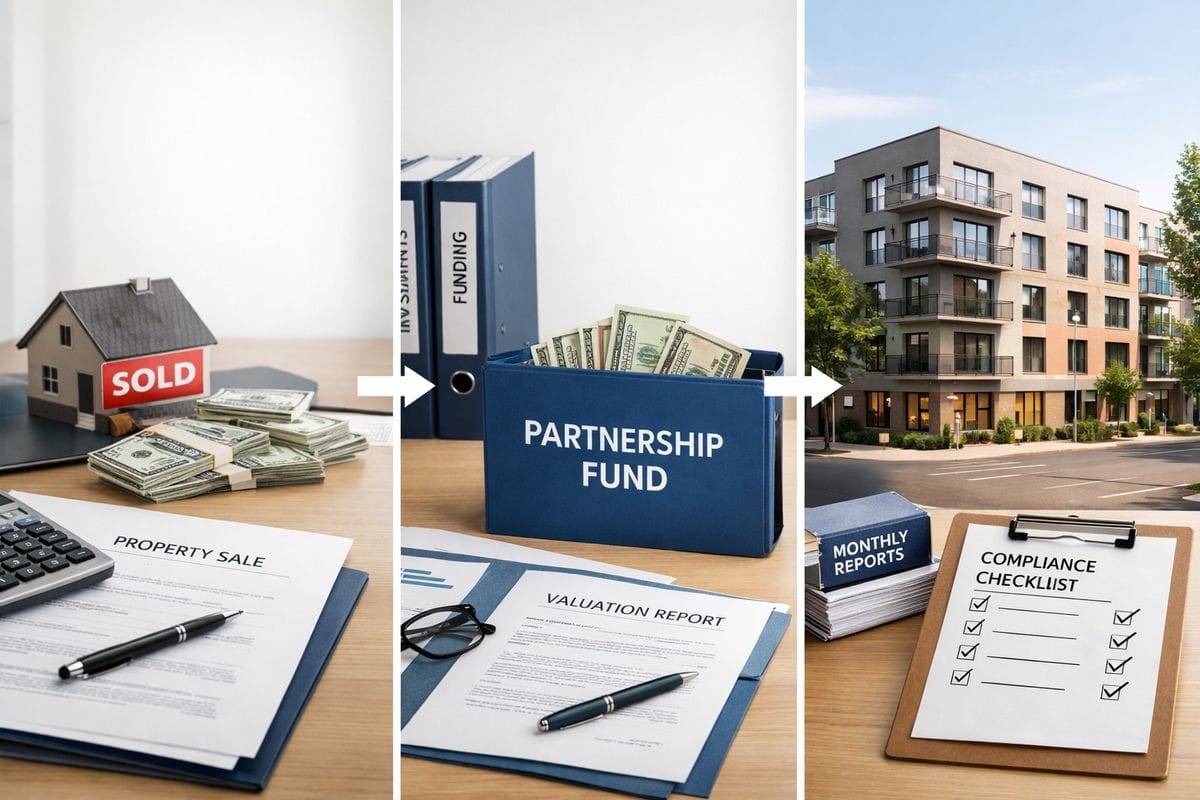
The process follows four phases, from gain event to ongoing reporting. Once you see the sequence, the structure feels much less abstract.
Phase 1: A capital gain is recognized
Everything starts with a taxable capital gain event. That could be the sale of appreciated real estate, marketable securities, or an interest in a business. The moment that event happens, the recordkeeping burden starts too.
Capture the closing statement, gain calculation, entity documents, and recognition date immediately. If those records are sloppy, advisor review slows down, tax reporting gets messier, and the 180-day timeline becomes harder to defend.
Phase 2: Capital is invested into the QOF
Next, the eligible gain amount is invested into a QOF. That fund can be self-certified or professionally managed, but it must actually be organized and maintained as a qualified opportunity fund. A deal advertised as “Opportunity Zone focused” is not enough.
Self-certification is handled through Form 8996, which the fund files with its federal tax return. That filing is the compliance backbone. If a fund cannot clearly show how it is organized and how it reports status, that is a serious warning sign.
Phase 3: The QOF deploys capital into qualified property or businesses
Once funded, the QOF puts money to work in one of the allowed channels. It can hold qualifying real estate directly, invest in qualified opportunity zone business property, or invest in qualified opportunity zone businesses operating in the zone.
For you, the question is simple: where is the capital actually going? Into stabilized housing, ground-up development, an operating business, or a mixed strategy? The answer affects risk, liquidity, and time-to-value. A tax structure does not replace underwriting.
Phase 4: The fund tests, reports, and maintains status
After deployment, the fund has to keep proving it qualifies. That means asset testing, valuation support, annual tax reporting, and maintaining documentation strong enough to survive review. The core IRS form for self-certification and compliance reporting is Form 8996.
This is where disciplined managers separate from promotional managers. A QOF is not defined by the acquisition. It is defined by the ability to stay qualified over time.
The Three Tax Outcomes Investors Need to Understand
The tax payoff has three moving parts. Miss one, and the economics look very different.
Deferral of the original capital gain
If you invest eligible capital gain into a QOF on time, tax on that original gain is deferred under the program rules. That improves short-term capital efficiency because more dollars stay invested instead of going immediately to taxes.
But deferral is not automatic forgiveness. The deferred gain still matters, and you need to plan for when it comes back into income under the statute or earlier triggering events.
Basis adjustments and deferred gain inclusion
Basis is your tax stake in the investment. In a QOF context, basis rules govern how much gain is eventually recognized and how the investment is measured for tax purposes.
Step-up treatment has changed over time depending on investment date and applicable law, which is why older articles can be misleading if read out of context. What matters now is understanding that deferred gain inclusion still happens on the required statutory date or earlier if a triggering transaction occurs. The tax bill does not vanish on its own.
Potential exclusion of new gain on the QOF investment
This is the headline benefit. If the QOF investment is held for the required long-term period, appreciation generated inside that investment can qualify for favorable treatment, including exclusion of post-investment gain under the applicable rules.
That is why QOFs fit long-duration capital. The tax structure rewards staying invested and letting the asset or business compound value over time. For after-tax ROI, that can be powerful. But only if the underlying deal performs.
Due Diligence: What to Check Before Investing in a QOF
Based on analysis of common investor mistakes, five drivers determine decision quality: fund status, manager process, asset quality, reporting discipline, and exit alignment. The recommendation is to review all five before focusing on projected returns.
Verify the fund is actually qualified
Start with legal structure and tax reporting. The fund must be organized as a corporation or partnership and self-certify as a QOF through Form 8996. If that proof is missing, the fund is not qualified in any meaningful sense.
This sounds basic, but it is where many mistakes begin. An asset can sit inside an Opportunity Zone and still fail to deliver QOF tax treatment if the entity structure is wrong.
Evaluate compliance discipline, not just projected returns
A manager’s compliance process matters as much as the underwriting deck. Review how the 90% asset test is monitored, how valuations are supported, how quickly capital is deployed, and how reporting is maintained.
Based on a review of recurring guidance themes, compliance failure creates avoidable tax drag and extends time-to-value. Good returns on paper do not offset a fund that cannot stay within the rules.
Underwrite the underlying real estate or business like any other investment
A QOF does not rescue a weak deal. You still need to evaluate market fundamentals, sponsor quality, operating assumptions, rent growth, liquidity, and exit horizon.
That is the business reality. Tax benefits improve net return. Asset performance drives the core result.
Common Misconceptions and Investor FAQs
Is a QOF the same as an Opportunity Zone?
No. An Opportunity Zone is the designated geographic area. A QOF is the investment entity that places eligible capital into qualifying property or businesses inside that area. Confusing the two leads to bad diligence and bad tax assumptions.
Does every property in an Opportunity Zone qualify?
No. Location alone does not make an investment qualified. The fund structure, the asset type, the business use, and the ongoing compliance tests all have to line up.
Is this only for real estate investors?
No. Real estate dominates the market because the structure fits long-hold property strategies well, but QOFs can also invest in qualifying businesses and business property located in Opportunity Zones. That makes the program relevant for property owners looking to diversify gain proceeds.
Is a QOF just a tax shelter?
No. It is a federally defined investment structure with strict timing, asset, and reporting requirements. The tax benefit exists only when those operational rules are satisfied.
The Recommendation: When a Qualified Opportunity Fund Makes Sense
A QOF makes sense when you have a recent eligible capital gain, a long hold horizon, tolerance for illiquidity, and confidence in the manager’s compliance process. Based on analysis of the field, the right way to evaluate a qualified opportunity fund is as a combined tax-and-underwriting decision.
Proceed only when two things are true at the same time: the underlying deal works on fundamentals, and the fund can prove ongoing compliance with the 180-day rule, the 90% asset test, and Form 8996 reporting. That is the standard that protects after-tax ROI.
Frequently Asked Questions
Can ordinary income be invested into a qualified opportunity fund for the same tax benefit?
No. The QOF deferral regime is built around eligible capital gains. Ordinary income does not qualify for that specific deferral treatment.
What happens if a fund fails the 90% asset test?
The fund can face monthly penalties for failing the test, based on the amount of the shortfall. Beyond the penalty, failed compliance undermines the tax value proposition and raises serious diligence concerns.
Does a self-certified QOF have less value than a professionally managed QOF?
No. Self-certification is allowed under the rules. The real issue is execution: entity setup, asset qualification, testing discipline, and accurate Form 8996 filing.
Is Form 8996 filed by the investor or the fund?
Form 8996 is filed by the fund. It is used to self-certify as a QOF and report compliance with the asset test.
Why are QOFs considered long-term investments?
Because the strongest tax outcome depends on holding the QOF investment long enough under the applicable rules. The structure is designed for patient capital, not short-term flips.