
The SALT deduction cap 2026 rule matters because it changes how much state and local tax you can write off on your federal return, and that directly affects after-tax portfolio ROI. For real estate investors, the bigger story is not just the higher cap. It is knowing which taxes belong on Schedule A, which belong on Schedule E, and which tax rules still block rental losses no matter what happens to SALT.
What the SALT Deduction Cap Is in 2026
The SALT deduction is the federal itemized deduction for certain state and local taxes you already paid. In 2026, the cap is $40,400 for most filers and $20,200 for married filing separately.
That is a major increase from the old TCJA-era $10,000 cap, but it is not a full repeal. The deduction is still capped, still only available if you itemize, and still reduced for higher-income households. For investors, that means better tax treatment for some personal state and local taxes, not unlimited deductibility.
Which taxes count toward SALT
SALT includes state and local income taxes or state and local sales taxes, plus real property taxes and personal property taxes. The key rule is simple: you can deduct income taxes or sales taxes, but not both on the same return.
For most real estate investors, the biggest personal SALT items are state income tax withholding from W-2 wages and property taxes on a personal residence. If you live in a no-income-tax state, sales tax can be relevant, but it still competes with the income tax deduction election. You do not stack both.
What does not count
A lot of investors misclassify non-SALT costs. Federal income taxes do not count. Social Security and Medicare taxes do not count. HOA fees do not count. Transfer taxes, estate or inheritance taxes, utility charges, and similar assessments do not count either.
That distinction matters because inflated expectations lead to bad projections. If a tax or fee is not one of the qualifying state or local taxes allowed under Schedule A rules, it does not increase your SALT deduction.
What Actually Changes in 2026 vs. the Old $10,000 Cap
The strategic stake is straightforward: a higher SALT cap can make itemizing worthwhile again, and that can improve after-tax cash flow from your overall household tax picture. But the benefit is narrower than the headlines suggest.
Under the TCJA structure, most taxpayers were stuck at a $10,000 SALT deduction cap, or $5,000 if married filing separately. In 2026, that ceiling jumps to $40,400 for most filers. That is a real change, especially if you own a high-tax personal residence or earn wages in a high-tax state. But the benefit still runs through itemized deductions, income phaseouts, and the rest of your return. It is not a free-standing tax break.
The annual inflation-style increase and 2030 reset
The cap rises from $40,000 in 2025 to $40,400 in 2026. After that, it increases by 1 percent annually through 2029, then reverts to $10,000 in 2030 unless Congress changes the law again.
That temporary structure matters for portfolio planning. A deduction that exists for four filing seasons and then snaps back is not something to bake into a long-term return model as if it were permanent. Use it for tactical planning. Do not treat it as a fixed feature of your ten-year projections.
The 2026 income phaseout
High earners do not automatically get the full expanded deduction. In 2026, the phaseout begins at $505,000 of modified adjusted gross income. Above that level, the cap is reduced by 30 cents for every $1 of MAGI above the threshold until it hits the $10,000 floor.
The math is mechanical. If your MAGI is $50,000 over the threshold, your cap is reduced by $15,000. Starting from $40,400, that leaves a $25,400 cap. Once income rises far enough, the benefit compresses back to the same $10,000 floor that applied before.
Three Rules That Determine Whether the Higher Cap Helps Your Portfolio
For investors, the value of the 2026 SALT change comes down to three drivers: whether you itemize, where you pay taxes, and whether you are confusing SALT with passive-loss rules. Based on analysis of investor tax outcomes, that is where the real ROI decision sits.
Rule 1: The higher cap only matters if itemizing beats the standard deduction
A bigger SALT cap creates tax value only if your total itemized deductions exceed the standard deduction. If itemized deductions still come in lower, the higher SALT limit changes nothing on your filed return.
That is not a minor point. It is the whole point. After TCJA paired the SALT cap with a higher standard deduction, the share of returns claiming SALT fell from 31% in 2017 to 9% in 2022. A lot of taxpayers stopped itemizing because the math no longer worked. The 2026 cap pulls some households back into itemizing territory, but not all.
Rule 2: High-tax-state investors gain the most
If you live in New York, California, New Jersey, or Connecticut, the expanded cap has obvious value because state income tax and personal property tax can exceed $10,000 very quickly. In those states, a higher cap can turn a heavily limited deduction into a meaningful one.
If you live in Texas, Florida, Tennessee, or another no-income-tax state, the story is different. The benefit comes mostly from personal residence property taxes and any elected sales tax deduction. That is still useful, but the ceiling is harder to hit unless your home value is high and your other itemized deductions are strong.
Rule 3: A bigger SALT deduction does not override passive activity rules
This is where investors make expensive mistakes. SALT is an itemized deduction on Schedule A. Rental losses are governed by passive activity rules under IRC §469. Those are separate systems.
A higher SALT cap does not release suspended passive losses. It does not change the $25,000 special allowance. It does not replace the need to test active participation. It does not make Real Estate Professional Status irrelevant. If your rental losses are suspended against W-2 income today, the 2026 SALT increase does nothing to fix that problem. Different bucket. Different rule set.
How the SALT Cap Interacts With Rental Property Ownership
The operational issue is separating personal taxes from rental expenses correctly. That sounds basic, but this is exactly where returns get muddled.
Personal residence property taxes vs. rental property taxes
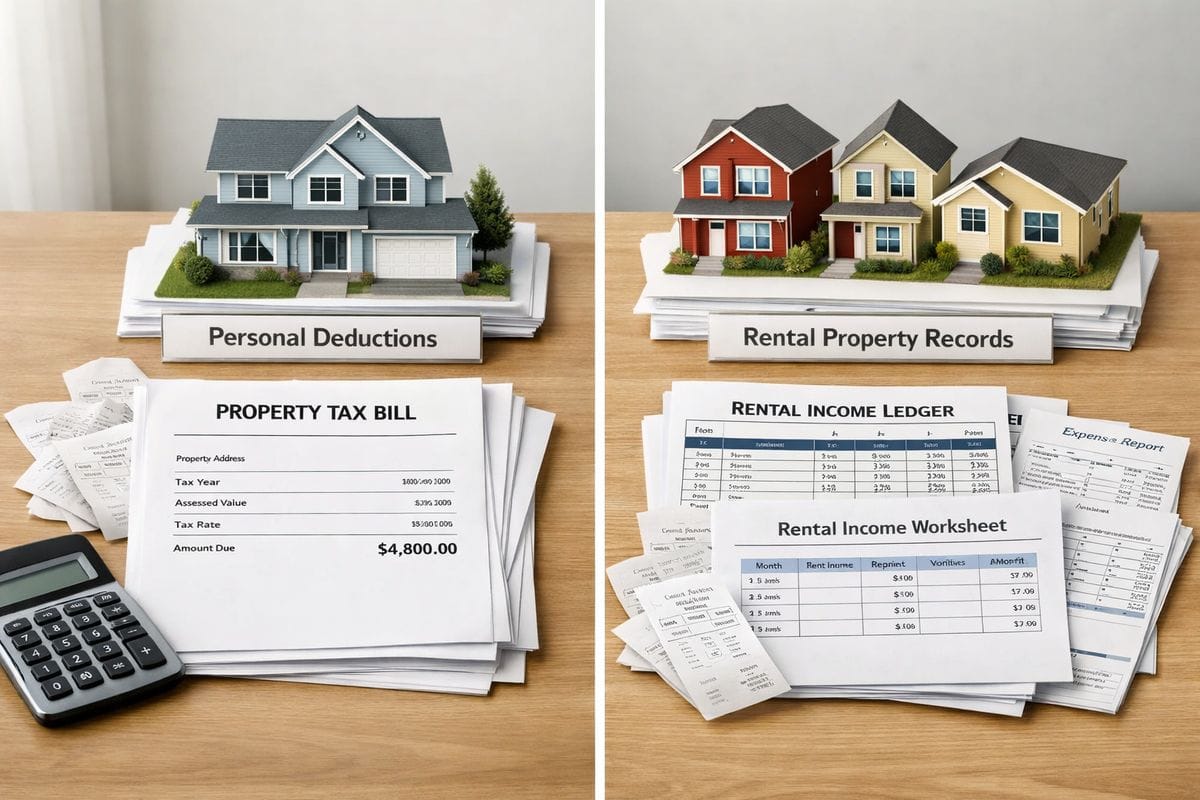
Property taxes on your personal residence belong in the itemized deduction bucket and count toward the SALT cap. Property taxes on rental property are generally deducted against rental income on Schedule E as an operating expense. Those rental property taxes are not limited by the personal SALT cap.
That distinction is not new in 2026. It has been true the entire time.
Use a concrete example. If you own a Texas personal residence worth $800,000 and pay $14,000 in property taxes, that $14,000 is a personal property tax amount that sits in the Schedule A bucket and is subject to the SALT cap. If you also own three Texas rentals and each rental pays $8,000 in property taxes, the $24,000 total on those rentals is deducted on Schedule E against rental income. It is fully deductible as a rental expense regardless of the personal SALT cap. Only the $14,000 personal residence tax is part of your SALT-cap calculation.
That is the misconception to eliminate: the SALT cap does not affect rental property tax deductions, and it never did.
State income taxes from wages, pass-through income, and rentals
State income taxes you pay personally, such as withholding from W-2 wages or quarterly estimates tied to personal income, can feed into SALT. But taxes paid at the entity level can follow different rules depending on structure and state law.
That tracing matters. If the tax is paid personally, it is generally part of your personal deduction analysis. If the tax is imposed and paid at the entity level, especially under pass-through entity tax regimes, it can fall under a different rule set entirely. More than 30 states have authorized PTET-style workarounds that can bypass part of the personal cap structure, and state PTET workarounds remain a separate planning track from the federal personal SALT limit.
Where Investors Commonly Misread the 2026 Change
Most SALT planning errors come from treating one tax rule as if it solved another. It does not.
“A higher SALT cap means every investor gets a bigger deduction”
False. You only benefit if itemizing beats the standard deduction, and the phaseout reduces the benefit once MAGI crosses the threshold. A household with modest itemized deductions still takes the standard deduction and gets no practical gain from a larger cap.
“The SALT cap increase fixes the passive loss problem”
False. Passive loss limitations under IRC §469 still control whether rental losses offset W-2 income, portfolio income, or both. A bigger Schedule A deduction does not release suspended losses from Schedule E.
For a W-2 earner holding rentals at a loss, that means the 2026 SALT change can improve itemized deductions while rental losses remain trapped. Those two outcomes regularly happen on the same return.
“Real Estate Professional Status changes the SALT cap”
False again. REPS can change the treatment of rental losses if material participation standards are met. It does not change the SALT cap, the Schedule A deduction framework, or the income phaseout formula.
That is why tax-planning effort needs to be allocated correctly. If the issue is suspended rental losses, analyze REPS and material participation. If the issue is limited personal state and local taxes, analyze itemizing and SALT. Mixing the two wastes time.
Practical 2026 Scenarios for Real Estate Investors
Examples show the real decision point better than abstract rules.
Scenario 1: W-2 earner with rental losses in a high-tax state
Assume $260,000 of W-2 income in California, $18,000 of state income tax, $16,000 of personal residence property tax, and suspended rental losses from two properties. Under the old $10,000 cap, only $10,000 of those personal taxes was deductible on Schedule A. In 2026, up to $34,000 of those SALT payments can count, because the total is below the $40,400 cap.
That improves itemized deductions materially. But the suspended rental losses stay suspended unless active participation, the special allowance, or another §469 rule changes the result. Higher SALT deduction, same passive-loss limit.
Scenario 2: Married couple with rentals whose deductions still do not exceed the standard deduction
Assume a married couple with $300,000 of income, modest mortgage interest, $14,000 of state income tax, and $11,000 of personal property tax. The higher cap means the full $25,000 personal SALT amount can potentially count. But if total itemized deductions still remain below the standard deduction, the couple still takes the standard deduction.
That is not theoretical. A consumer example shows that a married couple in California with $300,000 of income can still end up better off using the standard deduction. The recommendation is simple: run the itemizing math before assuming the cap increase delivers savings.
Scenario 3: Higher-income investor above the 2026 phaseout threshold
Assume $560,000 of MAGI. That is $55,000 above the $505,000 threshold. The cap is reduced by 30 percent of that excess, or $16,500. Starting from $40,400, the available cap falls to $23,900.
There is another drag at this income level. Starting in 2026, taxpayers in the 37% bracket see the value of itemized deductions effectively capped at 35 percent. That does not erase the deduction, but it trims the marginal value. For higher-income investors, the headline cap overstates the actual tax benefit.
What to Review Before 2026 Filing Season
The right response is not excitement. It is separation, modeling, and targeted planning.
Confirm which taxes belong on Schedule A and which belong on Schedule E
Separate personal state and local taxes from rental operating expenses before year-end. Personal residence property taxes, personal state income tax payments, and elected sales taxes go into the Schedule A analysis. Rental property taxes stay with the rental activity on Schedule E.
For investors with multiple entities, trace the payment path. If a tax is paid by a rental entity or through a state PTET regime, do not assume it belongs in the same bucket as personal SALT.
Model itemized deductions against the standard deduction
Run a side-by-side projection using mortgage interest, charitable gifts, and personal SALT. That projection tells you if the expanded cap changes your filing strategy or just looks good in a headline.
Based on analysis of actual filing patterns, this is where the return on planning time shows up. If itemizing still loses, there is no reason to build a tax strategy around the cap increase.
Evaluate entity-level and state-specific workarounds
PTET elections and similar state-level structures remain relevant, especially for pass-through income. Those strategies are separate from the federal personal SALT cap and require state-by-state review.
The recommendation is to treat entity-level taxes as a dedicated planning track, not as an afterthought to personal itemized deductions. That separation protects ROI and reduces filing errors.
What Happens After 2029 and Why the 2030 Reversion Matters
The current expansion is temporary. Your long-range planning should reflect that reality.
If you are underwriting acquisitions, projecting cash flow, or deciding on estimated payments across multiple years, do not assume the 2026 cap lasts forever. It rises modestly through 2029, then falls back to the old baseline in 2030 unless Congress acts again. A short-lived benefit should not carry the same weight as a permanent structural deduction.
Why the policy debate matters for investors
The policy fight is not background noise. It directly affects planning certainty. Based on congressional distribution data, taxpayers with incomes of $200,000 and above were projected to receive 65% of SALT benefits while making up only 12% of tax units. That concentration keeps the deduction politically exposed.
For investors, that means the 2030 reset is a real planning variable. Do not ignore it in multi-year forecasts, especially if your current after-tax return assumptions rely on large personal property tax or state income tax deductions.
Recommendation: Use 2026 as a Tax-Planning Checkpoint, Not a Shortcut
Treat the 2026 SALT cap increase as a tactical opportunity, not a shortcut. Re-run itemizing projections. Separate personal taxes from rental expenses correctly. Evaluate passive-loss strategy under IRC §469 on its own terms.
The field data shows the highest ROI comes from coordinated planning across Schedule A, Schedule E, and passive-loss rules, not from the cap increase alone. If you own a high-tax personal residence, the expanded cap can create real savings. If you own rentals, keep the core distinction in view: personal residence taxes face the SALT cap, rental property taxes remain deductible on Schedule E. That is the rule that drives accurate planning.
Frequently Asked Questions
Does the SALT deduction cap 2026 apply to rental property taxes?
No. Rental property taxes are generally deducted on Schedule E as rental expenses. The personal SALT cap applies to itemized deductions on Schedule A, such as property taxes on your personal residence.
If you live in Texas, does the 2026 SALT cap still matter?
Yes, but mostly for personal residence property taxes and any elected sales tax deduction. If you own an $800,000 Texas home with $14,000 of property taxes, that $14,000 sits in the Schedule A SALT bucket. If you also have three rentals with $24,000 of total property taxes, that rental amount stays deductible on Schedule E and is not capped by SALT.
Does Real Estate Professional Status increase the SALT cap?
No. Real Estate Professional Status affects how rental losses are treated under IRC §469 if material participation rules are met. It does not change the SALT cap, the phaseout threshold, or the Schedule A rules.
What happens to the 2026 SALT cap if MAGI is above $505,000?
The cap is reduced by 30 cents for every $1 of MAGI above $505,000 until it reaches the $10,000 floor for most filers. Higher income reduces the available deduction even if state and local taxes paid are much higher.
Is the 2026 SALT cap a permanent change?
No. The cap increases through 2029 on a 1 percent annual schedule, then reverts to $10,000 in 2030 unless Congress changes the law again. Long-term tax planning should treat the expansion as temporary.
Does a higher SALT cap mean itemizing is automatically better in 2026?
No. Itemizing only helps if total itemized deductions exceed the standard deduction for your filing status. The higher cap improves the odds for some households, especially in high-tax states, but it does not guarantee a better result.