
SDIRA real estate investing means using a self-directed IRA to buy real estate or real-estate-related assets inside your retirement account instead of holding only stocks, bonds, and mutual funds. The appeal is obvious: more control, better alignment with your real estate skill set, and favorable tax treatment. The risk is just as obvious once you understand the rules, because one bad transaction can wreck the IRA’s tax status and erase the upside you were chasing.
What SDIRA Real Estate Investing Actually Means
An SDIRA is still an IRA. That point matters more than most investors realize. “Self-directed” means you choose from a wider set of investments, including rentals, land, notes, syndications, and certain private deals. It does not mean you get to ignore the tax code, move money around casually, or treat the property like part of your personal portfolio.
In plain English, sdira real estate investing means your IRA becomes the investor and holds real estate inside the account’s tax structure. If the account is a traditional SDIRA, income and gains generally stay tax-deferred. If the account is a Roth SDIRA, qualified withdrawals are tax-free. That tax wrapper is the whole point.
The strategic stake is bigger than tax savings alone. You gain control over retirement capital, diversify beyond public markets, and put money into an asset class you already understand. But the field data shows the real dividing line is compliance. Real estate mistakes inside a taxable LLC are usually annoying. Real estate mistakes inside an IRA can be catastrophic.
Why This Strategy Gets Attention From Real Estate Investors
Real estate investors pay attention to SDIRAs because the structure solves a familiar frustration: retirement money often sits in index funds while your best knowledge lives in local property markets. If your edge is underwriting rent houses in Dallas, identifying development corridors outside Austin, or pricing distressed assets in Houston suburbs, an SDIRA lets retirement capital follow that knowledge.
Scale also explains the attention. U.S. retirement assets exceeded $49.1 trillion at the end of 2025, with IRAs holding $19.2 trillion, and real estate remains one of the most widely used SDIRA asset classes according to industry surveys. That is not niche behavior. It is a mainstream retirement pool looking for alternatives to public markets.
For experienced investors, the appeal usually comes down to three outcomes: tax-deferred or tax-free growth, diversification away from stock volatility, and direct control over asset selection. That said, attention is not the same as fit. Plenty of strategies look attractive on YouTube and fail in real life because they require perfect paperwork, patient custodians, and cash sitting idle for reserves.
How an SDIRA for Real Estate Works
At a high level, the IRA buys and owns the asset, the custodian administers the account, and every dollar related to the investment has to move through the IRA. Think of it like a sealed container. Money enters through contributions, transfers, and rollovers. It exits through approved investment activity and qualified distributions. You do not dip in and out personally.
That structure changes how every deal works. Offers, earnest money, closing funds, rent collection, expense payments, sale proceeds, and loan documents all have to reflect IRA ownership and custodian process. If you are used to moving fast with personal funds, this feels slow. Because it is slow.
Who Actually Owns the Property
Your IRA owns the property. Title is not in your personal name.
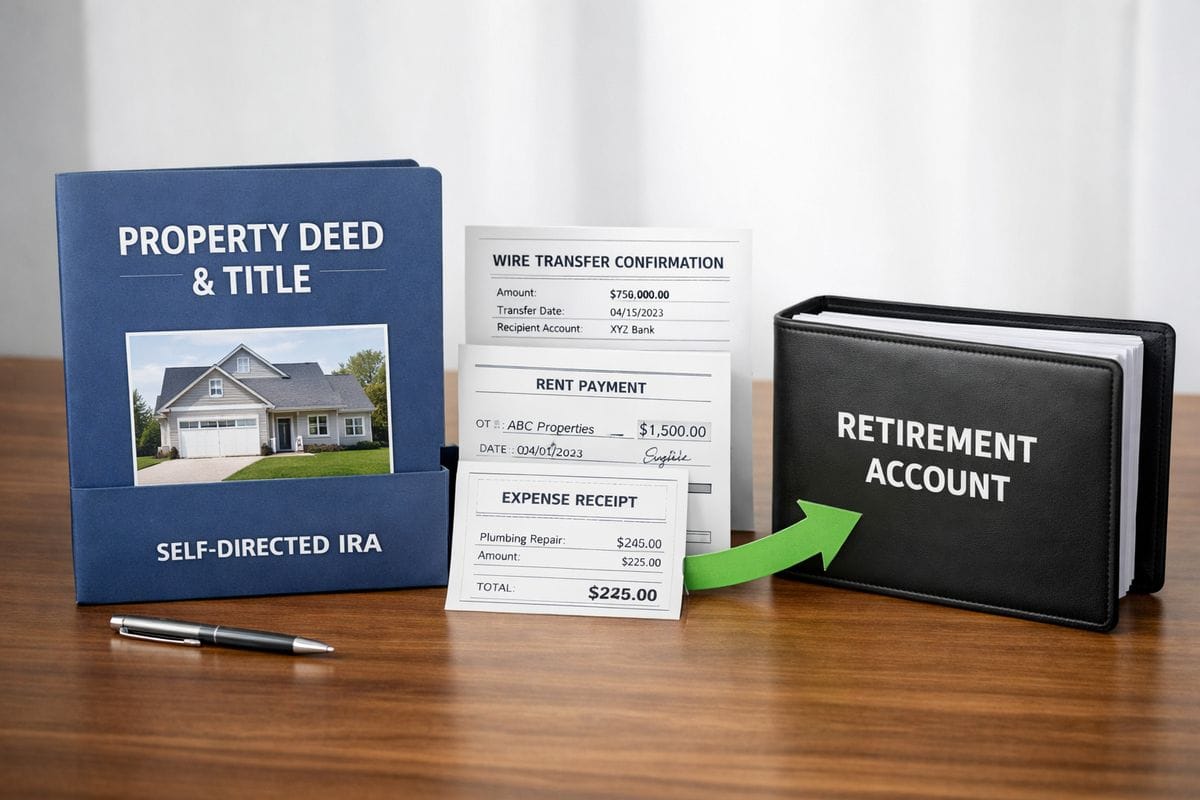
More precisely, title is held by the IRA or by the custodian for the benefit of your IRA. That ownership rule drives almost every compliance requirement that follows. If the IRA owns the asset, your personal checkbook cannot pay a repair bill. Your personal bank account cannot collect rent. Your family cannot stay there for a weekend. Your labor cannot improve the property.
This is where many investors get tripped up. The property feels like yours because you sourced it, underwrote it, and approved it. Legally and tax-wise, it belongs to the retirement account.
How Money Moves In and Out of the Account
Funding an SDIRA happens through contributions, transfers from another IRA, or rollovers from eligible retirement plans. Annual contribution limits still apply to contributions. For 2025, the IRA contribution limit is $7,000, with a $1,000 catch-up if you are age 50 or older. For 2026, the limit rises to $7,500, with a $1,100 catch-up. Transfers and rollovers do not count toward those annual limits.
That difference matters. If you want to buy a $180,000 rental and you are thinking only in terms of annual contributions, the math does not work. Most real estate SDIRAs are funded by moving existing retirement money, not by drip-feeding new contributions over many years.
Once funded, all deal-related money has to stay inside the account flow. Earnest money comes from the IRA. Closing funds come from the IRA. Rent returns to the IRA. Sale proceeds return to the IRA. Clean chain of funds, every time.
The Four Main Ways to Invest in Real Estate Through an SDIRA
Not every real estate strategy belongs inside an SDIRA. Based on analysis of how these accounts perform in practice, three approaches tend to fit well: long-term rentals in a Roth SDIRA, private lending secured by real estate, and raw land in growth corridors. Two approaches create far more friction than value: active flipping and highly leveraged buy-and-hold. The structures below explain why.
Direct Ownership of Rental or Commercial Property
An SDIRA can directly own single-family rentals, multifamily property, commercial buildings, and raw land. Direct ownership fits best when the plan is simple, cash reserves are strong, and the hold period is long enough for the IRA’s tax treatment to matter.
This is especially attractive in a Roth SDIRA. If a Roth SDIRA buys a rental for $220,000, collects net rent for years, and sells for $380,000 later, the qualified withdrawal treatment can turn that appreciation and income into tax-free retirement money. That is one of the strongest use cases in the entire SDIRA category.
The catch is operational friction. The IRA needs enough cash for taxes, insurance, repairs, vacancies, HOA dues, and legal bills. If the roof fails and the IRA is short $11,000, you cannot swipe a personal card and sort it out later. A direct-ownership strategy lives or dies on reserves.
Real Estate Notes, Private Lending, and Debt-Based Deals
This is one of the best SDIRA strategies and one of the least discussed. Instead of owning property, your IRA can make a loan secured by real estate and collect interest. That turns your IRA into the lender.
For example, your SDIRA lends $100,000 at 11% interest on a 12-month first-lien rehab loan. The borrower makes payments to the IRA, and that interest income stays inside the account. You avoid tenants, toilets, and management calls. You also avoid many of the operational headaches tied to direct ownership.
Debt-based deals fit investors who underwrite collateral and borrowers well but do not want active property management inside a retirement account. Based on field observation, this structure often delivers better time-to-value than direct ownership because administration is cleaner and prohibited-transaction risk is easier to control.
Syndications, Funds, and Crowdfunding Deals
An SDIRA can buy into syndications, private funds, and certain crowdfunding offerings. This is the passive version of SDIRA real estate. You commit capital through the IRA, the sponsor operates the deal, and distributions return to the IRA.
That structure works well if you want real estate exposure without managing assets directly. It also works if your retirement money is too small for direct ownership but large enough for a private placement minimum.
But there is no shortcut around process. Capital calls must be funded by the IRA. Distributions must flow back to the IRA. Fees must be paid through the IRA. If the sponsor sends a document for a personal signature or requests a wire from your personal account, the deal needs review before anything moves.
Rehab or Flip Projects Inside an IRA
Yes, an SDIRA can invest in rehab or flip projects. No, it is not a good fit for most investors.
Here is why. You cannot do the work yourself. You cannot personally guarantee financing. You cannot float costs out of pocket. If the project runs over budget, the IRA needs the cash. If the project pace starts to look like an active business instead of investing, UBTI exposure becomes a real problem. That tax drag undercuts the entire reason for using the IRA.
For most operators, flip projects belong outside the SDIRA. The compliance burden is too high, the margin for error is too thin, and the value of your own labor is locked out.
The Three Tax Benefits That Drive SDIRA Demand
The tax story is real, but it only works if the structure matches the strategy. Tax treatment does not rescue a bad deal, poor reserves, or sloppy compliance.
Tax-Deferred Growth in a Traditional SDIRA
In a traditional SDIRA, rental income, note interest, and gains generally stay inside the account without current tax in the normal course. That means your account compounds without annual tax leakage on every profitable event.
The distinction that matters is account-level treatment versus property-level economics. A bad rental is still a bad rental. Deferred tax treatment does not fix weak rent growth, high turnover, or expensive maintenance. But for a solid long-hold asset, deferring tax can materially improve compounded returns over time.
Tax-Free Qualified Withdrawals in a Roth SDIRA
The Roth version is often the strongest fit for real estate. You fund the account with after-tax dollars or converted funds, and qualified withdrawals are tax-free. For long-hold appreciation plays, that is powerful.
If a Roth SDIRA buys raw land in the path of development for $90,000 and sells it 12 years later for $260,000, the gain stays inside the Roth structure. If a Roth SDIRA owns a rental that throws off steady cash flow for a decade, that income compounds inside the account as well. Based on analysis of common SDIRA use cases, Roth long-hold real estate is where the structure earns its keep.
Diversification and Control as Portfolio Outcomes
Tax treatment gets attention, but diversification and control drive a lot of actual decisions. You reduce dependence on stock-market swings and allocate retirement capital into local assets you can analyze directly.
That matters in Texas especially, where investors often have better insight into neighborhood-level demand, suburban expansion, property taxes, insurance pressures, and development paths than into public-company earnings. If your skill set is property underwriting, an SDIRA lets retirement capital follow your real edge.
The Rules That Matter Most: Ownership, Expenses, and Personal Benefit
This is the section that protects ROI. Based on SERP patterns and field data, most SDIRA losses come from rule violations, not from cap rate errors.
All Income Must Return to the IRA
If an SDIRA-owned rental collects $2,100 per month, that rent goes to the IRA, not to your personal account. Same rule for note payments, option fees, and sale proceeds.
Simple example: your IRA owns a rental in Fort Worth. The tenant pays rent on the first of the month. That payment must be deposited into the IRA or into an account controlled by the IRA structure. If it lands in your personal checking account, even briefly, you have created a compliance problem.
All Expenses Must Be Paid by the IRA
Property taxes, insurance, repairs, HOA dues, legal fees, closing costs, and management fees all have to be paid by the IRA. No exceptions because the bill is small. No exceptions because the plumber needed payment that day.
That rule is why reserve planning matters so much. An SDIRA with $6,000 left after closing is fragile. One HVAC replacement can force a bad decision. The recommendation is simple: keep meaningful cash inside the account or avoid direct ownership entirely.
No Personal Use, No Sweat Equity, No Side Benefits
You cannot live in the property, vacation there, let family use it, store equipment there, or perform unpaid labor on it. If the asset is a short-term rental, you cannot block a weekend for yourself. If it is a flip, you cannot paint it on Saturday. If it is raw land, you cannot park a trailer there or use it for hunting.
Present-day benefit is the line you cannot cross. The IRA is for retirement investing, not mixed-use convenience.
Prohibited Transactions and Disqualified Persons, Explained Clearly
This is the central risk in sdira real estate investing. A prohibited transaction is not a minor paperwork issue. It is the event that can disqualify the entire IRA.
Who Counts as a Disqualified Person
Disqualified persons include you, your spouse, your parents, grandparents, children, grandchildren, and entities controlled by those parties. Siblings are treated differently from lineal family members under the rules, but that is not a green light to improvise. Verification before acting is the only safe approach.
The practical test is simple: if the deal moves value between your IRA and a close related party, stop and review it before any contract is signed.
The Most Common SDIRA Real Estate Mistakes
The mistakes are predictable. Buying a property from your father. Renting an SDIRA-owned condo to your daughter. Paying a $480 repair bill personally. Personally guaranteeing the mortgage. Doing your own rehab labor. Using the property for a weekend. These are not edge cases. These are the exact errors that blow up accounts.
The data shows most failures come from ordinary investor behavior carried into the wrong account type. Real estate investors are used to solving problems with speed and personal money. In an SDIRA, that habit is dangerous.
What Happens If a Prohibited Transaction Occurs
If a prohibited transaction occurs, the IRA can lose its tax-advantaged status. That can trigger ordinary income tax on the account value and, if you are under age 59½, a 10% early distribution penalty.
That consequence is severe enough to change how you should evaluate every deal. Pre-transaction review is not optional caution. It is protection against account-level failure.
Can an SDIRA Use Financing?
Yes, but financing is where many investors overestimate the upside and underestimate the tax drag.
Non-Recourse Loans: The Only Loan Structure That Fits
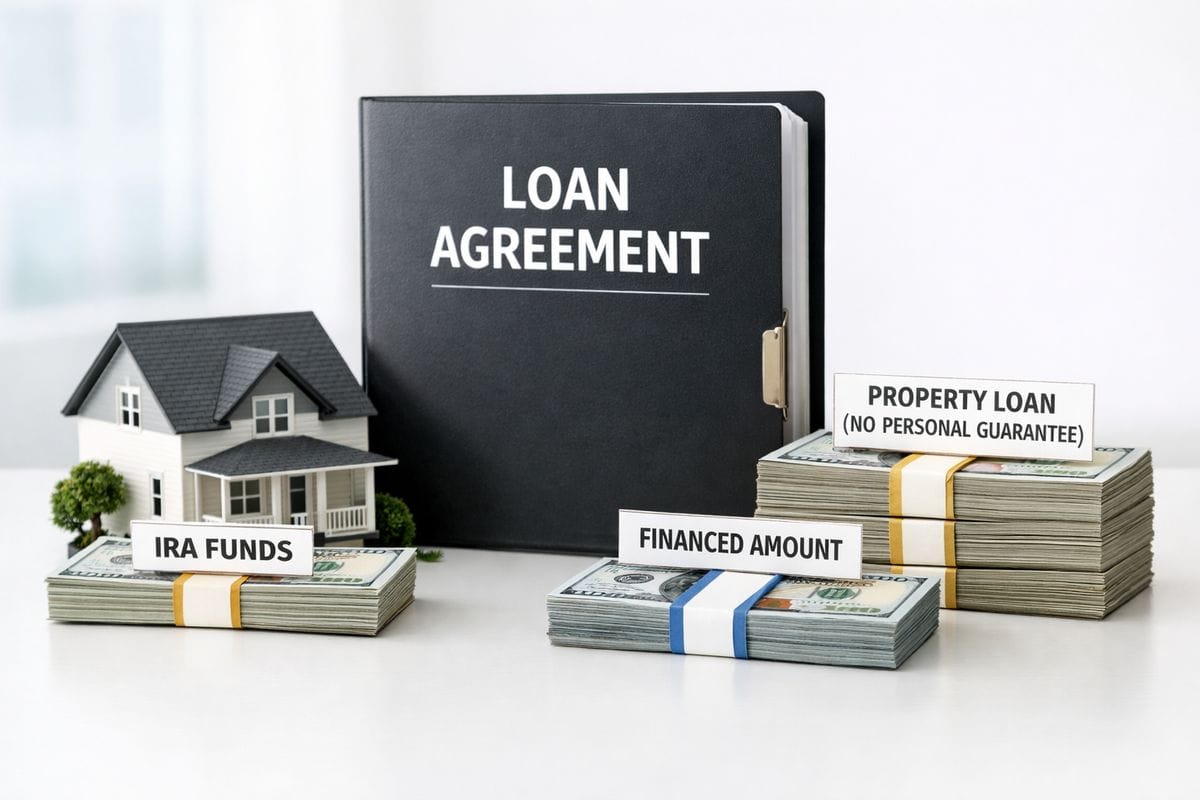
An SDIRA can use non-recourse financing. That means the lender’s remedy is limited to the property itself, not to your personal assets. Personal guarantees are not allowed. If the loan requires your credit support, it does not fit the IRA rules.
Non-recourse loans also tend to be less favorable than conventional investor loans. Higher down payments, higher rates, and narrower underwriting are normal. That slows deals and compresses returns.
UDFI and UBTI: Why Debt Can Trigger Current Tax
Debt inside an IRA can create unrelated debt-financed income, often discussed alongside UBTI. In plain English, the debt-financed share of income or gain can become taxable inside the IRA even though the account is generally tax-advantaged.
Take a simple example. Your SDIRA buys a property for $200,000 using $100,000 of IRA cash and a $100,000 non-recourse loan. Half the deal is debt-financed. If the property later generates $20,000 of net income, the debt-financed portion can create current tax exposure. If the property sells for a gain, the financed portion of the gain can also be affected. Suddenly the headline tax advantage is smaller than expected.
That is why highly leveraged buy-and-hold is one of the weaker SDIRA strategies. Financing expands buying power, but the tax complexity and underwriting limits often reduce actual ROI.
How to Buy and Manage Property Inside an SDIRA
The process matters as much as the asset. Clean execution is part of the return.
Phase 1: Open the Account and Fund It
Start with a custodian that actually supports the asset type and structure you plan to use. Not every SDIRA custodian handles every form of real estate deal, especially LLC setups, notes, or certain private placements.
Then fund the account through contributions, transfers, or rollovers. Most real estate purchases depend on transfers or rollovers because annual contribution limits are too low to capitalize a deal meaningfully.
Phase 2: Run Due Diligence Before the Offer
Underwrite harder than you would outside an IRA. That is the recommendation. Review rent estimates, taxes, insurance, reserves, property condition, foreclosure trends, and neighborhood demand before you write the offer.
Market data helps. ZIP-code foreclosure data updated monthly, single-family rental reports updated annually, and address-level property reports updated monthly can sharpen the decision. One market-data source referenced more than 1 million foreclosure listings nationwide, which shows how broad the opportunity set can be if you screen it properly. But opportunity is not enough. The IRA needs liquidity for surprises.
Phase 3: Execute the Purchase Through the Custodian
Offer language, title, earnest money, and closing instructions all need to match IRA ownership. Earnest money comes from the IRA, not your personal account. The custodian reviews documents. Closing funds are released through the approved process.
This is where YouTube optimism usually dies. Custodian timelines are real. Document corrections are common. Fast-closing sellers often hate this structure. If your entire acquisition model depends on same-day pivots, an SDIRA is the wrong vehicle.
Phase 4: Operate the Asset Without Breaking the Rules
After closing, property management can be outsourced, rents collected for the IRA, and expenses approved through the account. Maintenance can be handled by third parties. Sales can be executed through the same titled structure.
Your role has to stay inside the compliance lane. Oversight is fine. Self-dealing is not. Unpaid labor is not. Personal convenience is not.
Advantages and Tradeoffs of SDIRA Real Estate Investing
This strategy is neither a loophole nor a magic trick. It is a specialized tool.
The Main Advantages
The upside is real when the structure matches the strategy. You get favorable tax treatment, diversification into a familiar asset class, and direct control over investment selection. If your strength is underwriting local rentals, structuring hard money loans, or buying land ahead of development, an SDIRA lets retirement capital work in the same arena as your expertise.
This tends to fit experienced investors best. The more disciplined your underwriting and process, the more usable the structure becomes.
The Real Tradeoffs
Liquidity is limited. Custodian fees are real. Transaction timelines are slower. Funding and title formalities are unforgiving. Financing options are narrower. Leverage can trigger current tax. Errors carry severe penalties.
And honestly, this is the part most promotional content hides: SDIRA real estate is harder than it looks. The friction is not accidental. It is built into the account structure.
When SDIRA Real Estate Investing Makes Sense, and When It Does Not
Fit matters more than enthusiasm.
Best-Fit Investor Profiles
Strong-fit cases are easy to spot. You have idle retirement funds, strong underwriting skill, patience for process, and enough reserves to operate without touching personal money.
Buy-and-hold investors fit well when using a Roth SDIRA for long-term appreciation and income. Passive investors fit well in syndications if the sponsor is organized and the capital-call risk is manageable. Private lenders fit well when collateral analysis is strong and the goal is interest income without management burden. Raw-land investors fit well when the thesis is long-term appreciation in a path-of-growth market.
Poor-Fit Situations
Poor fits are just as clear. You want personal-use flexibility. You depend on fast closings with no custodian review. Your IRA lacks reserves. Your edge depends on doing your own rehab work. Your strategy needs heavy leverage to pencil.
Those cases do not belong in an SDIRA. Active flipping and highly leveraged buy-and-hold sit at the top of the avoid list for exactly that reason.
Frequently Asked Questions About SDIRA Real Estate Investing
Can an SDIRA Buy a Rental Property in Texas?
Yes. Your SDIRA can buy a rental property in Texas as long as the IRA owns it, the transaction avoids disqualified persons, and all income and expenses stay inside the IRA. Texas-specific costs such as property taxes, insurance, and repairs still have to be paid by the IRA, which makes reserve planning especially important.
Can an SDIRA Own an Airbnb or Short-Term Rental?
Yes, but there can be no personal use and no disqualified-person use. That is where many short-term rental investors fail. If you want an Airbnb you can occasionally use, an SDIRA is the wrong structure.
Can an SDIRA Build a House or Fund Renovations?
Yes. Construction and renovation can happen inside an SDIRA if all costs are paid by the IRA and your personal labor is excluded. The operational risk is high because draw schedules, overruns, and vendor payments all have to stay inside the IRA process.
Is an LLC Required for SDIRA Real Estate?
No. An LLC is optional, not mandatory. Some investors use an IRA LLC for checkbook control, but that adds setup cost and raises the compliance standard. If your process discipline is weak, more control makes the account less safe, not more effective.
What Is the Recommendation Before Moving Forward?
Pre-screen the deal structure with your SDIRA custodian, a real estate tax advisor, and legal counsel before any contract is signed or funds move. The data shows compliance review protects ROI more than squeezing out slightly better purchase terms. In this category, avoiding one prohibited transaction is worth more than winning a small price concession at closing.