
Real estate professional status irs requirements decide whether rental losses reduce current tax or sit suspended for years. That makes this a timing and cash-flow issue, not just a technical tax election. Under IRC §469(c)(7), real estate professional status is an exception to the passive loss rules for rental real estate, but it works only if two separate hurdles are cleared: qualifying as a real estate professional and materially participating in the rental activity.
This guide covers the rules that actually control the outcome, the records that survive audit, the mistakes that lose in Tax Court, and the planning moves that matter before 2026 and 2027 tax changes narrow the value of missed deductions.
What you will learn:
- The exact REPS qualification tests
- Why REPS alone does not free losses
- Which hours count and which fail
- How grouping elections change the result
- What records survive IRS scrutiny
- Why W-2 investors usually lose
- How REPS interacts with cost segregation
- What changes in 2026 to 2027, and what does not
Why Real Estate Professional Status Matters Before 2026, 2027
Real estate professional status determines whether suspended rental losses stay trapped as passive losses or offset wages, business income, and other non-passive income now. If your portfolio generates depreciation-driven losses, this single classification changes current-year tax liability, after-tax cash flow, and return on invested capital.
The urgency is higher right now because several planning windows are narrowing at the same time. Bonus depreciation has already been phasing down. Individual tax rates and the qualified business income framework face pressure as Tax Cuts and Jobs Act provisions approach sunset. Estate and gift exemption levels also face scheduled compression if Congress does nothing. REPS itself is not a temporary TCJA rule, but the value of getting losses into the right year becomes much more significant when tax rates, depreciation timing, and deduction structures are moving.
That is the business stake. If losses are suspended, cost segregation studies and accelerated depreciation produce paper deductions without current cash-tax value. If losses are non-passive, those same deductions can reduce tax now, which changes acquisition math, debt coverage, hold strategy, and disposition timing.
The recommendation is straightforward: evaluate REPS as a year-round operating position, not as a return-prep idea raised in March. By filing season, the result is usually already baked in.
The Core Rule: REPS Is an Exception to Passive Loss Limits
Real estate investors often treat REPS as a status that automatically unlocks rental losses. That is wrong. Rental real estate is generally passive by default, and REPS is only the first exception layer.
Under IRS Publication 925, a taxpayer qualifies as a real estate professional only by meeting both statutory tests under IRC §469(c)(7). Even after meeting those tests, rental losses become non-passive only for rental activities in which material participation exists. That two-step structure controls everything.
The Passive Activity Baseline Under IRC §469
IRC §469 limits passive activity losses. In plain English, passive losses generally offset only passive income. Rental real estate falls into the passive bucket by default, which is why so many investors see large Schedule E losses that do not reduce wages or business profit in the current year.
Those unused losses are not gone. They are suspended and carried forward. In a future year, suspended passive losses can offset passive income from the same or other passive activities, and in certain disposition events they can be released. But carrying losses forward is a timing problem. A deduction five years later is worth less than a deduction now.
This is where many portfolios quietly lose efficiency. The depreciation exists. The tax value does not arrive when the capital is actually under pressure.
The Two-Step Structure Most Investors Miss
Step one is qualifying as a real estate professional. Step two is materially participating in the rental activity. Passing step one alone does not free rental losses.
That distinction is repeated in IRS guidance and practitioner analysis because taxpayers keep collapsing the two concepts into one. The statute does not. REPS changes the classification rules for rental real estate, but material participation still determines whether the activity is passive or non-passive in the year at issue.
If your hours qualify you for REPS but your rentals are handled mostly by a property manager, losses can remain passive. If your rentals are intensely self-managed but your outside job consumes more total work time than real estate, REPS fails and the losses remain passive. Both gates matter.
Where the $25,000 Special Allowance Fits
The separate $25,000 rental real estate special allowance sits in a different lane. It applies to taxpayers who actively participate in rental real estate and fall within income limits. The allowance phases out as modified adjusted gross income rises and disappears at higher income levels.
For many W-2 earners, that rule becomes irrelevant fast. At $100,000 of modified adjusted gross income, the allowance starts phasing out. At $150,000, it is fully gone. Higher-income investors therefore cannot rely on this rule as a substitute for REPS.
The point is simple: active participation and the $25,000 allowance are not the same as real estate professional status. If your income is above the phaseout range, REPS is the only major path for using rental losses against non-passive income before a future disposition.
The Two Qualification Tests Under IRC §469(c)(7)
The statute uses two annual tests. Both must be satisfied in the same tax year. Time allocation drives the result, and the math is stricter than most investors expect.
The More-Than-50% Personal Services Test
More than half of all personal services performed in trades or businesses during the year must be performed in real property trades or businesses in which material participation exists. The key phrase is more than half of all personal services.
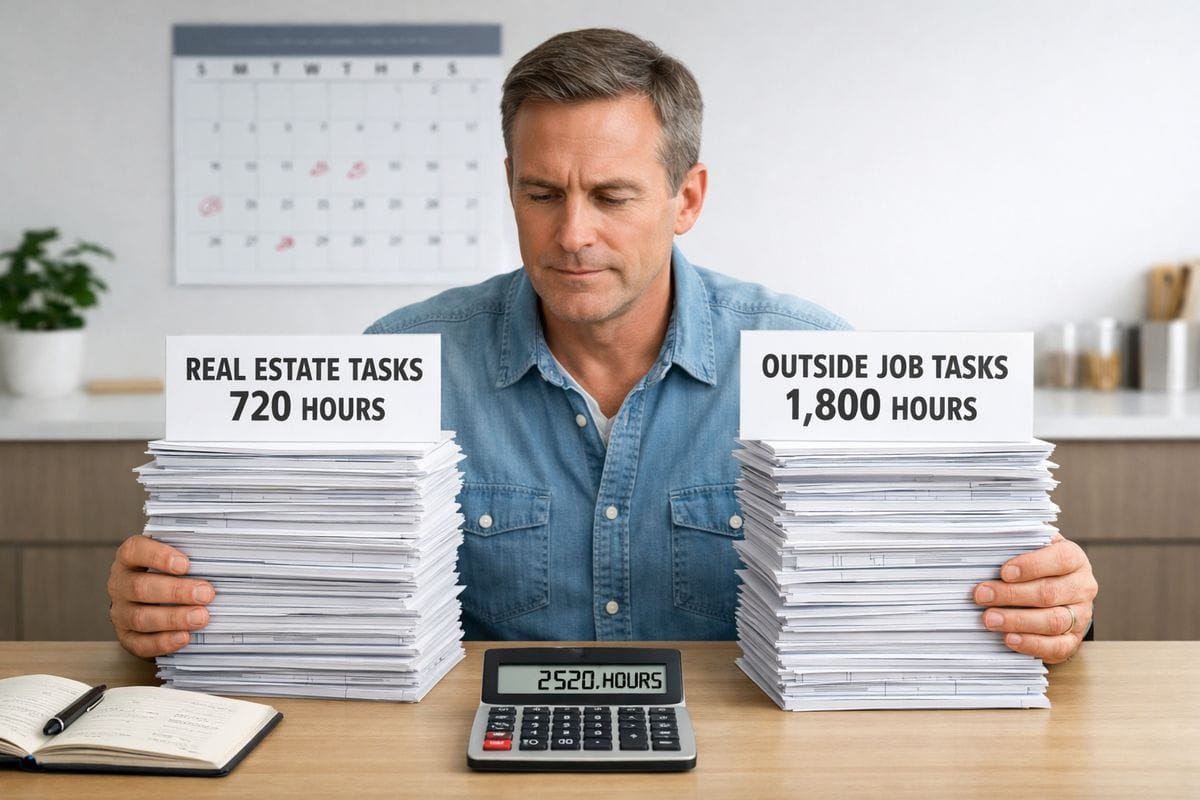
This is the test that usually destroys REPS claims for anyone with a full-time non-real-estate job. If your W-2 job consumes 2,000 hours, your real estate time must exceed 2,000 hours to pass the more-than-50% test. Hitting 750 hours is nowhere near enough.
The IRS states that both conditions are required, not one or the other. A taxpayer with 900 real estate hours and 1,200 consulting hours fails. A taxpayer with 760 real estate hours and 700 non-real-estate hours passes this prong, assuming the real estate services are in qualifying real property trades or businesses with material participation.
Another trap: employee services generally do not count toward the REPS tests unless you are a more-than-5% owner of the employer. If you work in real estate as an employee but do not own enough of the employer, those employee hours can be excluded for REPS qualification. That rule surprises a lot of licensed agents and salaried real estate staff.
The 750-Hour Test
You must perform more than 750 hours of services during the tax year in real property trades or businesses in which material participation exists. The threshold is annual and absolute. Hours do not carry over from prior years.
Treat 750 hours as the floor, not the finish line. A taxpayer with 751 hours still fails if non-real-estate work totals 900 hours. A taxpayer with 1,100 hours still fails if too many of those hours are investor-type tasks that do not count.
The cleanest way to think about this test is operationally: you need real, documentable, service-based time spent doing actual business functions in qualifying real property trades or businesses. Ownership is irrelevant. Intent is irrelevant. Claimed effort without records is usually worthless under audit.
Both Tests Apply Every Tax Year
REPS is tested every year. It is not an election that, once achieved, stays in place for life. A year with reduced hours, a maternity or paternity leave period, a new W-2 role, retirement, a major acquisition, or a sale of a time-intensive property can change the result immediately.
That annual testing changes planning. If one year includes a heavy rehab and direct management, qualification may be straightforward. If the next year shifts to stabilized assets under third-party management, the same taxpayer can fail. If retirement reduces non-real-estate work hours, REPS may become much easier in a later year.
This year-by-year structure is why annual logs matter so much. The IRS asks what happened in the tax year under examination, not what usually happens in your business.
What Counts as a Real Property Trade or Business
The statute defines real property trades or businesses broadly, but not infinitely. The broad list helps taxpayers. The limits still matter because investors routinely overcount nonqualifying owner activity.
The 11 Real Property Trades or Businesses
The IRS defines a real property trade or business to include development, redevelopment, construction, reconstruction, acquisition, conversion, rental, operation, management, leasing, and brokerage. Those 11 categories are the starting point for determining whether time belongs in the REPS bucket.
Development includes moving a project from raw or underused property toward productive use. Redevelopment covers repositioning or major improvement of existing property. Construction and reconstruction include building and substantial rebuilding work. Acquisition means work tied to obtaining real property, though pure investment scouting still creates trouble if the activity is really deal hunting rather than operating a business. Conversion includes changing property use, such as office to multifamily or short-term rental to long-term use.
Rental, operation, management, and leasing are the categories most rental owners rely on. These include tenant communications, showings, lease negotiation, maintenance coordination, rent collection, bookkeeping tied to operations, turnover work, and direct oversight of contractors. Brokerage applies when licensed brokerage activity is part of your work.
Hours across multiple qualifying real property trades or businesses can be aggregated for the 750-hour and more-than-50% tests if material participation exists in those businesses. That matters for taxpayers who combine brokerage, development, and rentals.
Rental Activities Versus Investor Activities
The line between business activity and investor activity is where many REPS claims collapse. Reviewing financial statements, analyzing market trends, discussing tax projections with an accountant, arranging financing, studying neighborhoods for future purchases, and monitoring a property manager at a distance often look like work. For REPS, much of that time fails.
Why? Because those tasks often reflect ownership, capital allocation, and investment oversight, not personal services in a real property trade or business. Courts and examiners focus on whether your actions directly affect day-to-day operations, leasing, management, construction, or another qualifying business function.
That is why searching for new deals is usually weak support. Buying property is listed in the statute as acquisition, but generalized market research and capital deployment decisions often resemble investor conduct more than business operations. The closer the task is to actual execution on a real property business, the stronger the hour.
Business Activities That Strengthen a REPS Position
Certain fact patterns make a REPS position much more defensible. Direct leasing activity is strong because it is operational and property-specific. In-house management is strong because it shows personal involvement in daily business functions. Tenant screening, rent collection, repair dispatch, turnover management, and vendor scheduling all support both REPS hours and material participation.
Rehab oversight can be strong when it involves actual supervision, site decisions, scope management, contractor direction, inspection follow-up, and property-level execution. Operating a separate real estate business, such as brokerage, management, development, or construction, also strengthens the case because it creates a larger base of qualifying hours and shows a real-estate-centered workload.
Based on analysis of audit disputes, the strongest REPS files look like operating businesses. The weakest files look like ownership with commentary.
Material Participation: The Second Gate to Non-Passive Losses
REPS alone is not enough. Material participation decides whether the rental activity itself is non-passive. If this second gate is missed, the losses stay passive.
Why Material Participation Is Separate From REPS Qualification
Hours used to qualify as a real estate professional are measured across real property trades or businesses in which material participation exists. But for rental losses to become non-passive, material participation must exist in the rental activity itself.
That sounds circular because the concepts overlap, but the legal structure is different. REPS answers whether rental real estate can escape the default passive rule. Material participation answers whether your involvement in the specific activity is regular, substantial, and direct enough to treat it as non-passive.
This is exactly why a taxpayer can qualify for REPS through a mix of brokerage and development hours yet still fail to free losses from a lightly managed rental portfolio.
The Seven Material Participation Tests
Treas. Reg. §1.469-5T provides seven tests. Rental owners usually rely on a small subset of them. The most defensible route is the one that leaves the least room for argument.
The 500-Hour Test
The 500-hour test is the cleanest path. If you participate in the activity for more than 500 hours during the year, material participation is established.
For rentals, this test works best when you have a grouped activity or a single time-intensive portfolio that you manage directly. It is simple, quantifiable, and easier to defend than narrative tests.
If your records show 540 documented hours across grouped long-term rentals, tied to tasks, dates, emails, invoices, and mileage, this is a strong litigation posture. If your file depends on broad estimates and unsupported categories, even 900 claimed hours can fail.
Substantially All Participation
You materially participate if your participation constitutes substantially all participation in the activity by all individuals, including nonowners. This test works when you are doing nearly everything yourself.
The catch is obvious. Contractors, handymen, leasing agents, maintenance staff, and property managers can break this test quickly. If paid third parties perform a meaningful share of activity hours, claiming substantially all participation becomes difficult to defend.
For self-managed single-family portfolios with limited outside help, this route can still work. For professionally managed assets, it usually does not.
More Than 100 Hours and More Than Anyone Else
You materially participate if you participate for more than 100 hours and no other individual participates more than you. This is a common rental test because some portfolios do not reach 500 owner hours.
The problem is third-party management. If a property manager logs more hours than you, this test fails. If on-site labor, contractors, or a resident manager collectively dominate the activity, proof becomes messy. The IRS often asks for management agreements, labor invoices, and vendor records for exactly this reason.
This test also requires property-level discipline. Without a grouping election, you need this result for each separate rental activity.
Prior-Year Participation Tests
Two prior-year tests exist, but rental owners often overestimate their usefulness. One test applies if you materially participated in the activity for any five of the preceding ten tax years. Another applies to personal service activities for three prior years, which usually has narrower relevance for rentals.
The five-of-ten-years rule can help taxpayers with long-running, hands-on ownership history, especially where current-year hours dip but prior involvement is strong. Still, it does not save a bad documentation file if the IRS disputes the history.
Facts-and-Circumstances Test
The facts-and-circumstances test is the weakest litigation position for most rental taxpayers. It requires regular, continuous, and substantial participation, and it invites argument over qualitative facts rather than clean numerical proof.
This route is especially weak when paid management exists. If a property manager handles daily operations, the case for regular, continuous, and substantial owner participation gets thin fast. Courts want specifics, not a story.
If this is your only path, your records need to be unusually strong: detailed logs, correspondence trails, decision records, site visit support, contractor directions, and evidence that your services actually drove operations.
Grouping Elections: When One Activity Beats Separate Properties
A grouping election often decides the outcome for taxpayers with multiple rentals. Without it, fragmented time across several properties can create repeated material participation failures even when total portfolio involvement is substantial.
The Default Rule: Each Property Stands Alone
The default rule treats each rental real estate interest as a separate activity. That means material participation is tested separately unless a valid grouping election is in place.
This is where many investors lose without realizing it. You may spend 420 hours across six rentals, but if no single property reaches a material participation test, losses remain passive. Time spread across properties is not enough by itself under the default rule.
For portfolios with small but frequent tasks across many units, separate testing is a structural disadvantage.
The Election to Group All Rental Real Estate Interests
IRC §469(c)(7)(A) and the regulations allow a qualifying taxpayer to elect to treat all interests in rental real estate as one activity. The grouping election is made by attaching the required statement to the return, and it generally remains binding for future years absent a qualifying change and proper revocation procedures.
This election changes the material participation analysis dramatically. Instead of proving participation property by property, you prove it for the grouped rental activity as a whole. For investors with multiple long-term rentals, this is often the difference between pass and fail.
Late election relief has existed in certain circumstances, but counting on cleanup later is poor planning. The recommendation is to address grouping prospectively and deliberately.
Advantages, Tradeoffs, and Exit Consequences
The main advantage is operational simplicity. Grouping aggregates hours, supports the 500-hour test more easily, and aligns with how many investors actually manage portfolios, as one business rather than isolated silos.
The tradeoff is future disposition planning. Grouping can affect how gain, suspended losses, and partial asset sales are treated because the activity is no longer viewed property by property for every purpose. If your strategy depends on selling one asset and releasing losses tied only to that asset, grouping changes the analysis.
That does not make grouping bad. It means grouping is a strategic choice, not a reflex. For most rental owners pursuing REPS, the audit defensibility benefit outweighs the downside.
When Grouping Is a Strong Recommendation
The recommendation is clear when you own several long-term rentals, your time is spread across units, and your goal is to defend material participation with a coherent annual log. Grouping is also strong when no single property produces enough owner hours but the portfolio does.
It is less attractive when each property is already intensely managed on its own, when planned dispositions make separate activity treatment more valuable, or when nonrental real estate businesses drive REPS qualification while rental participation remains minimal.
For many portfolios, however, grouping is the practical answer to the way real management time is actually spent.
What Hours Count for REPS and What Hours the IRS Rejects
This is the operating center of the entire REPS issue. The IRS does not reward effort in the abstract. It counts personal services in qualifying real property trades or businesses and rejects owner-level activities that do not directly affect operations.
Hours That Usually Count
Hours usually count when they reflect direct operational work tied to a specific property or real estate business. Examples include tenant communications, leasing calls, screenings, showings, rent collection, deposit follow-up, repair coordination, ordering supplies, scheduling vendors, supervising contractors, turnover management, bookkeeping tied to property operations, on-site inspections connected to management, and rehab oversight.
Driving to properties can count when the travel is tied to active management tasks, such as inspections, showings, contractor meetings, lease signings, or repair oversight. Property inspections count when they are real operating tasks, not scenic drive-bys intended to inflate hours.
A practical documentation template should track four data points for every entry:
| Date | Activity performed | Hours spent | Property address |
|---|---|---|---|
| 01/04/2026 | Tenant screening and lease review | 1.4 | 123 Main St, Dallas, TX |
| 01/04/2026 | Coordinated plumbing repair, vendor calls | 0.8 | 456 Oak Ave, Dallas, TX |
| 01/05/2026 | Drove to property, inspection, photo log | 1.2 | 123 Main St, Dallas, TX |
| 01/06/2026 | Supervised flooring contractor turnover work | 2.3 | 789 Pine Rd, Plano, TX |
That structure works because it answers the audit questions that matter: what was done, when, for how long, and at which property.
Activities that generally count include:
- Property inspections
- Tenant screening
- Coordinating repairs
- Negotiating leases
- Supervising contractors
- Driving to properties
- Rent collection
- Turnover management
- Site meetings
- Operations bookkeeping
Hours That Often Do Not Count
Some activities feel like work because they consume time, but they often fail under examination. Reviewing financial statements, talking to advisors, searching for new deals, attending education seminars, generalized planning, macro market research, arranging financing, capital raising, and passively reviewing management reports are common examples.
These are the hours investors use to pad thin files. Examiners know it, and courts have repeatedly rejected it. If the activity is mainly ownership oversight or investment analysis, it is weak support for REPS.
Activities that generally do not count include:
- Reviewing financial statements
- Talking to advisors
- Searching for new deals
- Education and seminars
- General market research
- Passive owner oversight
- Capital raising
- Loan shopping
The recommendation is to classify these separately in your system from day one. Do not mix noncounting hours into operating logs and hope to sort it out later.
Travel Time Rules
Travel time is supportable when it is tied directly to active management, leasing, construction, or operations. Commuting from home to a regular office is not. Inflated long-distance travel claims also attract scrutiny fast, especially if the property is out of state and local management exists.
If travel is claimed, the log should show destination, purpose, duration, and the operational task performed on arrival. Mileage records, calendar entries, and emails should corroborate the trip. A two-hour drive to inspect a turnover, meet a contractor, and approve scope changes is much stronger than three hours labeled simply as “property travel.”
Excessive travel claims sink credibility because they often create impossible annual schedules. Once credibility breaks, the entire log becomes vulnerable.
Time Spent Managing Managers and Contractors
This area is nuanced, but the line is still clear. Active supervision counts. Passive oversight does not.
If you direct vendor scope, review bids, approve repair methods, set deadlines, inspect completed work, and handle property-level decisions, that is active supervision. If you receive a monthly report from a manager, glance at it, and occasionally approve invoices, that is owner oversight.
Contractor and manager relationships therefore cut both ways. You can still claim hours while using outside help, but the more day-to-day work is outsourced, the harder it becomes to show that your own services were regular, substantial, and greater than the services of others.
Spouse Hours and Joint Return Misunderstandings
One spouse alone must satisfy the REPS qualification tests. On a joint return, one spouse cannot use the other spouse’s personal services to meet the 750-hour and more-than-50% tests. The IRS states this directly in Publication 925.
Material participation works differently. For determining participation in an activity, spouse participation can be counted together in certain contexts. That distinction creates confusion. The easiest way to keep it straight is this: REPS qualification is spouse-specific, while material participation has broader joint-return interaction.
This matters most for households where one spouse has a full-time non-real-estate job and the other spouse manages rentals. The spouse managing properties must independently satisfy REPS. The working spouse’s hours do not help with that threshold.
Recordkeeping Standards That Survive an IRS Audit
The law does not require a perfect daily stopwatch. But field results show that contemporaneous, specific records drive survival. A year-end spreadsheet built from memory is usually a losing position.
What the IRS and Courts Expect to See
The strongest records combine a time log with external proof. That includes calendars, appointment books, emails, text messages, mileage logs, vendor invoices, lease files, bank records, project management records, and property management communications.
A defensible record set shows not just total hours, but a believable pattern of work. If your log says you supervised a plumbing repair on March 3, the invoice, text thread, email, or payment record should place that task in the same time frame.
The data shows that logs without support invite attack. Support without a task-by-task log also creates gaps. You need both.
Contemporaneous Logs Versus Reconstructed Estimates
Courts repeatedly reject reconstructed logs built from averages, memory, and generic labels. A monthly estimate like “20 hours property management” is weak. A year-end spreadsheet assigning identical 2.5-hour blocks to random dates is worse.
The problem is credibility. If your records were created after the fact, rounded heavily, or disconnected from external evidence, examiners can treat them as advocacy, not substantiation. Once that happens, deductions are reversed, interest applies, and accuracy-related penalties become real.
Start the time log on January 1. That is the recommendation. Not in December. Not when the CPA asks for support. January 1.
How Detailed Your Records Need to Be
The practical standard is simple: date, property, task, duration, and supporting trail. Start and stop times help, though duration entries are often enough if the description is specific and corroborated elsewhere.
“Worked on rental” is useless. “Met flooring contractor, reviewed hallway damage, approved revised scope, 1.6 hours, 789 Pine Rd” is useful. The entry should let an examiner understand exactly what happened without guessing.
Specificity also prevents accidental overcounting. If the task description is vague, investor hours and operational hours blend together. That creates risk before the IRS even opens the file.
A Defensible Time-Tracking System
The most effective system is boring. That is the point.
Log time weekly, not quarterly. Reconcile monthly against calendar entries, mileage, and documents. Retain digital support in property folders. Total hours annually by property and by activity category. Separate counting categories from noncounting categories. Flag travel separately. Preserve all records for the full tax retention period and longer if significant losses carry forward.
A practical workflow looks like this:
- Record each task within the week performed.
- Assign the task to a property address or real estate business.
- Tag the activity type, leasing, maintenance, management, rehab, travel, bookkeeping.
- Attach or save support, email, invoice, photo, text, mileage.
- Reconcile monthly totals.
- Review annual totals before year-end, not after filing.
That system does more than defend an audit. It tells you in real time whether your filing position is actually supportable.
Audit Risk: How the IRS Challenges REPS Claims
REPS is audit-prone because the tax benefit is large and the proof is fact-intensive. Examiners attack the claim at predictable pressure points.
High-Risk Profiles the Data Shows Repeatedly
Full-time non-real-estate employment is the highest-risk profile because the more-than-50% test becomes mathematically difficult. Out-of-state properties create travel and feasibility questions. Third-party managers weaken both hours and material participation. Sparse, generic records suggest a return position built after the fact.
Other high-risk patterns include elderly or heavily committed taxpayers claiming extremely high hours, owners whose properties appear to run without them, and returns with large cost segregation deductions paired with thin documentation.
The IRS often begins with occupation. W-2s, signatures, LinkedIn profiles, payroll records, and outside business activity all frame the time-allocation analysis immediately.
Common IRS Interview Questions
The typical examination is not mysterious. Expect questions about occupation, weekly schedule, other businesses, commute time, the number of properties, who performed repairs, whether a property manager was used, how tenant issues were handled, what records were kept, and when the logs were prepared.
Expect direct questions about spouse roles if a joint return is involved. Expect requests for calendars, mileage logs, emails, invoices, and management agreements. Expect follow-up on impossible dates or suspiciously uniform hours.
The exam theme is always the same: prove who did what, when, and for how long.
Why Property Managers Change the Analysis
Property managers do not automatically kill REPS, but they materially weaken many claims. If a manager handles leasing, repairs, rent collection, tenant calls, and contractor coordination, your own service hours shrink. Your position under the substantially-all and more-than-100-hours-and-more-than-anyone-else tests also weakens.
Examiners know that paid management often means someone else is doing the work you are trying to count. That is why management agreements, commission statements, labor expenses, and Schedule E entries receive attention during audits.
If you use a manager, your remaining hours must be specific, direct, and meaningful. Passive approval of reports is not enough.
Red Flags in Time Logs
Round-number entries are a classic red flag. So are identical hours repeated week after week, duplicate tasks across multiple properties on the same date, and annual totals that imply impossible schedules.
A log created after the return is prepared is another problem, especially if timestamps, file metadata, or internal inconsistencies reveal the timing. Courts have also reacted badly to logs that include meals, excessive travel, on-call time, and broad categories like “research” or “management.”
A believable log looks messy in a human way. It varies. It ties to reality. It contains short tasks, long tasks, and occasional gaps.
Court Cases That Define the Real Standards
Case law is where abstract rules become real operating standards. The lesson across cases is not subtle: specificity wins, estimates lose, and full-time outside employment creates a steep barrier.
Cases Where Taxpayers Lost on Documentation
Taxpayers lose repeatedly when records are reconstructed from memory, rounded, or unsupported. In Harnett v. Commissioner, reconstructed estimates were rejected because the taxpayer did not maintain a contemporaneous log and could not credibly prove the claimed hours. In Bosque, the taxpayers admitted having no documentation and lost.
In Penley, the Tax Court rejected exaggerated records with rounded entries, weak detail, and unsupported time claims. The court also imposed a negligence penalty. That is the outcome pattern to remember: once documentation fails, the return often loses on both deductions and penalties.
Cases Where Taxpayers Lost on Full-Time Employment Conflicts
Full-time employment outside real estate regularly undermines the more-than-50% test. The math is unforgiving. A taxpayer can spend substantial time in real estate and still fail because real estate was not more than half of total personal service time.
This is where many part-time investors misunderstand the law. The issue is not whether 750 hours sounds like a lot. The issue is whether real estate hours exceed all other business and employment hours combined.
Even an investor with 800 real estate hours fails if another job or consulting practice consumed 850 hours. That is not a gray area. It is a failed statutory test.
Cases Where Taxpayers Won With Specific, Credible Proof
Taxpayers win when facts line up cleanly with the statute and the records are believable. In Miller, detailed work logs, credible testimony, and corroborating evidence supported the claimed hours and operational involvement. That is what success looks like: contemporaneous records, direct services, consistent facts, and no major contradiction from outside employment.
Successful cases usually feature real-estate-centered work patterns, substantial direct activity, and documentary support that extends beyond a single spreadsheet. The file tells a coherent story before testimony begins.
What the Case Law Means for Current Planning
The operating rules from litigation are clear. Keep contemporaneous logs. Exclude investor hours. Treat full-time non-real-estate work as a major obstacle. Use grouping where it improves material participation proof. Do not rely on facts-and-circumstances when a cleaner numerical test is available.
Most important, build the record while the year is happening. Courts reward records that arise from ordinary business behavior. Courts punish records that arise from tax controversy.
Working a Full-Time W-2 Job and Trying to Qualify
This is one of the highest-intent questions because many rental owners want the tax result without changing the workload. The law usually does not allow that.
Why the More-Than-50% Test Is the Main Barrier
A standard full-time W-2 schedule usually blocks REPS because real estate must exceed that time. If your job is roughly 40 hours a week for 50 weeks, that is 2,000 hours. Real estate services must exceed 2,000 hours and also surpass 750. That means nights and weekends are rarely enough.
Based on analysis of audit disputes, this is the main reason W-2 investors lose. The 750-hour threshold gets all the attention, but the more-than-50% test is the real wall.
Scenarios That Fail Fast
A taxpayer with 2,000 W-2 hours, five rentals under third-party management, and 300 documented owner hours fails fast. A taxpayer with a demanding consulting practice and a few weekend property visits also fails fast. A taxpayer who claims high real estate hours but uses a manager for tenant issues, leasing, and repairs starts from a weak position.
The same is true for owners who live far from the rentals and count broad travel time or oversight of reports as participation. Those fact patterns attract immediate scrutiny because the business appears to run without the claimed level of owner service.
Scenarios That Can Still Work
Qualification can still work when outside employment is genuinely limited. Reduced W-2 hours, part-time schedules, seasonal work, sabbaticals, retirement transitions, and a spouse with little or no other employment can produce a valid REPS profile if the real estate workload is real and documented.
A stronger scenario also exists when you operate a real estate-centered side business, such as property management, brokerage, development, or construction, and those hours are substantial, qualifying, and materially participated. But the math still rules. Real estate must be more than half of total personal service time.
Three simple profiles show how the two-prong math works:
Profile 1: Full-time landlord, passes easily
Real estate hours: 1,650
Other business or employment hours: 0
Result: passes the 750-hour test and passes the more-than-50% test because all personal services are in qualifying real estate activity.
Profile 2: Spouse managing properties, passes if no other employment
Spouse real estate hours: 980
Other spouse’s W-2 hours: 2,100
Claiming spouse’s non-real-estate hours: 0
Result: passes if the managing spouse independently satisfies REPS and materially participates in the rentals. The working spouse’s hours do not prevent the managing spouse from qualifying.
Profile 3: Part-time investor with W-2, almost always fails
Real estate hours: 820
W-2 hours: 1,900
Result: fails the more-than-50% test even though 750 hours is met. Losses remain passive unless another exception applies.
Those examples capture the practical reality. REPS is a workload test, not a preference election.
Short-Term Rentals, REPS, and Related Exceptions
Short-term rentals are often discussed alongside REPS because they can produce similar passive loss outcomes through a different path. That overlap causes confusion.
Why Short-Term Rentals Follow Different Activity Rules
When average customer use is short enough under the rental activity regulations, the activity may not be treated as a rental activity for passive loss purposes. That matters because the default rule that rental real estate is passive may not apply in the same way.
If the activity is not treated as a rental activity, material participation becomes the central question without needing REPS in the same way long-term rentals do. This is why short-term rental planning often appears as an alternative strategy for high-income taxpayers seeking current deductions.
The point is not that short-term rentals are easier. The point is that the classification rules differ.
Material Participation in Short-Term Rentals
For a short-term rental activity that is not treated as a rental activity under the regulations, the standard material participation tests apply directly. The 500-hour test is again the cleanest route, though other tests can apply depending on the facts.
This creates opportunity for taxpayers who materially participate heavily in a vacation rental or similar operation, especially when direct management, guest communication, cleaning coordination, pricing, maintenance, and turnover activity generate substantial owner hours.
But the same documentation standards apply. Unsupported owner claims still fail.
REPS Versus the Short-Term Rental Path
If your portfolio is mainly long-term rentals, REPS remains the primary route for converting losses into non-passive losses. If your activity is a qualifying short-term rental business with strong material participation, you may achieve a similar tax result without meeting the REPS tests.
Planning therefore differs. Long-term rental investors focus on annual REPS qualification and often grouping elections. Short-term rental operators focus on the activity classification rules and material participation.
Confusing these paths creates filing errors. Long-term rental owners cannot borrow short-term rental logic just because both strategies involve real estate losses.
Tax Benefits of REPS Beyond Unlocking Rental Losses
Unlocking rental losses is the headline benefit, but not the only one. Still, this is an area where investors often overstate what REPS does.
Using Rental Losses Against W-2 and Business Income
The biggest financial outcome is immediate use of losses against non-passive income. That includes wages, business income, and other ordinary income streams. Accelerated depreciation from cost segregation becomes far more valuable when it offsets current tax rather than sitting suspended.
This is why REPS has such strong ROI for high-income households with active income. A six-figure depreciation deduction that remains passive has deferred value. A six-figure deduction that offsets current ordinary income has immediate cash value.
Suspended Loss Release Strategy
REPS also changes timing strategy. Without REPS, passive losses accumulate and release under narrower rules, often tied to passive income or full disposition. With REPS and material participation, current-year deductions can be used now, which affects acquisition pacing, refinancing choices, and hold-versus-sell decisions.
That timing difference matters at the portfolio level. If suspended losses are building faster than passive income, you are carrying tax assets that do not improve present liquidity. REPS can convert those trapped deductions into current benefit.
NIIT Implications for Rental Income
REPS can also affect the 3.8% Net Investment Income Tax, but this requires precision. The NIIT has its own framework. In some cases, rental income from a business in which material participation exists can fall outside net investment income treatment. Some tax commentary also notes a safe-harbor style path tied to more than 500 hours in the current year or five of the prior ten years for NIIT purposes.
The important point is that REPS helps, but NIIT analysis is not identical to passive loss analysis. You need both frameworks reviewed together if NIIT exposure is material.
What REPS Does Not Change
REPS does not automatically eliminate self-employment tax questions. Rental income generally remains outside self-employment tax, but facts still matter, especially when services become extensive.
REPS does not guarantee qualified business income treatment. It does not turn every real estate activity into earned income. It does not fix weak basis, at-risk, or entity issues. It does not override poor documentation.
In other words, REPS is powerful, but it is narrow. Its value comes from the passive loss rules, not from a wholesale rewrite of all real estate tax treatment.
Cost Segregation, Bonus Depreciation, and Timing Strategy
REPS matters most when paired with deductions large enough to justify the compliance burden. Cost segregation is the usual driver.
Why Cost Segregation Often Pairs With REPS
Cost segregation accelerates depreciation into earlier years by reclassifying components of a property into shorter recovery periods where appropriate. For investors pursuing REPS, this can create large current-year paper losses.
That pairing drives ROI when those losses are non-passive. The same study is much less valuable if the resulting loss stays suspended. This is why cost segregation and REPS should be modeled together, not separately.
Bonus Depreciation Phase-Down and Planning Windows
Bonus depreciation has been phasing down, which changes the value of timing. Acquisition dates, placed-in-service dates, and the timing of a cost segregation study all affect the amount and speed of deductions available.
As bonus depreciation declines, the margin for timing errors gets smaller. A delayed acquisition, delayed placed-in-service date, or missed REPS year can reduce the value of accelerated depreciation significantly.
That is why 2026 and 2027 planning matters now. The interaction between depreciation timing and passive loss treatment determines real cash-tax outcomes.
When Accelerated Depreciation Backfires
Accelerated depreciation backfires when it creates large passive losses that cannot be used currently. Investors often celebrate the size of the deduction without asking whether the loss is actually usable.
If REPS fails, or if material participation fails, cost segregation may simply enlarge suspended losses. The return looks tax-efficient on paper while cash taxes remain stubbornly high. That is not successful planning. That is a classification failure.
2026, 2027 Tax Law Changes: What Changes and What Stays the Same
This is where many investors conflate unrelated rules. REPS itself sits in IRC §469. The TCJA sunset affects other parts of the planning environment.
REPS Rules That Do Not Expire
The core REPS tests under IRC §469(c)(7) do not expire on the TCJA sunset schedule. Unless Congress changes that statute, the two qualification tests and the material participation framework remain in force.
So the REPS question is not “Will the rule vanish?” The right question is “Will the tax value of qualifying change because rates, deductions, and depreciation rules change around it?” The answer is yes.
TCJA Provisions That Affect Real Estate Planning
The scheduled sunset affects individual tax rates, bracket structure, and potentially the qualified business income deduction framework. Estate and gift exemption levels are also set to change significantly if current law sunsets as scheduled.
For real estate investors, that means the value of ordinary deductions, income shifting, succession strategy, and exit timing all move. A deduction used in one rate environment has different value in another. Entity planning also deserves review if expiring rules alter the economics of pass-through income.
Depreciation and Deduction Changes Already in Motion
Not all change waits until 2026 or 2027. Bonus depreciation phase-down is already in motion. Other deduction limits and capitalization timing issues also affect how much benefit accelerated depreciation creates today versus later years.
That means the planning window is active now, not at the sunset date. Waiting until the rules are closer to expiring usually means missing the operating year needed to support the return position.
Strategic Moves Before the Sunset Window Closes
The recommendation is to focus on five planning actions before the window narrows further: evaluate grouping elections, strengthen logs immediately, model cost segregation and bonus depreciation timing, review entity structure and income character issues, and align actual work hours with the intended filing position.
This is not a paperwork exercise. It is resource allocation. If your intended tax result depends on direct management, then your operating model needs to reflect that before year-end.
How to Determine If Pursuing REPS Makes Financial Sense
Not every investor should pursue REPS. The right question is not “Can a return be filed this way?” The right question is “Does the expected tax benefit justify the operating burden and audit risk?”
The Five Drivers of REPS ROI
Five drivers determine the return on the effort.
First, ordinary income level. The higher your wages or business profit, the more valuable current rental losses become.
Second, expected depreciation. Portfolios with large depreciation deductions, especially after cost segregation, generate more tax value from non-passive treatment.
Third, property count and complexity. More properties often create more operational hours, but also more recordkeeping burden. Grouping often matters here.
Fourth, management style. Direct self-management strengthens both qualification and documentation. Heavy outsourcing reduces both.
Fifth, time availability. If your non-real-estate workload is too large, the compliance system does not matter because the statutory math still fails.
A Simple Decision Framework
Use a five-step decision process.
Estimate expected current-year rental losses and accelerated depreciation. Test whether the 750-hour and more-than-50% thresholds are realistically achievable. Assess whether material participation can be proven, especially with or without grouping. Evaluate whether you can maintain contemporaneous documentation all year. Compare expected tax savings against the compliance burden and audit exposure.
If the tax savings are small, the case for REPS is weak. If the savings are large but your workload facts are poor, the position is still weak. The strongest situations combine large losses, direct involvement, available time, and disciplined records.
When the Recommendation Is to Skip REPS
Skip REPS when expected losses are modest, when operations are heavily outsourced, or when a full-time non-real-estate job makes the more-than-50% test unrealistic. Skip it when your recordkeeping behavior is inconsistent and your business model is fundamentally passive.
In those situations, other strategies usually produce better ROI. That may include focusing on long-term passive loss accumulation, disposition planning, debt management, entity simplification, or a short-term rental structure where the facts support a different classification path.
The recommendation is to pursue REPS only when the operating facts are strong enough that the return position feels ordinary, not heroic.
A Step-by-Step Plan to Qualify and Defend the Position
A workable REPS strategy follows phases. That keeps the filing position tied to real operations instead of tax-season storytelling.
Phase 1: Confirm Eligibility Before Year-End
Review total projected work hours across all trades and businesses. Measure real estate hours separately from all other service hours. Confirm whether qualifying real property services exceed non-real-estate services. Identify whether one spouse, not both combined, can independently satisfy the REPS tests.
If the numbers do not work by midyear, forcing the claim later is a mistake. Adjust the operating model or abandon the position early.
Phase 2: Set Up the Documentation System
Start the time log January 1. Use the four-field template for every entry: date, activity performed, hours spent, property address. Track tasks weekly. Retain supporting records in digital folders by property and month.
This is the minimum standard:
| Date | Activity performed | Hours spent | Property address |
|---|---|---|---|
| 02/11/2026 | Tenant call, lease amendment, follow-up email | 0.9 | 15 Lake View Dr, Tampa, FL |
| 02/11/2026 | Drove to property, inspection after roof repair | 1.1 | 15 Lake View Dr, Tampa, FL |
| 02/12/2026 | Coordinated appliance replacement with vendor | 0.7 | 84 Bay St, Tampa, FL |
The system should also maintain a separate noncounting list so investor-type hours are not mixed into the annual total.
Phase 3: Decide on Grouping and Management Structure
Evaluate whether each property stands a fair chance of meeting a material participation test separately. If not, review whether grouping all rental real estate interests into one activity strengthens the position.
At the same time, assess outsourced functions. If a property manager handles most leasing, repairs, and tenant contact, your hours and material participation evidence weaken. If REPS is the objective, direct management often needs to increase.
Phase 4: Coordinate With Cost Segregation and Filing Strategy
Model the tax value of anticipated depreciation. If a cost segregation study is planned, confirm that REPS and material participation are on track before assuming current-year benefit. Review NIIT implications separately. Make sure return disclosures, grouping statements, and Schedule E treatment align with the actual facts.
This is where tax planning either creates ROI or just creates large suspended losses.
Phase 5: Prepare for Audit Before Filing
Before filing, reconcile total hours to calendars, emails, invoices, and mileage. Review whether the more-than-50% test is satisfied using actual annual totals, not estimates. Confirm which spouse is claiming REPS. Verify grouping election status. Remove noncounting hours. Identify weak entries and replace them with supported descriptions if contemporaneous records exist.
A pre-filing audit review is not excessive here. It is standard risk management for a high-value, high-scrutiny return position.
Frequently Asked Questions About IRS Real Estate Professional Status
How many properties are needed to qualify?
No minimum property count exists. Qualification depends on hours, qualifying real property services, and material participation, not on owning a specific number of rentals. One time-intensive property can support qualification. Ten lightly managed properties can still fail.
Can one spouse qualify for both spouses on a joint return?
One spouse must independently satisfy the REPS tests. One spouse cannot use the other spouse’s personal service hours to meet the 750-hour and more-than-50% thresholds. But spouse participation can still matter in material participation analysis for the activity on a joint return.
Can a property manager be used and still claim REPS?
Yes, but the position becomes weaker. Outsourced management reduces your countable operational hours and makes it harder to prove material participation, especially under the substantially-all and more-than-100-hours-and-more-than-anyone-else tests.
Does flipping houses count toward REPS?
Development, construction, reconstruction, acquisition, and related real property trades can count toward REPS if they are real property trades or businesses in which material participation exists. But dealer activity and rental activity have different tax consequences, so do not assume that flipping and rentals produce identical treatment across all issues.
Do education, networking, and market research hours count?
No, not generally. Education, seminars, networking, broad market research, reviewing financial statements, and searching for new deals are usually investor or educational activities, not qualifying personal services for REPS hours.
Is an LLC or S corporation required?
No. Entity choice does not create REPS. The issue is your personal services and participation under IRC §469. An LLC can hold rentals and an S corporation can operate a real estate business, but neither entity election substitutes for actual qualifying hours and material participation.
What happens if the IRS denies the claim?
The rental losses are reclassified as passive and suspended unless another rule allows current use. You also face additional tax, interest, and possible accuracy-related penalties. If large cost segregation deductions were used, the adjustment can be substantial.
The Recommendation: Build a Year-Round REPS System, Not a Year-End Story
The recommendation is decisive: pursue REPS only when annual hours, direct operational involvement, grouping strategy, and contemporaneous records all align. If your filing position depends on reconstructed logs, investor-type hours, or a full-time W-2 schedule that overwhelms your real estate time, the claim is weak and the downside is expensive.
A winning REPS position is built during the year. It starts on January 1 with a live time log, not in December with a spreadsheet from memory. It is tested against IRC §469 before filing season, supported by property-level records, and coordinated with cost segregation, grouping, and income-planning strategy while those decisions still change the outcome.