
Real estate professional passive loss rules decide whether your rental losses reduce this year’s tax bill or sit on the shelf for years. That is not a technical footnote. It changes cash flow, after-tax ROI, and the value of strategies like cost segregation. In plain English, rental real estate is passive by default under IRC §469, which means losses generally offset only passive income. Real Estate Professional Status, or REPS, is the narrow exception that can turn rental losses into current deductions against nonpassive income, but only if the annual hour tests and material participation rules are met and proven.
Early navigation matters here because the rules stack on top of each other. This guide covers:
- the three-tier framework for rental loss treatment
- the two REPS qualification tests
- material participation and grouping elections
- substantiation standards and audit failures
- the $25,000 special allowance
- suspended losses and taxable dispositions
- short-term rental exceptions
- NIIT, cost segregation, and spousal planning
- pre-2026 and 2027 planning moves
- real-world qualification scenarios
- frequently asked questions
Why Real Estate Professional Status Changes the Economics of Rental Losses
The strategic stake is simple: suspended losses reduce current-year tax benefit, weaken after-tax cash flow, and delay the ROI from depreciation. If your rentals generate large paper losses from interest, repairs, and depreciation but those losses stay passive, the tax value is deferred. If those same losses become nonpassive, you can offset wages, consulting income, or operating business income now.
That is why REPS matters so much. Under the passive activity rules, rental real estate is generally passive even if you spend real time managing it. REPS is the exception built into §469(c)(7), but it is not a blanket pass. You still need material participation in the rental activity itself.
What the field data shows is blunt: many taxpayers focus only on the 750-hour headline and ignore the more-than-50% test, the separate material participation analysis, and documentation. That is exactly how otherwise strong returns get disallowed on audit.
The Three-Tier Framework: Passive Rentals, Active Participation, and REPS
The cleanest way to understand the rules is through three tiers. Each tier produces a different tax outcome.
Tier 1: Rental Real Estate Is Passive by Default
The default rule controls unless you prove an exception. Under IRC §469, rental real estate is passive as a matter of law, not based on your feelings about how hard you work. Long-term residential rentals usually land here. If you have passive income from other sources, passive rental losses can offset it. If not, the excess loss is disallowed for the year and carried forward.
That baseline surprises owners who self-manage several properties. Effort alone does not convert a rental into a nonpassive activity.
Tier 2: Active Participation and the $25,000 Special Allowance
Active participation is the middle tier. It is easier to satisfy than material participation and much easier than REPS. If you own at least 10% of the property and make bona fide management decisions, such as approving tenants, setting rental terms, and authorizing repairs, you can often qualify for the special allowance.
That allowance generally permits up to $25,000 of rental loss to offset nonpassive income, but it phases out between $100,000 and $150,000 of modified adjusted gross income. Above that range, the allowance is gone. For many high-income W-2 households, this benefit disappears entirely.
Tier 3: REPS Plus Material Participation
This is the top tier and the one that changes outcomes dramatically. If you qualify as a real estate professional and materially participate in the rental activity, the rental loss becomes nonpassive. That means no $25,000 cap and no passive basket trap.
The recommendation is to think of REPS as a two-key system. One key is annual REPS qualification. The second key is material participation in the rental activity or validly grouped rental activity. Without both keys, the deduction stays locked.
The Legal Foundation: IRC §469, Rental Activity Rules, and What Actually Controls
A lot of commentary on this topic oversimplifies the statute. The controlling framework comes from IRC §469, related Treasury regulations, and IRS guidance in Publication 925. General articles are useful for explanation, but the code and regulations decide the result.
The Passive Activity Loss Limitation
Section 469 limits passive activity losses to passive activity income. If passive losses exceed passive income, the excess is suspended, not lost. That distinction matters. A disallowed loss still has value, but the value is delayed until you generate passive income or dispose of the activity in a fully taxable transaction.
That deferral can last years. For an investor counting on depreciation to shelter W-2 or business income, passive treatment destroys the timing benefit.
How Rental Activity Is Defined for Tax Purposes
A rental activity generally exists when tangible property is used by customers and gross income is paid mainly for that use. Average customer use matters because certain short-duration stays can pull an activity out of the rental bucket. But most long-term residential leases are classic rental activities and are passive by default.
This is why ordinary landlords do not get nonpassive treatment just by working hard. The rental label itself drives the passive presumption.
Where REPS Fits Into the Statute
REPS sits inside §469(c)(7). That provision removes the automatic passive characterization for rental real estate activities, but only for a taxpayer who satisfies both statutory tests for the year. Even then, the rentals become nonpassive only if material participation exists in the relevant activity. The nonpassive Schedule E treatment follows from meeting both steps.
The Two Core REPS Qualification Tests
REPS is tested every tax year. Prior-year qualification does not carry forward. A strong 2025 file does nothing for 2026 if the hours and facts change.
The More-Than-50% Personal Services Test
More than half of your total personal services in all trades or businesses during the year must be performed in real property trades or businesses in which you materially participate. This test is where most full-time W-2 earners fail.
Use the math, not hope. If you work 2,000 hours in a non-real-estate W-2 job, you need at least 2,001 hours in qualifying real property trades or businesses to have more real estate service hours than non-real-estate service hours. That creates 4,001 total work hours for the year. At 52 weeks, that is roughly 77 hours every week without a break. A W-2 employee earning $200,000 with a normal full-time schedule does not have a defensible REPS case on those facts.
Employee hours create another trap. Personal services as an employee in a real property trade or business do not count for REPS unless you own more than 5% of the employer, as Publication 925 states. So a salaried employee at a real estate company does not automatically get credit for those hours.
The 750-Hour Test
The second gate is more than 750 hours of services during the tax year in real property trades or businesses in which you materially participate. This is necessary, but never sufficient by itself.
A retired investor who logs 900 hours across rentals, leasing, and operations can pass this test. A real estate agent with 1,400 hours in brokerage and rental operations can pass this test. A spouse managing eight rental properties and spending 1,100 hours on leasing, repairs, bookkeeping, contractor coordination, and tenant issues can pass this test. But if the more-than-50% test fails, REPS still fails.
What Counts as a Real Property Trade or Business
The statute covers development, redevelopment, construction, reconstruction, acquisition, conversion, rental, operation, management, leasing, and brokerage. Hours in these categories count only if tied to a real property trade or business in which material participation exists.
That last phrase matters. Time spent passively reviewing investment options or reading market articles does not become qualifying time just because it concerns real estate.
Material Participation: The Requirement That Decides the Deduction
Material participation is the second gate, and for many taxpayers it is the decisive one. REPS changes the character rule. Material participation determines whether the rental loss is actually nonpassive.
The Seven Material Participation Tests
Treasury regulations provide seven tests, and satisfying any one test is enough. The most practical for rental owners are these: more than 500 hours during the year, participation constituting substantially all participation in the activity, or more than 100 hours with nobody else participating more.
Other tests involve prior-year material participation patterns and facts-and-circumstances analysis. Those routes exist, but they are less clean in audit. For planning purposes, hours-based tests create the strongest file.
Why 500 Hours Is Common but Not the Only Path
Many advisors talk as if 500 hours is the only route. It is not. It is simply the easiest route to document and defend. If your activity qualifies under the substantially-all test or the 100-hour-and-no-one-more test, material participation can still exist.
That matters if you outsource some work but still remain the dominant operator. It also matters for grouped activities, where the combined hour total can clear 500 comfortably.
Participation That Does Not Count
Investor-level activity is a recurring audit problem. Reviewing financial statements, monitoring appreciation, arranging financing as an owner, or making occasional high-level strategic decisions does not carry the same weight as operating the rental business. Work not customarily done by owners can also be excluded in the wrong fact pattern, especially if it is performed mainly to manufacture hours.
Double counting is another failure point. Driving to a property and handling three tasks does not create three separate two-hour entries. Hours must reflect actual time, real tasks, and credible support.
The Grouping Election: When Treating All Rentals as One Activity Improves the Outcome
For owners with multiple properties, the grouping election is often the difference between a workable REPS case and a failed one.
How the Election Works
By default, each rental real estate interest is treated as a separate activity. That means material participation is tested property by property. If you have eight rentals and spend 120 hours on each, you can look busy all year and still fail 500 hours on every separate activity.
The election under Treas. Reg. §1.469-9(g) allows you to treat all interests in rental real estate as a single activity for material participation purposes. You generally make the election by filing the required statement with a timely filed return for the first year you want it to apply. Based on analysis of IRS guidance, late relief can exist in limited circumstances, but planning should assume the election needs to be made correctly the first time. Once made, it is not freely reversible and generally requires IRS consent to change.
Benefits of Grouping for REPS Claims
Grouping lets you aggregate hours across properties. That means 120 hours on each of eight rentals becomes 960 hours in one combined rental activity rather than eight separate failures. For owners with multiple long-term rentals, that is often decisive.
It also reduces the risk of losing nonpassive treatment because one smaller property received less hands-on time. From a business-outcome perspective, grouping improves the odds that cost segregation deductions, repair spikes, and other losses produce current-year tax value.
Risks and Tradeoffs of Grouping
The catch is future flexibility. Grouping can affect how suspended losses are released when you sell one property. If all rentals are one activity, selling a single property does not necessarily trigger the same loss-release result as selling an entire separate activity. Grouping can also lock you into a structure that no longer fits your portfolio years later.
The recommendation is straightforward: use grouping when your operating model depends on aggregated hours and your time is spread across many properties. But model the disposition consequences before making the election.
What Hours Count, What Hours Fail, and How Courts Evaluate Proof
Based on analysis of Tax Court outcomes, documentation decides a surprising number of REPS cases. Strong facts with weak records often lose.
Contemporaneous Time Logs: The Standard That Wins
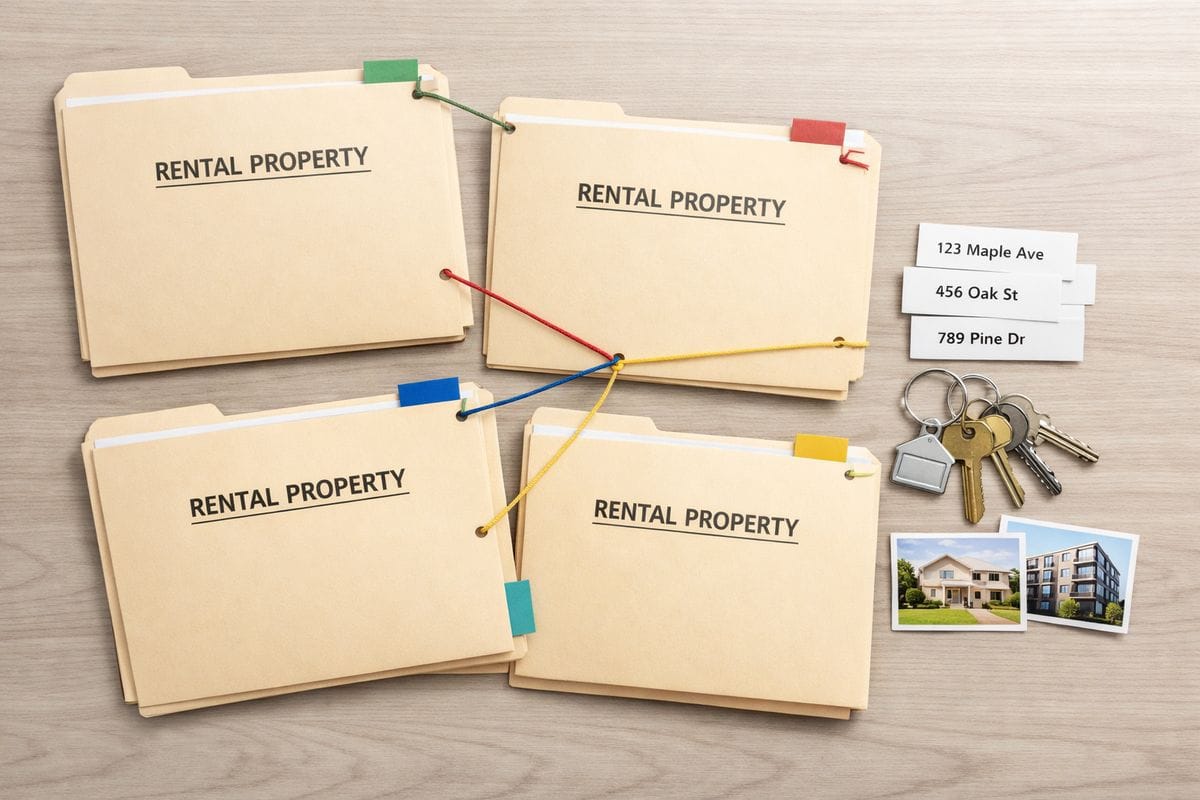
The winning standard is a contemporaneous log. That means recording work close to the time performed, not reconstructing it at year-end. A defensible log includes the date, the property or grouped activity, the task performed, duration, and enough detail to connect the task to real property operations.
Court decisions repeatedly punish vague summaries like “property management, 8 hours” or “tenant issues, 10 hours.” The better entry says: “3/14, Maple Street duplex, reviewed delinquency ledger, called tenant, met plumber, approved water heater replacement, 2.6 hours.”
Examples of Credible Supporting Records
A time log is stronger when third-party records back it up. Strong support includes calendars, emails, text threads with contractors, mileage records, invoices, lease files, bank and card records, property management software timestamps, phone logs, and vendor communications. The recommendation is to build a file that tells one consistent story.
The tax literature and court commentary strongly favor contemporaneous time logs with corroborating records over after-the-fact estimates.
Common Recordkeeping Failures
The most common failures are predictable: round-number entries, inflated daily hours, missing dates, annual estimates, duplicated tasks across properties, and logs that conflict with W-2 work schedules or travel records. If your calendar shows you at an office from 8 a.m. to 6 p.m. every weekday, a parallel claim of 35 weekly rental hours needs extraordinary support.
Cases like Harnett and Bosque turned heavily on substantiation. The pattern is clear. Courts do not reward enthusiasm. Courts reward precision.
The $25,000 Special Allowance: Useful, Limited, and Often Misunderstood
For many taxpayers, especially higher-income W-2 owners, the special allowance is the rule that actually matters. REPS gets attention because it is powerful. The $25,000 allowance gets used more often.
Who Qualifies for Active Participation
Active participation is a lower standard than material participation. If you own at least 10% of the rental and make meaningful management decisions, you are often in the running. Approving tenants, setting rent, authorizing repairs, and deciding on lease terms are classic examples.
This standard is practical for small landlords who are involved but not full-time operators. It does not require 500 hours. It does not require 750 hours. And it does not require more than half of your work time in real estate.
MAGI Phaseout Rules
The benefit is sharply limited by income. The special allowance starts phasing out at $100,000 of modified adjusted gross income and disappears at $150,000. The reduction formula is severe: the allowance falls by 50 cents for every dollar of MAGI above $100,000.
A simple example makes the point. If your MAGI is $120,000, you are $20,000 above the threshold. Your $25,000 allowance is reduced by $10,000, leaving $15,000 available. If your MAGI is $150,000 or more, there is no allowance left.
REPS vs. Active Participation
The standards and outcomes are completely different. Active participation is a lower bar with a capped benefit and an income phaseout. REPS plus material participation is a much higher bar with much larger upside because losses can offset nonpassive income without the $25,000 cap.
For a high-income household, active participation is usually a dead end once MAGI crosses the phaseout range. At that point, the real options are REPS, passive-income matching, short-term rental planning, or waiting for future release events.
Suspended Passive Losses, Carryforwards, and Dispositions
If your loss is disallowed this year, it does not vanish. But timing still matters because a dollar deducted today is worth more than a dollar deducted years later.
How Suspended Losses Carry Forward
Suspended passive losses carry forward indefinitely. Each year, they sit in the passive basket tied to the activity and become deductible when passive income arises or another rule allows release. This is deferral, not forfeiture.
Still, deferral has a cost. It lowers present-value tax savings and weakens the current-year benefit of depreciation-heavy strategies.
When a Sale Releases Suspended Losses
A fully taxable disposition to an unrelated party generally releases suspended passive losses from that activity. But not every transfer counts. Gifts, like-kind exchanges under prior law when applicable, certain related-party transactions, and partial transfers can produce very different outcomes.
This is where grouping decisions matter again. If rentals are grouped into one activity, the sale of one property inside that group does not automatically free all suspended losses tied to the broader grouped activity.
Planning Around Carryforwards
Planning should treat suspended losses as an asset with timing risk. Project passive income, likely disposition dates, refinancing plans, and entity structure. If a sale is expected in 18 months, the value of a suspended loss is much higher than if no release event is in sight for seven years.
The recommendation is to model the portfolio, not the property. Loss timing is portfolio math.
Short-Term Rentals, Average Stay Rules, and Why Some Investors Bypass REPS Entirely
This is where many investors miss a planning opportunity. Not every rental falls into the passive default bucket.
When a Rental Is Not Treated as a Rental Activity
If average customer use is short enough, or if substantial personal services are provided, the activity can fall outside the tax definition of rental activity for passive-loss purposes. That changes the analysis. Instead of starting with passive-by-default rental treatment, you move directly into material participation testing.
This is why some short-term rental owners do not need REPS at all. If the activity is not treated as a rental activity under the regulations, nonpassive treatment can follow from material participation alone.
Material Participation for Short-Term Rental Strategies
A short-term rental owner who materially participates can often treat losses as nonpassive without meeting the REPS tests. That can be far more achievable for a high-income taxpayer than trying to satisfy the more-than-50% personal services test.
But the facts must support it. You need the average-stay analysis, the services analysis, and the material participation record. Platform use alone does not establish the answer.
Where Investors Misclassify Short-Term Rentals
The biggest errors are sloppy average-stay calculations, confusion over cleaning versus substantial services, and assuming every Airbnb-style property is automatically nonpassive. It is not. A short-term rental strategy only bypasses REPS if the regulatory exceptions are actually met.
REPS and the Net Investment Income Tax (NIIT)
The tax impact does not stop with passive loss deductions. NIIT changes the economics of rental income and gains.
NIIT Thresholds and Core Rules
The NIIT rate is 3.8%. The threshold amounts are $250,000 for married filing jointly, $125,000 for married filing separately, and $200,000 for others. Once your modified adjusted gross income exceeds the threshold, net investment income becomes exposed to this surtax.
For rental-heavy portfolios, that can materially change after-tax yield.
When Rental Income Escapes NIIT
Nonpassive treatment can help move rental income out of net investment income, but NIIT has its own standards and requires separate analysis. Documented participation remains central. If the rental activity is a trade or business and your participation meets the applicable standard, NIIT exposure can drop.
This is a major reason REPS planning has value even in years without large losses. It affects ongoing income and, in the right fact pattern, gain on disposition.
The 500-Hour Safe-Harbor Concept in Planning
Practice often centers on the 500-hour safe harbor for certain NIIT planning. Broadly, participation for more than 500 hours in the current year, or more than 500 hours in five of the prior ten years, can support treatment of rental income and related gains as active rather than investment income.
Do not confuse this with REPS. NIIT planning and REPS overlap, but they are not the same test.
Cost Segregation, Bonus Depreciation, and Why REPS Amplifies the Tax Result
Many investors care about REPS because of one practical outcome: it turns accelerated depreciation into immediate tax value.
How Cost Segregation Increases Losses
A cost segregation study reclassifies building components into shorter recovery periods. That accelerates depreciation into earlier years. The front-loaded deduction can be large, especially when paired with bonus depreciation rules in effect for the year.
This strategy creates tax losses faster. It does not, by itself, determine whether those losses are usable now.
Why Passive Status Limits the Benefit
If the activity stays passive, accelerated depreciation often produces suspended losses rather than current tax savings. Your return shows a bigger paper loss, but your current-year tax bill does not move much. The economic benefit is delayed.
That is why passive status limits the value of aggressive depreciation planning.
When REPS Turns Depreciation Into Immediate Tax Value
When REPS and material participation are established, the same depreciation deduction can offset wages, business income, and other nonpassive income. That changes cash flow immediately. The business outcome is stronger after-tax liquidity and a higher near-term ROI on the property strategy.
This is the point many investors actually care about. REPS does not just change classification. It changes whether cost segregation pays off this year.
How Spouses, Joint Returns, and Household Work Allocation Affect Qualification
Household structure often determines whether REPS is realistic.
REPS Is Determined at the Taxpayer Level
REPS is tested separately for each spouse, even on a joint return. One spouse must independently satisfy both statutory tests. You cannot add your hours to your spouse’s hours to get over the line for REPS qualification. That is explicit in IRS guidance.
This is why the common high-income structure works: one spouse has substantial non-real-estate employment, the other spouse drives the real estate operations full time.
Material Participation on a Joint Return
Material participation is different. On a joint return, spousal participation is combined for material participation purposes. That distinction matters. One spouse can qualify for REPS, while both spouses’ hours together help establish material participation in the rental activity.
That split rule is technical, but operationally powerful.
Practical Scheduling for High-Income Households
Based on analysis of common household structures, the strongest REPS file is often a stay-at-home or part-time-working spouse who manages the rental portfolio directly. If that spouse oversees eight long-term rentals, handles leasing, maintenance coordination, rent collection, vendor management, bookkeeping, and property visits, a credible annual total of 1,000 to 1,400 hours is realistic. If outside non-real-estate work is minimal, the more-than-50% test becomes manageable.
That is the opposite of the $200,000 W-2 earner working 2,000 office hours. One profile fits the statute. The other fights math.
Real-World Qualification Scenarios
Rules make more sense when placed inside actual taxpayer profiles.
Full-Time W-2 Earner With Several Long-Term Rentals
A full-time W-2 earner with several long-term rentals usually fails the more-than-50% test. If your job consumes 2,000 hours, real estate service hours must exceed 2,000. That is the barrier, and it is usually fatal. What the field data shows is that taxpayers in this profile often overestimate management time and understate job hours, which increases audit risk.
The recommendation is not to force REPS. Use the $25,000 active participation allowance if MAGI allows, optimize suspended-loss carryforwards, or evaluate short-term rental rules where facts support that path.
One Spouse in Real Estate, One Spouse in a Non-Real-Estate Career
This is one of the strongest valid REPS structures. If one spouse has the outside career and the other spouse drives the rental operations, time logs, contractor oversight, tenant management, and bookkeeping, the qualification case is much cleaner. On a joint return, that structure can unlock nonpassive treatment for large depreciation losses.
The recommendation is to formalize the operating role, maintain detailed logs, and review the grouping election early.
Real Estate Agent or Broker With Rental Properties
A real estate agent or broker has a more natural path to REPS because brokerage is a real property trade or business. If brokerage hours and rental hours together exceed 750 and represent more than half of all personal service time, the REPS tests can be met. But rental losses still do not become nonpassive unless material participation exists in the rentals themselves or in a properly grouped rental activity.
The recommendation is to separate the two analyses in your records: qualification hours for REPS and participation hours for rentals.
Investor Using Third-Party Property Management
Outsourcing creates a predictable problem. The more operational work your property manager performs, the fewer hours you have available for material participation. High delegation weakens the claim that you were the primary operator.
This does not make REPS impossible. It does make the records and the remaining scope of your work far more important. If your role is mostly reviewing monthly statements and approving larger repairs, the claim is weak.
Audit Triggers and the Most Common Reasons REPS Claims Fail
The IRS audits REPS because the upside is large and the abuse pattern is familiar. The failure modes are not mysterious.
Failing the More-Than-50% Test
Demanding outside jobs are the first red flag. If your return claims REPS while your facts show a full-time non-real-estate career, the more-than-50% test often fails before the 750-hour analysis even starts. This is especially true where employer records, calendars, or travel schedules conflict with the claimed real estate hours.
Proving Hours With Estimates Instead of Records
Year-end reconstructions, round-number logs, and ballpark testimony are weak. Courts consistently favor specific, contemporaneous records over memory-based estimates. The documentation standard is not optional in a serious REPS file.
Assuming Management Ownership Equals Material Participation
Owning rentals, making strategic decisions, and occasionally stepping in during a crisis do not automatically satisfy material participation. The regulations look for actual operating involvement, and the burden is on you to prove it.
Ignoring Separate-Activity Rules
This is the quiet killer. Taxpayers often assume hours across multiple properties combine automatically. They do not. Unless you make a valid grouping election, each rental interest is generally a separate activity. A taxpayer can work 900 hours across a portfolio and still fail material participation on every individual property.
A Pre-2026 and 2027 Planning Checklist
The audience concern here is justified. Tax law changes around the TCJA sunset affect the value of deductions even if REPS itself does not change.
What Stays the Same
The passive activity loss regime under IRC §469, REPS standards, material participation tests, and the basic rental-loss framework stay in place unless Congress changes those rules directly. As of now, nothing in the expected TCJA sunset mechanics rewrites the REPS tests.
That means your planning foundation remains the same: qualify annually, document hours, address grouping, and test material participation.
What Changes Around the TCJA Sunset
What changes are the surrounding tax economics. Individual rates are scheduled to shift, bonus depreciation rules continue to phase down under current law, and other provisions such as qualified business income planning can change the after-tax value of deductions and rental income. A lower bonus percentage means less front-loaded depreciation. Higher individual rates increase the value of every deductible dollar that remains available. The interaction matters.
This is why 2026 and 2027 planning should not focus only on qualification. It should focus on timing.
Actions to Take Before Filing Season
The recommendation is to move through six actions before filing season:
- evaluate whether a grouping election is needed
- upgrade time tracking to contemporaneous logs
- assess cost segregation timing by property
- model MAGI and the $25,000 allowance
- review NIIT exposure on income and gains
- test whether operations support a defensible REPS file
That checklist drives tax outcome, audit durability, and time-to-value from depreciation strategies.
The Decision Framework: When Pursuing REPS Delivers the Highest ROI
Not every investor should pursue REPS. The right answer depends on facts, not ambition.
Best Fit Profiles for Pursuing REPS
The best fit includes households where one spouse is devoted to real estate operations, real estate agents or brokers with rental portfolios, retired investors with significant operating time, and owners planning major depreciation acceleration through cost segregation. These profiles combine available hours, clean math on the more-than-50% test, and high nonpassive income to offset.
In this kind of program, the tax ROI is strongest when current deductions shelter substantial wages or operating income and the documentation file is audit-ready from day one.
Cases Where the Better Strategy Is Not REPS
The better strategy is not REPS when your outside career dominates your time, when property management handles most operational work, when MAGI planning makes the active participation allowance partially available, or when a short-term rental structure offers a cleaner path through material participation without needing REPS.
A weak REPS claim is worse than no REPS claim. It creates audit risk, penalty exposure, and poor planning discipline.
Your Next-Step Tax Review
The recommendation is to run a year-by-year review built around four drivers: quantify hours, map each activity, confirm or reject grouping, and align documentation with the deduction outcome sought. If the math does not work in January, it will not work better in April. If the records are weak in real time, they will not become strong at year-end.
Frequently Asked Questions
Can a full-time W-2 employee qualify for REPS?
Usually no. If your non-real-estate job takes 2,000 hours, you need at least 2,001 hours in qualifying real estate trades or businesses to satisfy the more-than-50% test. That is why most full-time W-2 earners should not build a tax plan around REPS.
Does meeting 750 hours automatically make rental losses nonpassive?
No. The 750-hour test is only one part of REPS. You also need more than half of all personal service hours in qualifying real estate trades or businesses, and you still need material participation in the rental activity or grouped rental activity.
Can one spouse qualify for REPS on a joint return?
Yes. One spouse can independently satisfy the REPS tests, and that is enough for the joint return. But the qualifying spouse must meet both statutory tests alone. Spousal hours do not combine for REPS qualification.
Do all rental properties need 500 hours each?
No, not if a valid grouping election is in place. Without grouping, each rental is generally a separate activity and material participation is tested separately. With grouping, hours across all rental interests can be combined into one activity.
Are year-end estimates of hours good enough?
No. The strongest proof is a contemporaneous log supported by emails, calendars, invoices, mileage, lease records, and similar documents. Estimates prepared after the fact are one of the most common reasons claims fail.
If REPS is not realistic, what is the next-best strategy?
The next-best strategy is usually one of three paths: claim the $25,000 active participation allowance if MAGI permits, build and preserve suspended passive losses for future passive income or taxable dispositions, or evaluate whether short-term rental rules create a nonpassive path through material participation alone.